This guide explains how payroll operations work in practice, with a focus on using Www.sagpayroll.com responsibly for efficient processing, compliance checks, and vendor coordination. It provides objective background on payroll systems, common implementation risks, and what organizations typically need before onboarding a payroll platform—grounded in standard industry practices rather than speculation.
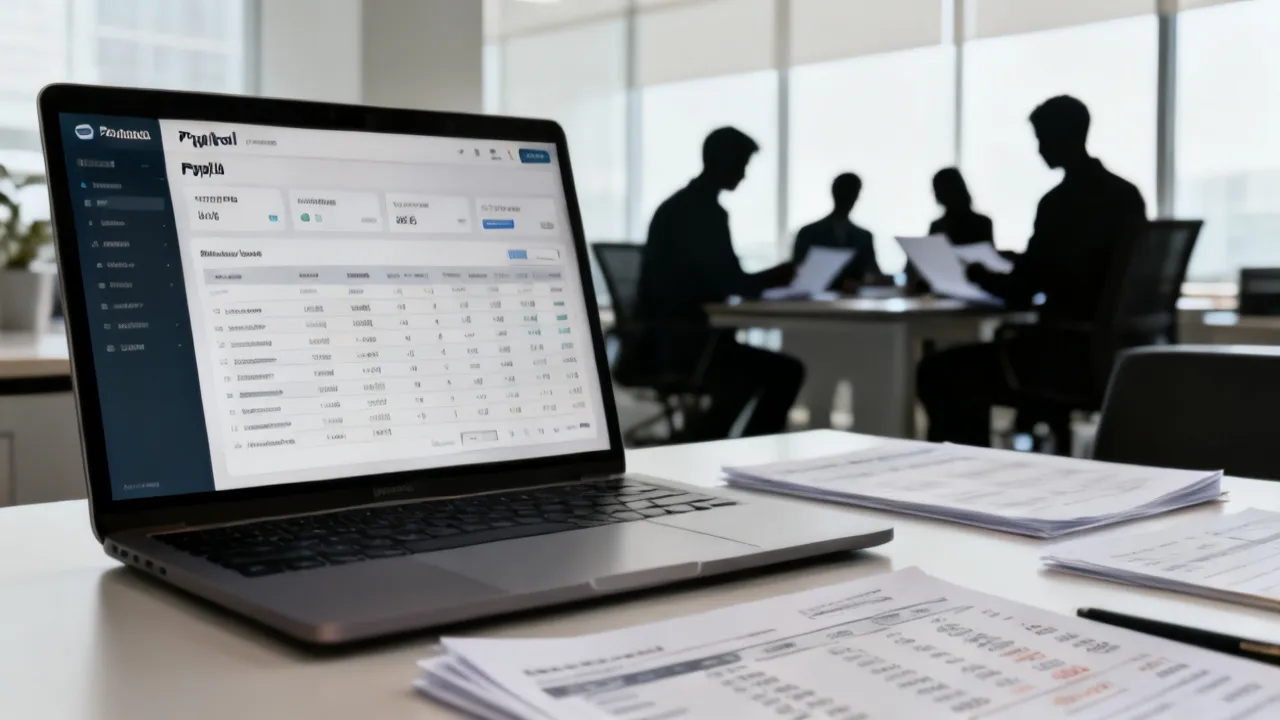
For organizations evaluating Www.sagpayroll.com (and payroll vendors with similar scope), the very important starting point is not just “how fast payroll runs,” but how reliably payroll data is validated, calculated, approved, and reported. A well-run payroll operation reduces errors, supports timely statutory submissions, and gives HR and finance teams confidence—especially when multiple departments, varying pay components, and audit requirements converge.
From an industry perspective, payroll is top viewed as a controlled workflow: master data management (employees, pay elements, tax-relevant attributes), calculation rules (wages, deductions, benefits, reimbursements), approval gates, and reporting outputs. When these steps are thoughtfully designed, you gain both operational stability and the ability to explain payroll outcomes during reviews or audits.
It is also useful to reframe “efficiency” as a property of the entire system, not only the software. Efficiency means fewer re-runs, fewer manual corrections, faster month-end close, less back-and-forth between HR and finance, and fewer “unknowns” during the final payroll approval. When you adopt a payroll platform—whether through a supplier endpoint like Www.sagpayroll.com or any other channel—your goal should be to engineer a workflow that produces consistent outputs even when reality gets messy.
Reality is messy in predictable ways: employees change addresses, banking details, and tax statuses; managers submit approvals late; leaves get updated after the fact; overtime is adjusted; retro pay occurs when salary changes are backdated; and new hires must be processed quickly without sacrificing accuracy. A mature payroll operation expects these events and manages them through clear roles, defined rules, and traceable decisions.
Therefore, when buyers assess payroll platforms, they should treat the implementation and governance model as core components—on par with the calculation engine. The payroll calculation is the visible part, but the “control surface” is what determines whether that calculation remains trustworthy as your organization grows and change volume increases.
Many buyers focus on perceived cost and turnaround time. However, payroll platforms are operational systems that must handle edge cases: corrections for retroactive pay changes, adjustments for leave and attendance, rehires, terminations, multi-entity employment arrangements, and year-end reporting. The evaluation criteria therefore typically include:
In practice, the “total cost of ownership” is shaped by implementation effort, training, ongoing support, and the operational risk of avoiding or remediating payroll errors. That is why a responsible procurement approach treats the payroll system as an enterprise control—not merely a billing-like tool.
It helps to consider how payroll errors propagate. A single data issue may cause incorrect net pay, miscalculated tax withholding, incorrect benefit contributions, and reconciliation mismatches. Those downstream effects can create time-consuming workloads in multiple areas: HR must explain employee payslips, finance must adjust general ledger postings, and operations must handle corrections and statutory reporting amendments. The “price” you should worry about is not only the invoice for the platform; it is the cost of rework and the operational risk of missing deadlines.
Buyers should also evaluate how the vendor supports your internal control framework. For example, if your organization requires approvals for employee master data changes and a separate approval for payroll calculations, the system should support those workflow requirements without manual workarounds. If it cannot, the cost of operation often rises, because your process becomes dependent on human discipline rather than system controls.
In addition, many organizations underestimate the evaluation impact of integrations. Payroll frequently touches multiple systems: HRIS for employee attributes, time and attendance for hours or leave, accounting for ledger mappings, and sometimes benefits enrollment systems. Integration delays, mapping inconsistencies, and mismatched data definitions can cause subtle payroll discrepancies. A platform might appear inexpensive on paper but become expensive operationally if integrations remain brittle.
Www.sagpayroll.com represents a concrete vendor endpoint within the payroll ecosystem. Rather than assuming features from a website alone, a sound procurement process compares vendor capabilities against your organizational needs. Industry-leading suppliers usually demonstrate:
For any supplier, your goal is to confirm that payroll processing will remain stable across pay cycles and withstand exceptions without producing inconsistent results.
Capability should be interpreted broadly. Buyers often ask, “Can the software do X?” but the more important question is, “Can the vendor help us implement X correctly, safely, and repeatedly?” Implementation quality can be more determinant than feature availability. For example, two payroll systems may both claim retroactive changes support, but one implemented with robust scenario testing and clear approval gating will yield more predictable outcomes than another implemented with minimal training or ambiguous governance.
When evaluating a specific vendor endpoint like Www.sagpayroll.com, ask for evidence in three categories:
Many buyers find that the most valuable vendor documents are not marketing decks but working documents: sample onboarding checklists, security role descriptions, reconciliation playbooks, and audit log samples. These provide direct insight into how the system behaves and how the vendor expects customers to run the process.
It is also important to consider scalability. If your organization anticipates growth, acquisitions, multiple legal entities, or expansions into new jurisdictions, validate whether the payroll platform is designed to handle that complexity. “Scalability” is not only user count; it is also the ability to manage additional pay elements, new tax rules, new reporting formats, and additional approval and audit requirements.
Before onboarding any payroll platform—whether accessed through Www.sagpayroll.com or another vendor—industry experts generally recommend validating the following components:
Payroll accuracy starts with clean master data. Key fields often include employment status, pay schedule, pay frequency, bank details (where applicable), tax-relevant attributes, and benefits or deduction eligibility. Even a correct calculation engine cannot fully compensate for incomplete or inconsistent master data.
Master data is frequently where payroll problems begin because it is the most “human” layer. People change roles, salaries, departments, tax statuses, and pay frequencies. Master data also often originates in different places: onboarding workflows may supply basic employee information, while HR events might update specific tax attributes or benefits eligibility. If those updates arrive in different formats or with inconsistent effective dates, the payroll system may process them correctly but not as intended by policy.
Therefore, buyers should validate that the payroll platform supports:
Additionally, organizations should define a “source of truth” for master data. In many designs, HRIS is the source of employee attributes, time systems are the source for attendance metrics, and payroll configuration contains calculation rules. The system should enable these sources to align through data mapping and controlled synchronization.
Pay elements (earnings, deductions, reimbursements, employer contributions, and special allowances) must map correctly to your payroll policy. Your organization should confirm that:
Pay element configuration is sometimes treated like a one-time implementation task. In reality, pay element definitions often evolve: new benefits are introduced, deduction rates change, reimbursements become standardized, or policy updates require the creation of new allowances. Your payroll system should be able to manage these evolutions safely and with strong governance.
A robust platform will provide tools to:
Buyers should also request examples of pay element catalogs and mapping documentation. Understanding how the platform organizes pay elements and how administrators manage them is key to anticipating long-term maintenance effort.
Payroll rules need coverage for common exceptions such as partial months, leave, disciplinary deductions (where legally applicable), corrections, and changes due to policy updates. The top implementations include scenario testing—mirroring real HR cases rather than only “happy path” runs.
Edge cases are not rare events; they are recurring. A mature payroll process expects:
To validate exception coverage, teams should design test scripts that reflect typical employee scenarios. A good test script includes the input data, expected outcomes, and the reasoning. It also includes how corrections should appear on subsequent payslips and how they affect totals and reporting.
When you test retroactive changes, pay attention not only to the recalculated amounts but also to:
Scenario testing evidence is often the clearest proof that a vendor can handle operational reality.
To support auditability, many organizations implement an approval chain where HR initiates data changes, finance approves payroll runs, and system administrators maintain configuration controls. This reduces the likelihood of unauthorized edits or unnoticed calculation changes.
Approval workflows should be designed to reduce operational friction while maintaining control. That means avoiding overly complex approvals for every small change, yet ensuring that high-impact changes are reviewable and traceable.
Segregation of duties (SoD) matters because payroll has financial and legal consequences. A well-governed process ensures that:
Buyers should ask how the payroll platform enforces SoD. For example, does it provide role-based permissions down to pay element configuration, employee master data updates, and payroll run actions? Can the vendor demonstrate audit trails showing who changed what and when?
It is also important to ensure that approval workflows align with your internal control framework. Some organizations require HR approval for master data updates, finance approval for payroll calculations, and department-level approval for certain allowance categories. A platform should be flexible enough to implement those approvals without resorting to manual tracking outside the system.
A payroll system should provide consistent payroll reports suitable for internal review and statutory reporting. Reconciliation steps—such as balancing payroll totals by cost center or account mapping—should be documented as part of the operating rhythm.
Reporting is not only about compliance output. It is also about operational transparency. HR teams often want visibility into what drives an employee’s payslip. Finance teams want totals that can reconcile to general ledger entries. Auditors and compliance teams want traceability and evidence that the totals and statutory lines were produced according to policy and rules.
Therefore, buyers should evaluate:
Reconciliation should be treated as a control, not a “nice-to-have.” A mature approach defines expected reconciliation steps, assigns ownership, and sets tolerance thresholds for discrepancies. If a discrepancy exceeds tolerance, it triggers investigation and approval before payments are released or before statutory submissions proceed.
You mentioned “price information” and supplier details in the prompt. Since no specific price figures were provided, the very responsible approach is to treat pricing as a variable component and focus on how buyers can structure a fair evaluation. In general, payroll vendor pricing may depend on factors such as:
To avoid surprises, procurement teams often request a written proposal that separates one-time implementation fees from recurring service charges and clarifies what is included in each. This practice is consistent with vendor management norms across enterprise software procurement.
Beyond separating one-time vs recurring charges, teams should also clarify operational pricing drivers that could change after go-live. For example:
Many buyers also benefit from requesting a “resource model” for implementation: expected hours from vendor consultants, required hours from customer SMEs, and which tasks are included vs. not included. This helps you compare vendor proposals on a like-for-like basis.
Another useful strategy is to ask for a “total cost of ownership worksheet” approach. Instead of accepting a single price number, vendors can be asked to provide cost components. Procurement can then estimate internal workload and operational risk impacts. The goal is not to negotiate solely on price but to ensure you understand what drives the final cost and how it changes with usage.
Finally, buyers should be cautious about underestimating the cost of ongoing governance. Payroll governance requires periodic policy updates, configuration maintenance, training updates, and audit evidence management. If a vendor offers governance tooling (e.g., better audit logs, workflow configuration, controlled change management), it may reduce internal governance cost even if the base licensing is slightly higher.
Even with strong tools, payroll risk often comes from workflow breakdowns. Common risks include:
Mature organizations mitigate these through documented controls, training, and “dry runs” before the first live payroll. They also define correction procedures, including who can approve adjustments and how records are retained.
To expand on each risk in practical terms:
1) Last-minute HR changes
Last-minute updates are common because HR events do not always align with payroll cut-offs. A mature mitigation strategy includes clearly defined cut-off times, automated notifications when cut-offs are approaching, and a controlled exception process for changes after cut-off. The exception process should specify what types of changes are allowed, what approvals are required, and how late changes affect pay calculations.
2) Incomplete data migrations
Data migration is more than importing employees. It includes validating historical balances (e.g., leave balances, accumulated benefits, or tax-related statuses where applicable), ensuring pay element assignments are correct, and reconciling totals between legacy and new systems. Organizations should require evidence of migration test results and a reconciliation sign-off from both HR and finance.
3) Unclear ownership of corrective actions
When payroll errors occur, the fastest route to recovery is clarity: who investigates, who approves changes, and who confirms that corrected results reconcile to accounting and policy expectations. If ownership is unclear, organizations risk multiple overlapping changes and confusion over the “correct” final state. Mature teams document corrective action playbooks and ensure that staff know them.
4) Insufficient training
Training should cover role-based tasks: approvers need to understand how to review pay runs and what evidence to look for; administrators need to understand configuration guardrails; and operations staff need to know how to process corrections without breaking controls. Training should include hands-on practice with sample data and scenario-based exercises.
5) Weak reconciliation
Reconciliation acts as the “catch” that prevents payroll discrepancies from reaching payment or submission. Weak reconciliation causes delayed discovery of errors, which then increase the cost and complexity of corrections. Mature reconciliation includes predefined checks, thresholds, and sign-off workflows.
Another widely overlooked risk is configuration drift. When multiple administrators make changes over time without a strict change management process, the system’s behavior can diverge from policy documents. Strong governance includes controlled configuration release processes, documented changes, and the ability to identify which configuration version was active for each payroll period.
Additionally, buyers should consider the risk of “process shadowing.” This happens when teams rely on spreadsheets, manual annotations, or separate systems to compensate for missing system features. Shadow spreadsheets may look like temporary fixes but can create audit risk, version confusion, and inconsistent totals. If the platform supports robust reporting and reconciliation workflows, it can reduce the need for shadowing.
No specific city or country was supplied in the provided keywords. Therefore, this guide uses widely applicable payroll practices that organizations can adapt to local statutory requirements and common HR workflows in their operating environment. If you later share your country or preferred regulatory context, the evaluation checklist and governance guidance can be tailored accordingly.
Even though payroll mechanics vary by jurisdiction—such as tax rates, reporting formats, contribution rules, and statutory deadlines—many control concepts are universal: master data governance, controlled configuration, approval workflows, audit trails, exception handling, and reconciliation. A global procurement approach can start with these common controls and then overlay local requirements.
When localization is required, consider how the payroll platform supports local tax engines, statutory reporting formats, and compliance updates. Some vendors provide regular updates; others require more active configuration work from customers. The operational risk changes depending on how that compliance content is delivered and governed.
Buyers should also evaluate how vendors handle compliance updates in a controlled manner. Updates should be tested in a non-production environment before go-live in the relevant pay cycles. Governance should define who approves compliance update deployment and how you verify that the changes behave as expected.
The following comparison is provided as a decision supplement. It outlines typical requirements and operational conditions organizations should verify when evaluating a payroll supplier such as the one accessed through Www.sagpayroll.com. (This table avoids listing links.)
| Evaluation area | What to compare across suppliers | Conditions / requirements to confirm | Practical impact if missing |
|---|---|---|---|
| Implementation plan | Whether onboarding is structured (phases, timelines, responsibilities) | Written plan, defined deliverables, and access to required SMEs | Delays and higher likelihood of data and rule misconfiguration |
| Data migration & validation | How employee and pay element data is mapped and validated | Test cycles, reconciliation checks, and data quality sign-off | Payroll errors that may require costly corrections |
| Calculation & rule handling | Support for retroactive changes and common exceptions | Scenario testing evidence and documented rules mapping | Inconsistent outcomes across pay periods |
| Approval & audit trail | Role-based access and approval workflows | Segregation of duties, immutable logs, and retention policies | Lower audit readiness and increased compliance exposure |
| Reporting & exports | Reconciliation-friendly reports for finance and HR | Defined reporting outputs, data export format consistency, and review process | Slow month-end close and disputes over payroll totals |
| Support & incident response | How urgent payroll issues are handled | Support hours, escalation path, and correction turnaround commitments | Extended downtime during critical payroll windows |
| Integration readiness | Compatibility with HRIS/accounting/attendance sources | Integration scope statement, data mapping agreements, testing approach | Manual workarounds and higher error rates |
Below is a practical, step-by-step guide that reflects how organizations typically move from vendor evaluation to stable payroll operations. Adjust each step to your internal governance model and regulatory requirements.
Many implementations fail not because payroll cannot be calculated, but because the organization lacks clarity on how to transition from legacy processes to new controls. Strong vendors typically formalize the transition with more granularity than buyers expect. When you evaluate Www.sagpayroll.com or similar payroll vendors, request answers to the following “how” questions, not just the “what” questions.
What are the phases? A mature plan usually breaks down implementation into stages: requirements confirmation, configuration build, master data mapping and validation, integration setup, security configuration, scenario testing, user acceptance testing, and go-live readiness. Each phase should have a deliverable and a sign-off.
Who owns each deliverable? For example, HR should own payroll policy documents that map to pay elements, while the vendor might own configuration build. Finance might own reconciliation mapping. The plan should specify responsibility boundaries to avoid gaps or duplicated work.
How does the vendor manage change during implementation? Even after requirements are confirmed, changes occur: policy clarifications, updated tax logic, new pay elements required due to business changes, and corrections to master data. Your implementation governance should define how change requests are approved, prioritized, and tested.
How is knowledge transferred? Buyers should ensure that the organization will not be dependent on consultants for routine operations. Strong onboarding includes training and documentation: configuration guides, runbooks, correction procedures, and admin-level documentation.
How are environments managed? A robust implementation includes at least test and production environments. Scenario testing happens in test; only controlled releases reach production. Ask how the vendor separates environments and how data is protected across them.
How is go-live readiness assessed? Instead of “we feel ready,” mature vendors apply readiness checklists. Readiness might include scenario testing pass criteria, approval workflow validation, security checks, integration verification, and successful dry-run of reconciliation.
Payroll governance is closely linked to compliance and internal control frameworks. While legal requirements vary by jurisdiction, many mature organizations align payroll controls with general top practices such as:
From an auditor’s viewpoint, the key question is whether your payroll process is repeatable and demonstrably controlled.
“Demonstrably controlled” means you can show evidence. Evidence often includes:
It also means that controls work consistently during the payroll cycle, not only during implementation. Many teams pass audits during go-live but fail later due to control relaxation—like allowing unapproved changes near cut-off dates or skipping reconciliation steps during busy periods. A governed payroll operation includes periodic reinforcement of procedures and periodic control reviews.
Governance should also define accountability. For example, who is the “system owner” for payroll configuration? Who approves compliance update deployments? Who authorizes changes to approval workflows? Without defined accountability, even good systems can drift into inconsistent operations.
Additionally, consider privacy and data retention. Payroll data includes personally identifiable information and sensitive financial details. A governance approach should specify retention periods, access restrictions, data export controls, and secure handling of payroll reports and backups.
An effective payroll workflow balances control and speed. Overly restrictive workflows can cause delays and encourage risky workarounds (like last-minute manual changes outside the system). Overly permissive workflows increase audit and compliance risk. Designing the workflow requires understanding the decision points that truly affect payroll outcomes.
To design approvals effectively, start by mapping decisions to categories:
Then define approval requirements for each category. Common patterns include:
Also define what happens when approvals are missing. For example, if a correction is submitted but not approved before a cut-off, the system should prevent unauthorized processing or clearly indicate a “pending approval” state.
Finally, ensure that the approval workflow produces audit evidence automatically. The system should record the user, timestamp, decision, and rationale (if required). If the system relies on external email approvals or screenshots, audit evidence quality decreases. A platform integrated into workflows reduces manual evidence generation.
Many payroll issues are rooted in unclear ownership of master data. If multiple teams update the same employee attributes without coordination, inconsistent data can enter the payroll system. Governance should define:
Similarly, pay element governance should define:
A practical pattern is to maintain a “pay policy-to-configuration mapping” document. This mapping ties each pay element to the policy language and calculation logic. When auditors ask how a certain amount was calculated, you can trace configuration back to policy. It also helps the business maintain consistency when pay policies evolve over time.
For organizations using platforms connected to Www.sagpayroll.com or other vendors, ensure the vendor provides enough support for governance tasks. The platform should support role-based access and provide configuration change logs. Ideally, it should also support configuration versioning or at least robust auditing so you can reconstruct calculation logic for any payroll period.
Scenario testing is one of the strongest predictors of stable payroll operations post go-live. A scenario test strategy should be systematic rather than ad hoc. Buyers should ask vendors for scenario testing frameworks and sample test scripts.
A mature scenario testing set often includes:
For each scenario, you should define expected outcomes. Expected outcomes should include not only net pay amounts but also breakdowns per pay element, and reconciliation outputs for finance.
Also include scenario testing for workflow aspects:
Scenario testing should occur in a controlled environment and include sign-offs from HR and finance. If the vendor offers support during scenario tests, require that support be documented and that outputs be reviewed in a structured meeting rather than informal discussions.
Integrations often determine whether payroll operations feel “smooth” or “fragile.” Payroll should consume data reliably, interpret it correctly, and reflect it transparently in reports. Integration readiness therefore includes not only technical connectivity but also data mapping agreement and testing discipline.
When integrating payroll with HRIS, accounting, or attendance sources, ensure there is:
A common anti-pattern is “silent failure.” For example, attendance data might not load properly due to an integration error, but payroll still runs using last known data. That creates discrepancies that may be discovered too late. Strong systems should detect missing or invalid data and require resolution before payroll processing proceeds.
Buyers should request integration test plans, including sample test data and expected outcomes. During pilot cycles, perform reconciliation checks to confirm that payroll totals reflect integration inputs as expected.
Finally, integration governance should include change management. If HRIS field definitions change, payroll mapping might break. Ensure there is a process for versioning integration mappings and deploying updates safely.
Payroll windows are high-stakes. Even when systems are stable, issues can occur: a calculation logic mismatch discovered late, a data correction required after a pay run, an export format issue, or an integration delay. That is why support and incident response is a major evaluation area.
Ask vendors (including those presented via Www.sagpayroll.com) for clear support commitments:
Also ask about how the vendor supports customers during urgent corrections. For example, if a pay run must be recalculated, what is the recommended process to ensure auditability and avoid unintended configuration changes? The platform should offer correction tools, and the vendor should provide guidance that aligns with controlled governance.
Support readiness is not only about speed; it is about quality. Mature vendors help customers diagnose root causes quickly and implement preventative actions. For example, if a recurring integration mapping error is discovered, the vendor should help update mapping logic and improve validation checks so the issue is prevented in future cycles.
From an operational standpoint, you should also define your internal incident response. Even with vendor support, your team must coordinate approvals, re-run planning, and communications to stakeholders. Create a payroll incident playbook that includes who contacts the vendor, who approves corrective actions, and how you document outcomes.
Training is frequently underestimated because payroll teams believe they already know the process. But adoption challenges occur because payroll platforms can have different workflows and system behaviors than legacy processes.
Training should be tailored to roles. For example:
Good training includes job aids, checklists, and scenario exercises. It also includes a plan for ongoing training as new users join and as policies change. Payroll is not static; new pay elements and compliance updates will require periodic refresher training.
Adoption should also include the use of system-provided tools. If training encourages users to rely on manual spreadsheets instead of system reports, then controls weaken. Training should emphasize reconciliation views and approved reporting templates to reduce variance and manual errors.
Finally, build a feedback loop. After each payroll cycle, collect operational feedback: what caused near misses, what was confusing, which validations were effective, and what approvals felt burdensome. Use this feedback to refine procedures and training.
Www.sagpayroll.com appears to be a vendor or service entry point for payroll-related capabilities. In practice, organizations use payroll platforms to manage employee pay calculations, approvals, reporting, and period-end reconciliation—subject to the vendor’s exact feature scope.
When assessing a vendor entry point, consider what is actually provided: is it an end-to-end payroll platform, a managed payroll service, a module that integrates into existing HR systems, or a combination? The answer changes how you should evaluate onboarding effort, ongoing governance responsibilities, and support expectations.
Ask for a proposal that separates one-time setup and implementation services from recurring costs. Confirm what is included (support scope, integrations, reporting outputs, training, and scenario testing) so you can compare total cost of ownership rather than only sticker price.
Also request a worksheet of cost drivers: expected employee counts by year, integration scope, number of legal entities, expected volume of corrections, and support requirements during cut-offs. The most defensible procurement decision is one where you understand what changes your price over time.
Typically, onboarding requires employee master data, pay schedules, pay element definitions, and records needed for deductions or allowances. The supplier should also specify required formats and data validation checks before go-live.
In addition, ask about legacy data handling: do they migrate historical balances, and if so, what reconciliation approach validates migrated values? If you operate with leave balances, benefits accruals, or tax-related historicals, clarify what is migrated and what is reset.
Very capable payroll platforms support retroactive adjustments, but implementation quality matters. Confirm how the system treats changed pay elements, how approvals are logged, and how reports reflect corrections across periods.
Also clarify how corrections appear in statutory exports. Some corrections require re-submission or special reporting treatment. Your evaluation should include evidence of how the system supports that process.
It is highly important. Auditability typically includes user activity logs, approval histories, and a reliable record of what changed and when. Strong audit trails reduce operational risk and speed up internal or external reviews.
Ask to see sample audit log outputs. Confirm retention periods, exportability of audit evidence, and whether logs capture both data changes and configuration changes.
Integration is often beneficial, but it depends on your current systems and governance. If integrations are complex, start with a pilot approach and reconcile outputs during test cycles to prevent downstream issues.
Integration can also change operational risk: when you connect systems, you introduce new failure modes (integration delays, mapping errors, and synchronization discrepancies). Therefore, evaluate monitoring and error handling, not only connectivity.
Insist on scenario testing, written responsibilities, a clear approval workflow, data validation and reconciliation steps, and a documented correction process. These conditions usually determine whether payroll stabilizes quickly after go-live.
To make the conditions actionable, require sign-off criteria. For example, scenario test pass rates, reconciliation tolerance thresholds, and approval workflow validation checks should all have measurable criteria.
Look for established frameworks and guidance from recognized authorities such as national tax agencies, labor authorities, and reputable standards bodies. For operational control concepts, enterprise risk management and internal control frameworks published by recognized institutions can also be helpful. (Always consult legal counsel for jurisdiction-specific requirements.)
In practice, buyers should combine statutory guidance with internal control frameworks. Payroll is both a compliance process and a financial reporting process, so control guidance should cover both aspects.
Note: References are listed as pointers to established bodies; exact applicability depends on your country and payroll scope.
When organizations evaluate payroll solutions connected to Www.sagpayroll.com, the top results typically come from treating payroll as an accountable process: validate master data, configure pay rules carefully, build approval workflows, and reconcile outputs every cycle. Pricing and supplier reputation matter, but—based on industry experience—governance, test coverage, and operational clarity are what ultimately determine whether payroll runs remain accurate and dependable over time.
In the long run, payroll efficiency is achieved by reducing uncertainty. Strong process design and compliant data handling reduce surprises, shorten correction cycles, and increase confidence across HR, finance, and compliance stakeholders. When payroll becomes predictable, teams spend less time troubleshooting and more time supporting employees and improving operational outcomes.
As you move forward, the most practical way to keep momentum is to anchor your procurement decisions in evidence: evidence of scenario testing, evidence of audit logs and approvals, evidence of reconciliation outputs, evidence of integration testing, and evidence of correction procedures. That evidence-based approach transforms a payroll platform purchase into a process improvement initiative—and it is the foundation for sustainable payroll performance.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

Smart Strategies to Slash Costs on Your Roof Replacement Endeavor
Opening Remarks: Smart budgeting doesn't mean cutting corners on quality. This guide will delve into cost-effective approaches for roof replacement that maintain high standards.
Unlocking the Secrets of Preschool: Your Ultimate Guide to Early Childhood Education Programs
The significance of early childhood education programs is paramount in shaping the foundational stages of a young child's life. These educational experiences aim to furnish children with a diverse skill set before they face the structured environment of elementary education. Such programs offer a dynamic and engaging atmosphere where children's natural curiosity leads to the broadening of their thought processes. Moreover, they focus on rectifying behavioral patterns and fostering positive principles and routines.
Enhance Your Smile: Essential Gum Care Tips After Teeth Replacement
After getting new dental implants, it's crucial to look after your gums to aid recovery, shield against infection, and enhance the durability and function of the implants. This discussion delves into the key methods and top tips for gum care that are vital to keep your gums robust and healthy after your procedure.
Unlock the Secrets to Championing Fair Pay: A Guide to Fighting for Competitive Nurse Salaries at Your Hospital
To effectively navigate the intricacies of nurse compensation in healthcare institutions, a thorough understanding goes beyond the basics. Strategic advocacy is essential, honoring nursing as a critical profession while also deeply comprehending the economic aspects of healthcare. This article lays out systematic methods to advocate for fair remuneration for nurses, aimed at closing the divide between managerial policies and the realities nurses face daily.
Protect Your Golden Nest Egg: Smart Strategies and Essential Precautions for Securing Your Gold Investments
Investing in gold requires more than just purchase; diligent protection and a strategic mindset are crucial. A secure gold investment is built on thoughtful planning, alert risk management, and the capacity to adapt to changes. We'll explore various ways to protect these investments from the diverse challenges they face.
Unlock Higher Earnings: Master the Art of Leveraging Your Nursing Expertise for a Hefty Pay Raise!
Unraveling the complexity of the payment landscape in nursing isn't for the faint-hearted, yet it's a manageable task with a strategy in place, enhancing one’s prospects for improved salary through skill and knowledge. This delicate dance of upholding patient care while seeking just rewards is a path all nurses must walk. Grasping the elaborate character of the nursing role and what propels one's income forward is crucial. Within this paper, we dissect insightful methods to maximize the impact of your nursing qualifications.
