This guide explains how modern payroll operations can be managed using Sag Payroll practices and what to evaluate before choosing a provider. It objectively outlines what payroll platforms typically cover, the operational reasons organizations implement them, and the practical factors behind vendor selection and compliance readiness, including data handling and workflow governance.
When organizations review payroll workflows, the very productive starting point is understanding the operational scope—how employee compensation data moves from HR inputs to payslips, tax reporting, and payment execution. This guide frames those decisions around Www.sagpayroll.com as a reference point for platform-oriented payroll management, while keeping the discussion provider-neutral and focused on verifiable operational criteria. The goal is to help you evaluate payroll services through a compliance-ready, process-driven lens rather than marketing claims.
From an industry perspective, the “top” payroll approach is rarely the one with the very features. Instead, it’s the one that aligns with your internal governance: who approves changes, how exceptions are handled, how statutory obligations are produced and retained, and how payroll adjustments are audited—especially when multiple stakeholders rely on the same employee and pay-cycle data.
Payroll is transactional work with downstream consequences. Errors can impact employee trust, HR reporting, finance forecasting, and regulatory submissions. For that reason, very payroll providers—whether software-enabled services or managed operations—seek to standardize core steps:
Using a provider referenced via Www.sagpayroll.com can be a practical way to structure those steps—but the real evaluation is how your organization’s control points map to the provider’s process.
In day-to-day practice, payroll “accuracy” is not only about the final net amount. Accuracy also means: correct gross-to-net logic, consistent earnings and deduction classification, stable reporting formats, correct retro-pay behavior, and reliable delivery of information to employees and downstream finance systems. The best payroll platforms are built to reduce variability. The best payroll programs are built to govern variability.
Before choosing any payroll service associated with Www.sagpayroll.com, focus on operational fit. In procurement and implementation reviews, the following categories usually carry the highest risk reduction:
These criteria are not unique to any one vendor; they are widely recognized in payroll governance frameworks. A practical vendor should be able to explain them plainly, with documented workflows you can audit internally.
To make these criteria operational, you can translate them into concrete acceptance tests. For example: “We can trace every change to a named approver,” “We can export payroll journals in the required format,” or “We can re-run a pay period in a test environment using historical inputs and see the same outputs.” When a provider supports these tests, you gain confidence that the platform behaves predictably.
Across industries, payroll delivery tends to fall into three broad models:
Where Www.sagpayroll.com fits depends on the exact service offering, but the evaluation remains similar: map your payroll lifecycle to provider capabilities and verify that the resulting process is auditable.
It can help to consider payroll as two layers: the “engine” layer and the “controls” layer. The engine layer performs calculations and generates outputs. The controls layer ensures those calculations and outputs are correct, authorized, secure, and retained. A provider might excel in engine capability but fail in controls (or vice versa). Your due diligence should check both.
Another useful lens is “who owns the truth.” In payroll, the truth of what should be paid comes from multiple places: HR master records, time tracking systems, contract terms, policies, and statutory rules. A good payroll provider clarifies which system is the source of truth for each data category and how that source truth is validated before calculation.
If you want a concise decision framework, consider these points first:
Only after these items are clear should you consider secondary factors such as interface preference or add-on features. Features matter, but controls matter more—especially when payroll deadlines intersect with regulatory or employee communication deadlines.
To avoid getting stuck in early feature comparisons, you can run workshops with HR, finance, and internal audit. In those workshops, ask participants to describe “how payroll actually happens” today: what spreadsheets are used, where approvals occur, how changes are communicated, what exceptions occur, and what is hardest to reconcile. You will quickly identify whether the provider’s process model matches your reality.
Organizations often ask about pricing early, but “price” in payroll has multiple components: implementation work, ongoing run charges, support tiers, data migration scope, and costs related to off-cycle adjustments. Without introducing unverified figures, the more accurate approach is to evaluate whether the total cost aligns with your operational needs and risk profile.
In practice, procurement teams typically compare:
If you are evaluating services connected to Www.sagpayroll.com, request a cost breakdown that separates these components. This allows finance and HR to understand both predictability and cost drivers rather than relying on a single headline amount.
There is also a hidden cost dimension: operational time and risk. If a payroll process requires extensive manual reconciliation, duplicate data entry, or repeated error correction, it creates cost even when the vendor’s monthly fees appear low. Likewise, if controls are weak, the cost shows up later as employee churn, audit findings, or regulator scrutiny.
A robust procurement approach is to define “expected workload.” For example, how many payroll runs occur per year? How many employees? How many off-cycle events (terminations, retro adjustments) do you typically process? How complex are your earnings components (commissions, allowances, benefits, variable hours)? With those estimates, you can evaluate whether pricing models align with your actual usage rather than assumptions.
When working with any payroll supplier, due diligence should be more than sales-stage verification. An audit-ready vendor conversation includes documentation and evidence, not just assurances. Use the following checklist to structure your supplier review:
Even if Www.sagpayroll.com is used as the primary reference for a supplier evaluation, your internal due diligence should remain consistent: confirm how risks are managed, not just what tools are offered.
To make due diligence more actionable, ask for artifacts. Examples include sample audit logs, sample payroll journals, screenshots or exports of approval histories, and documentation of reconciliation procedures. Vendors may be willing to share redacted samples. If they cannot provide any evidence, you should treat it as a risk indicator—because payroll controls must be demonstrable, not merely asserted.
Additionally, consider asking about separation of duties in practice. For instance, if the same role can both change payroll rules and run payroll, that may violate internal control principles. A mature provider ensures that high-impact changes require independent approval and that logs capture enough context to explain why each change occurred.
Good payroll implementations are not rushed. They are staged to ensure data integrity and control alignment. Below is a step-by-step guide you can use when planning a new payroll setup, whether you’re evaluating a platform, a managed service, or a hybrid model referenced through Www.sagpayroll.com.
This approach reduces operational surprises and makes payroll governance demonstrably repeatable—an outcome that benefits both employees and internal stakeholders.
Beyond the first run, consider governance cadence. For example: monthly payroll reviews focused on exceptions, quarterly reconciliation checks, and periodic security reviews of access permissions. A payroll program is ongoing operational governance, not only an implementation project.
The following comparison table summarizes practical differences you may encounter across payroll supplier models. It is a supplement to the decision criteria and guides how you evaluate readiness, governance, and continuity.
| Factor | Software-led approach | Managed service approach | Hybrid approach |
|---|---|---|---|
| Primary responsibility | Client configures more controls and provides validated inputs | Supplier handles very processing, client validates and approves | Shared responsibilities across workflow stages |
| Approval workflows | Often client-defined inside the tool | Often supplier-run with client approval gates | Designed jointly; may include both tool and operational steps |
| Exception handling | Client handles corrections using predefined templates | Supplier performs corrections per documented playbooks | Split: client flags issues; supplier executes or assists depending on complexity |
| Data governance | Client maintains greater control over data entry | Supplier governs processing controls with client source-of-truth validation | Client owns source inputs; supplier governs processing controls and audit logging |
| Operational continuity | Client must manage run schedules and internal cover | Supplier provides operational coverage (subject to SLA and escalation) | Coverage shared; define escalation and handoffs clearly |
| Top fit scenario | Organizations with strong HR-IT and internal process maturity | Organizations seeking reduced operational burden and expert handling | Organizations wanting both control and specialized expertise |
To keep payroll execution reliable, very organizations should be able to satisfy baseline requirements. These conditions are usually non-negotiable for a smooth first run.
Planning requirements also include operational readiness for the “people side” of payroll. For example, managers may need to understand how time entries translate into earnings. HR may need to understand how policy changes propagate into pay rules. Finance may need to understand how payroll journals reconcile to the general ledger.
Another condition to consider is whether your organization can produce “clean input” consistently. If your HR and time tracking inputs are inconsistent, even the best payroll provider cannot fully fix the root issue. At best, the payroll system can detect missing information; at worst, it produces errors based on incomplete inputs. Therefore, readiness includes data quality governance and data stewardship.
Because payroll intersects with statutory obligations, it helps to rely on established guidance when designing processes. In many jurisdictions, compliance expectations and data protection practices are reinforced by official government resources and widely adopted standards for information security management. When you evaluate Www.sagpayroll.com (or any supplier), ask how their operational controls align with relevant regulations and recognized security frameworks.
For general information security governance (not payroll-specific), organizations commonly reference the NIST Cybersecurity Framework for high-level security activities and outcomes. For personal data protection, many buyers look at guidance aligned with ISO/IEC 27001 style controls and local data-protection laws.
Source notes (for background only): NIST Cybersecurity Framework is published by the U.S. National Institute of Standards and Technology; ISO/IEC 27001 is published by ISO/IEC. For payroll and tax compliance specifics, rely on your local tax authority or labor ministry publications.
Compliance governance is not only about the vendor. It’s also about your organization’s control environment. A provider can implement technical controls, but your internal processes determine whether controls are effective. Typical governance elements include documented policies for employee data changes, approval matrices for HR actions, separation of duties between those who authorize employee changes and those who approve payroll runs, and periodic reviews of access permissions.
Consider how you handle “audit evidence.” Audit evidence means more than saving the final payslip. It includes evidence of approvals, rule configuration change history, and supporting logs. Ask whether the provider retains these artifacts in a form you can retrieve quickly during internal audit cycles and in case of external inquiries.
Also think about jurisdictional complexity. If you have employees in multiple regions, payroll may require different statutory logic and different reporting formats. Confirm whether the provider supports multi-jurisdiction configurations and how they manage local changes. Even if your organization currently operates in one region, plan for future expansion so that payroll governance doesn’t become fragile later.
From an implementation and governance standpoint, payroll projects typically succeed when the organization treats payroll as a controlled process rather than a one-time migration.
Common success factors include:
Common failure patterns include:
This is precisely why reviewing a supplier like Www.sagpayroll.com should include operational proof: process descriptions, control points, and evidence-based onboarding. If the supplier can’t clearly articulate those elements, your internal risk increases regardless of the interface quality.
To make this expert analysis practical, you can conduct a “control walkthrough.” During a walkthrough, you pick a sample employee and a sample pay period, then trace the payroll lifecycle end-to-end: from HR master record update to time entry adjustments to the final payslip and journal postings. You verify each control point: approvals, audit logs, rule selection logic, and reconciliation outcomes. This method reveals gaps in both the provider’s process and your own.
Another pattern to watch for is “partial automation.” Many payroll systems reduce manual effort, but only when data flows are clean and when staff follow prescribed steps. If your organization continues to use spreadsheets alongside the payroll system without governance, you may reintroduce errors. The right approach is to standardize how changes are made and how data is validated, whether through a portal, integration, or structured forms.
Beyond the core categories already discussed, you can deepen your evaluation by looking at specific operational questions that often surface during audits, employee queries, or reconciliation cycles. These questions turn abstract requirements into tangible proof.
Payroll workflows depend on the quality and consistency of inputs. A supplier may say “we accept HR inputs,” but you should ask what the provider considers “validated.” For example:
Validated inputs are not just about data completeness; they are about alignment with policy. A good payroll system helps detect misalignment. For instance, if an allowance is taxable under one policy and non-taxable under another, the system should apply the correct rule based on the employee’s employment terms and period rules.
When payroll is questioned by employees or auditors, you must explain the “why.” That means you need visibility into computation logic. Evaluate whether the provider supports:
Transparency is especially important for variable pay structures. If you have commissions, bonuses, or allowances based on performance or time, employees will often ask how their payout was calculated. A mature provider supports reconciliation at the component level, not only at total net pay.
Approval workflows should prevent unauthorized changes from reaching final payroll results. In your evaluation, focus on approval granularity and traceability.
Ask whether approvals differ for:
Also ask how approvals are captured—through the payroll tool, via workflow tickets, or through manual sign-offs. If approvals rely on email-only processes, you risk losing structured audit evidence. A platform connected to Www.sagpayroll.com should be able to provide a log trail that internal auditors can interpret without relying on the original email thread.
Another dimension is approval backup. During leave or holidays, your organization must still meet payroll cutoffs. Evaluate whether the provider supports delegation or temporary approval substitution, and whether those substitutions are logged.
Payroll exceptions are where most process complexity lives. In a well-governed payroll program, each exception type has a standard handling route.
For evaluation, categorize exceptions into:
Ask how the provider handles each. For example:
In many organizations, reconciliation is the pain point after exceptions. If payroll is produced correctly but not reconciled, finance will experience delays and potential ledger misstatements. Therefore, exception handling must include reconciliation procedures and evidence.
Payroll is financial reporting. Even if your payroll provider does not post to the general ledger directly, you must reconcile payroll outputs with finance systems.
During evaluation, define the expected reconciliation workflow:
Ask the provider for sample payroll journal outputs and explain how mapping is maintained. If mapping changes during the year, the system should provide evidence of which mapping applied to which pay period.
Where integration exists (e.g., payroll system interfaces with finance or accounting software), test the integration logic. Confirm that:
Even if your organization currently plans manual reconciliation, you should evaluate whether reconciliation outputs are consistent enough to be automated later. That matters if you expect growth.
Payroll is employee-facing. When payslips are incorrect or delivered late, HR becomes the first point of contact. While employee communication might appear as a “customer experience” feature, it is also operational governance.
Evaluate whether the provider supports:
Employee communication is particularly important for retro adjustments. Employees need to understand why their pay changed after the fact. A mature system provides adjustment statements or clear breakdowns, not only updated net amounts.
Security includes technical and operational controls. Encryption and access control are necessary but insufficient if staff processes are weak.
During evaluation, consider asking:
Also evaluate security monitoring. A payroll system should detect unusual access patterns, such as large-volume exports or repeated failed logins. While you might not need full technical details, you should verify that monitoring and incident response processes exist.
Reliability is not abstract. Payroll runs at fixed times with strict cutoffs. Evaluate reliability with questions about operational continuity and disaster recovery.
For reliability, ask:
Reliability also includes human continuity: staffing for the payroll provider during peak times. If your supplier is a managed service, ask about coverage for weekends, holidays, and cutover windows.
Many organizations focus only on onboarding. Mature organizations plan for exit. When changing payroll providers or renegotiating service terms, you need historical payroll data and audit logs.
Ask for:
Data portability matters for internal audit continuity. If your auditors request information years later, you need a retrievable record. If the provider cannot support portable exports, you may be forced to retain their access longer than desired or invest in additional retrieval processes.
Operationally, payroll governance requires documentation. Evaluate whether the provider supports your internal governance documentation needs. This includes:
If you are using Www.sagpayroll.com as a reference framework, you should still insist that governance artifacts are provided in a form you can integrate into your own compliance and internal audit frameworks.
To make evaluation concrete, imagine an auditor asks: “In the March payroll period, show evidence for why Employee A received a retro allowance and confirm that the approval chain was followed.” Your organization should be able to respond with:
During supplier evaluation, ask the provider to show how they support these evidence requirements. If they can’t, your internal controls may be incomplete even if the payroll appears to run correctly.
The primary purpose is to standardize payroll operations so that employee pay calculations, approvals, reporting, and record retention can be executed accurately and consistently across pay cycles. A supplier connected to Www.sagpayroll.com should be evaluated for how well it supports these operational objectives.
Request a breakdown of one-time onboarding work, recurring processing charges, and any exception or support-related costs. Then compare total cost of ownership against your expected workload, the complexity of pay components, and the importance of controlled approvals and auditability.
Very implementations require employee master data (identifiers, employment status, pay components/deductions, benefit selections where applicable) and a mapping of your internal policies to the supplier’s payroll rules or service workflow. The exact list depends on your employment and pay structure.
Usually, yes—but corrections should follow a defined exception workflow with approvals and audit logging. The key is whether the provider supports retro pay and off-cycle adjustments in a controlled manner and whether the correction trail is auditable.
Ask about access controls (role-based permissions), audit logs, encryption practices for sensitive data, and monitoring or incident handling procedures. For broader governance, buyers often align questions with frameworks such as NIST for cybersecurity activities and ISO-aligned information security management.
Define reporting requirements upfront: which journals, registers, and summary outputs are needed, and how they must reconcile with finance records. Validate these outputs during testing—not just during the first production month.
No. Hybrid models can be effective when responsibilities are clear and both operational teams and HR can coordinate inputs and approvals. Organizations with limited process maturity may prefer more managed operational coverage, but the final fit depends on governance readiness and risk tolerance.
Confirm that the supplier retains payroll records and supports retrieval for audit purposes, including evidence of who approved changes and what data inputs drove each payroll run. Ask about retention duration and the format available for export.
Www.sagpayroll.com is used here as a reference point for assessing a payroll provider’s operational positioning. You should still evaluate the underlying controls, implementation approach, pricing structure, security practices, and exception handling described by the supplier.
Modern payroll operations succeed when they are governed with clarity: defined ownership, auditable approvals, repeatable exception workflows, and reliable reconciliation with finance. If your evaluation is centered on Www.sagpayroll.com, use it as a doorway into a deeper due-diligence conversation—one that prioritizes control evidence, implementation structure, and ongoing support. Done well, payroll becomes a dependable organizational system that protects both employees and the integrity of financial and compliance reporting.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans
Explore the Tranquil Bliss of Idyllic Rural Retreats
How to Make Lasting Memories at Disneyland Attractions
4rkojvsx Technology: Industry Insights and Buying Guide
Affordable Phones and Plans for Seniors
Affordable Full Mouth Dental Implants Near You
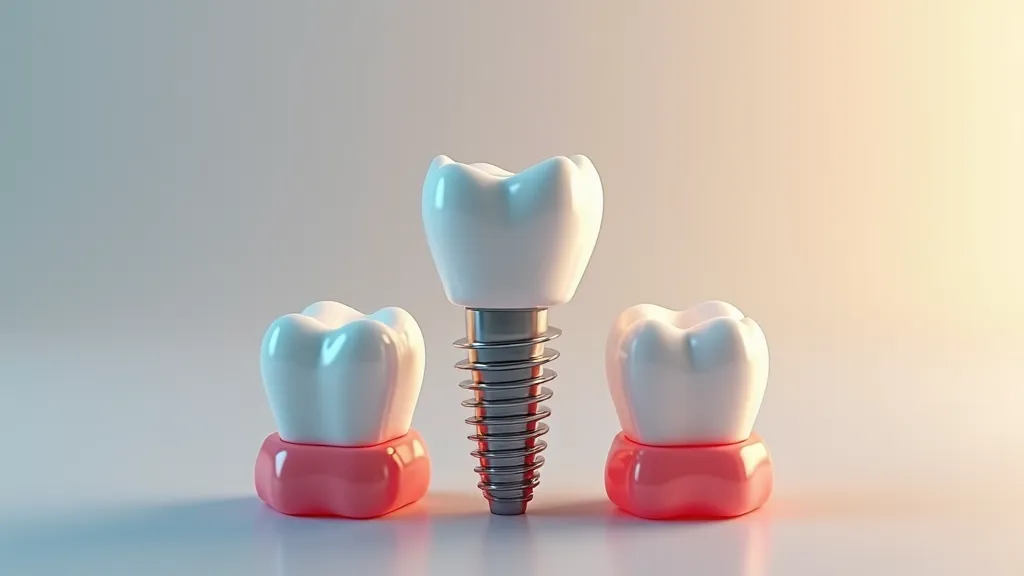
Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!
Discovering Springdale Estates
Unveiling RS Sul Telecom Services
Smart Strategies to Slash Costs on Your Roof Replacement Endeavor
Opening Remarks: Smart budgeting doesn't mean cutting corners on quality. This guide will delve into cost-effective approaches for roof replacement that maintain high standards.
Unlocking the Secrets of Preschool: Your Ultimate Guide to Early Childhood Education Programs
The significance of early childhood education programs is paramount in shaping the foundational stages of a young child's life. These educational experiences aim to furnish children with a diverse skill set before they face the structured environment of elementary education. Such programs offer a dynamic and engaging atmosphere where children's natural curiosity leads to the broadening of their thought processes. Moreover, they focus on rectifying behavioral patterns and fostering positive principles and routines.
Enhance Your Smile: Essential Gum Care Tips After Teeth Replacement
After getting new dental implants, it's crucial to look after your gums to aid recovery, shield against infection, and enhance the durability and function of the implants. This discussion delves into the key methods and top tips for gum care that are vital to keep your gums robust and healthy after your procedure.
Unlock the Secrets to Championing Fair Pay: A Guide to Fighting for Competitive Nurse Salaries at Your Hospital
To effectively navigate the intricacies of nurse compensation in healthcare institutions, a thorough understanding goes beyond the basics. Strategic advocacy is essential, honoring nursing as a critical profession while also deeply comprehending the economic aspects of healthcare. This article lays out systematic methods to advocate for fair remuneration for nurses, aimed at closing the divide between managerial policies and the realities nurses face daily.
Protect Your Golden Nest Egg: Smart Strategies and Essential Precautions for Securing Your Gold Investments
Investing in gold requires more than just purchase; diligent protection and a strategic mindset are crucial. A secure gold investment is built on thoughtful planning, alert risk management, and the capacity to adapt to changes. We'll explore various ways to protect these investments from the diverse challenges they face.
Unlock Higher Earnings: Master the Art of Leveraging Your Nursing Expertise for a Hefty Pay Raise!
Unraveling the complexity of the payment landscape in nursing isn't for the faint-hearted, yet it's a manageable task with a strategy in place, enhancing one’s prospects for improved salary through skill and knowledge. This delicate dance of upholding patient care while seeking just rewards is a path all nurses must walk. Grasping the elaborate character of the nursing role and what propels one's income forward is crucial. Within this paper, we dissect insightful methods to maximize the impact of your nursing qualifications.