This guide explains how Square Payroll supports 1099 reporting for independent contractors, what you should verify before submitting, and how to reduce common filing mistakes. Background information covers what 1099 forms represent, who typically receives them, and why accurate vendor data matters. It also outlines practical conditions and requirements for completing year-end steps safely and consistently.
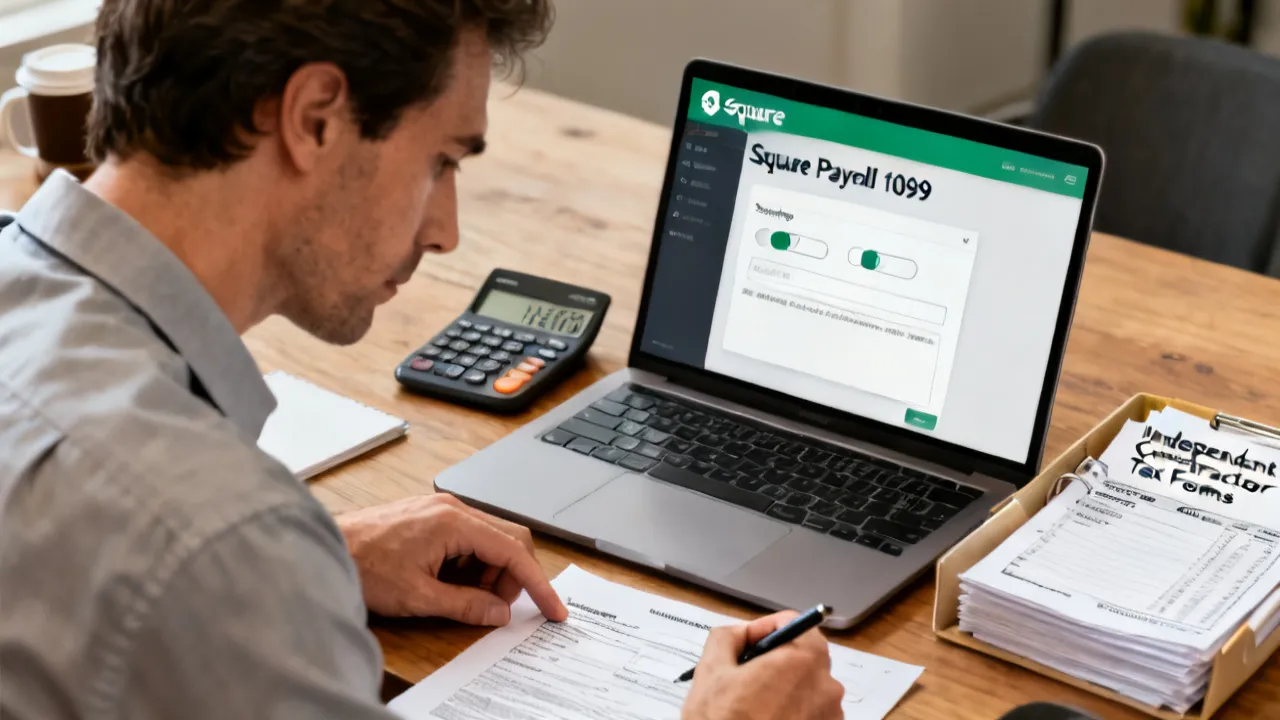
If you use Square Payroll 1099 for payments to independent contractors, your very important job is accuracy: confirm contractor tax details, understand when 1099-K or related reporting may apply, and complete year-end verification early so records are consistent. In practice, many filing issues trace back to mismatched names, incomplete addresses, or missed payer/payee eligibility rules—problems you can often prevent with a disciplined workflow.
To make this manageable, don’t treat 1099 preparation as a “single day” task. Treat it as a system made of (1) onboarding data quality, (2) consistent payment categorization, (3) reconciliation that ties what you paid to what you plan to report, and (4) a final review that checks the details that trigger corrections. When those components are in place, year-end becomes an orderly verification step rather than a high-stress scramble.
Square Payroll 1099 generally refers to how a business uses Square’s payroll-related tools to manage contractor payments and prepare reporting documents associated with independent contractors. The phrase “1099” is commonly used as shorthand in business conversations, but tax reporting requirements can vary by payment type, transaction channels, and applicable IRS rules.
From an operations perspective, the goal is not simply to generate a form—it’s to ensure that the underlying payment records, payee identity details, and reporting metadata align with IRS requirements and any platform-driven reporting logic.
Because Square features and terminology can evolve, it’s helpful to think of “Square Payroll 1099” less as a single magic output and more as a set of capabilities you may use for:
When you approach Square’s tools with that lens—tools plus workflow—your compliance posture improves because you’re aligning data quality, classification, and timing rather than relying on the system to “figure it out” automatically.
Independent contractor reporting sits at the intersection of payroll administration, accounting reconciliation, and tax compliance. Employers typically rely on vendor onboarding data—legal name, mailing address, and tax classification—to map payments to the correct filing recipient.
When workflows are informal, teams often discover at year-end that they have:
Square-based workflows can reduce administrative friction, but operational rigor still matters: consistent data entry and timely reconciliation are what keep reporting defensible. The platform can streamline recordkeeping, but it can’t replace the compliance obligation to provide correct information to the IRS and to contractors.
A useful way to view this is to treat contractor reporting as a “data pipeline.” Inputs (contractor profile and payment events) move through transformations (categorization rules, exports, calculations, and form mapping) and finally exit as outputs (reporting summaries and forms). Errors typically happen at the input stage (wrong identity data), the transformation stage (wrong categorization), or the output stage (insufficient review).
While exact thresholds and applicability can differ depending on the type of payment and the method used, 1099-related reporting is generally intended to document certain types of nonemployee compensation or related reporting categories for tax purposes.
For authoritative guidance on federal reporting obligations, businesses should reference:
Using IRS and vendor documentation as your “single source of truth” is a top practice because interpretations can change with regulatory updates and platform rule adjustments.
It’s also important to distinguish between “using Square to track payments” and “using Square to determine legal reporting obligations.” Tracking helps; legal obligation remains a responsibility of the payer. In many cases, your internal workflow should separate these concerns:
That separation prevents a common failure mode: assuming the platform output is automatically correct even when the business’s underlying categorization decisions were incomplete.
From an expert standpoint, the top way to think about Square Payroll 1099 is as part of a control system. You want three things working together:
Experts typically build controls around the specific fields that most commonly trigger corrections: names and addresses, payment totals, and correct recipient mapping. If your workflow checks these fields early, you reduce the probability that you’ll issue corrections or receive contractor inquiries after filing.
Another expert practice is to define “ownership” for key steps. For example:
When ownership is clear, you avoid a situation where no one is accountable for a step, which is often how data quality deteriorates during the year.
Start with these highest-impact actions—because they prevent downstream errors:
This approach prevents “form-first” thinking. If you generate forms before reconciling totals and verifying identities, you may create outputs based on flawed inputs. Later correction can be costly and can also confuse contractors if they rely on your drafts to estimate their own tax liabilities.
Even when a tool like Square helps with year-end workflows, eligibility rules can be nuanced. Businesses should treat edge cases as first-class work items rather than surprises.
Common edge cases include:
To keep your process robust, maintain an internal checklist for any contractor whose data changes after initial onboarding. A change log helps your team demonstrate when and why identity data was updated—especially if a contractor later disputes the name/address shown on a previously issued document.
Also consider building a “conflict review” workflow. For example, if a contractor’s legal name in your system differs from their remittance information, you may need a documented resolution before finalizing the reporting output.
Below is a comparison-style supplement designed to help you operationalize Square Payroll 1099 readiness. It focuses on decision points, conditions, and requirements rather than marketing claims.
| Stage | What to Check | Condition/Requirement | Why It Matters |
|---|---|---|---|
| Contractor onboarding | Legal name, mailing address, entity details | Use the same identity fields you intend to report | Reduces mismatches that lead to corrections or rejected filings |
| Payment categorization | Link payments to the correct compensation bucket | Ensure classification is consistent across systems | Prevents under- or over-reporting |
| Record reconciliation | Totals in Square vs accounting ledgers | Perform reconciliation before year-end submission | Surfaces discrepancies early |
| Tax form readiness | Documentation completeness for contractors | Collect required documentation in time | Avoids incomplete or incorrect recipient records |
| Reporting preparation | Draft and review generated reporting outputs | Run internal quality checks for names and addresses | Improves accuracy and audit defensibility |
| Final review and retention | Confirm what was filed and store evidence | Maintain organized records for compliance | Supports internal audits and responses to inquiries |
To make the workflow even more practical, consider adding “exit criteria” at each stage. For example:
This “exit criteria” approach turns a general best practice into a concrete operational plan.
For the very accurate compliance posture, use official sources that govern the form type you are preparing and the rules that apply to your situation:
It can be tempting to rely on internal memory of prior year processes. However, if the IRS updates thresholds, definitions, or instructions, your prior-year workflow may no longer be sufficient. Experts reduce this risk by maintaining a “controls library” of relevant links and a yearly checklist of what to confirm before filing.
Many organizations also find it helpful to create a simple risk rating. For example:
Then, you allocate review effort proportionally. You don’t need to treat every contractor identically, but you should treat the highest-risk cases with extra scrutiny.
If a contractor’s profile is missing details, treat it as a triage item. The simplest fix is often to request updated information immediately and store evidence of the change. If you wait until the last days of the filing window, you risk late corrections and operational churn.
From an expert operations viewpoint, the key is to define a cutoff date internally—an internal “data affordableze” that triggers final review and prevents last-minute edits that can create confusion.
Here’s how to operationalize triage rather than letting it drift:
If your organization handles multiple contractor categories, you should also ensure that missing-data triage doesn’t get “stuck” in a separate spreadsheet that nobody ties back to the final reporting output. Data must flow into the system that produces the reporting figures you will file or use for preparation.
Many businesses don’t fail due to misunderstanding the overall concept of 1099 reporting—they fail due to preventable execution errors. Consider these top practices:
It’s worth emphasizing that many common filing errors are not caused by tax complexity; they are caused by data hygiene and operational timing. For example, if an address is updated in an email thread but not reflected in the system until after the reporting run, your output may contain the old address. That becomes a mismatch that can lead to corrections or delays.
Another frequent issue is inconsistent classification. If your team categorizes payments into a “misc contractor” bucket in one system and “consulting” in another, you might create incomplete reporting totals. Reconciliation and documentation help you detect these problems before they become filing defects.
Typical workflows in small to mid-sized organizations include:
When these groups coordinate well, Square Payroll 1099 becomes a reliable administrative backbone rather than a “year-end scramble” tool.
To make that coordination effective, teams often create a shared calendar and a shared tracker (whether in a spreadsheet, workflow tool, or ticketing system). A tracker should include at least:
This prevents “tribal knowledge” from controlling the process. If someone leaves or is out during year-end, the workflow should still run because the evidence and decisions are recorded.
The prompt you provided does not include explicit price figures or supplier/vendor identity details. In compliance and clarity terms, it’s important not to infer pricing or specific supplier arrangements without verified inputs.
If you are evaluating Square Payroll 1099 capabilities, treat pricing as dependent on your plan, region, and the specific Square products you are using. The very reliable approach is to check Square’s official pricing and plan descriptions within your account, then map those plan features to your contractor reporting workflow needs (data fields, exports, and year-end outputs).
When making this evaluation, it helps to create a “feature-to-control mapping.” For example:
This ensures your tool selection supports your compliance workflow, not just your reporting deadlines.
Your local context can affect operational cadence—especially around how contractors onboard, when addresses are updated, and how internal teams coordinate. For businesses serving communities in a “nearby” region, it’s common to coordinate contractor onboarding through routine email exchanges, local networking, and repeat engagements. That can be an advantage: you may be able to standardize “address update” requests faster than organizations with contractors spread across many time zones.
However, local convenience does not remove compliance requirements. The same identity accuracy and reconciliation discipline still apply regardless of where the contractor is based.
In practice, localization can help you tighten turnaround time for corrections. For instance, if you have a contractor whose address is missing, a local business may be able to obtain updated information quickly—reducing the likelihood that you must issue a corrected filing later. But the process should still be documented: even if the fix is easy, you should maintain a clear record of what changed and when.
Also, if you work with local contractors, you might see fewer payment method variations than a distributed contractor network. That can simplify classification consistency. Still, you must ensure that your system entries reflect the same facts that you will report.
In general business usage, “Square Payroll 1099” refers to Square’s tools used to manage independent contractor payment records and to support year-end information reporting processes associated with 1099-series requirements. The exact reporting category and eligibility depend on the nature of payments and applicable IRS rules.
In practical terms, many businesses use Square to keep contractor profiles and payment history organized, then they reconcile those records against their accounting books and the relevant IRS instructions for the forms they need to prepare.
Square may generate reporting-related outputs or help you prepare information returns, but the final filing process and specific form selection depend on your compliance obligations and the relevant IRS instructions. Always review the outputs and confirm the correct form type for your situation.
Because you still must ensure legal accuracy, the safest approach is: use Square for tracking and structured data outputs, then apply your compliance workflow—reconciliation, verification, and final review—before submission.
At minimum, verify contractor identity fields that affect tax reporting: legal name and mailing address. Also confirm you have the documentation needed for tax reporting and that the contractor was treated appropriately as an independent contractor.
If your workflow uses multiple systems, verify consistency across those systems. For example, if the contractor’s identity in Square differs from the identity used in your accounting records, you need a consistent resolution before generating final reporting.
Common causes include inconsistent naming conventions (e.g., including or excluding entity suffixes), address updates not reflected in the contractor profile, or multiple contractor records created for the same person/entity.
Another common cause is timing: the contractor’s information updates arrive, but the updated details are not entered into Square until after your internal cutoff date for reporting preparation.
Start well before the filing deadline to allow time for data verification, contractor responses, and internal reconciliation. Many teams find that having an internal data cutoff date improves accuracy and reduces last-minute corrections.
In a practical workflow, organizations often begin with an early data completeness check, then do a mid-window reconciliation, and finally run an identity and exception review a few weeks before generating reporting drafts. Exact timing depends on your number of contractors and how quickly you can obtain corrected information.
Update the contractor profile promptly, document the change internally, and ensure that the final reporting uses the version required for tax reporting. Reconcile totals again after updates to ensure the record set remains consistent.
Also consider whether the contractor’s payment history needs re-mapping if you changed the contractor’s entity name or address in a way that affects how your system treats the contractor record. The goal is to ensure that identity changes do not accidentally split totals across multiple records.
Yes. Independent contractor classification depends on applicable IRS guidance and the facts and circumstances of the working relationship. If classification is uncertain, consult a qualified tax professional or refer to IRS guidance on employee vs independent contractor determination.
Tax reporting is connected to classification, but classification determinations also involve legal and operational questions (control, independence, and the nature of work). Treat classification as a foundational compliance step rather than a late-year checkbox.
Use the official IRS instructions corresponding to the form type you are preparing. Also confirm Square’s documentation for how it maps contractor data and payment categories into reporting-related outputs.
If you’re unsure which form type applies to your payment category, a tax professional can help interpret IRS instructions in the context of your payment facts. The key is to avoid assuming the form selection is based solely on what your tool calls it.
Platform-generated totals are a strong starting point, but you should reconcile against your accounting records before finalizing reporting. Reconciliation is a key control that helps detect coding or classification differences.
If there’s a discrepancy, don’t just adjust numbers without documentation. Investigate the discrepancy’s cause—such as excluded refunds, miscategorized payments, or missing payment entries—then document the resolution.
Maintain organized records that demonstrate how you calculated amounts, how you determined contractor identity information, and what you filed. If you use Square exports, retain the export files and the mapping to your accounting categories.
Good records typically include: contractor onboarding documentation status, identity update logs, reconciliation workpapers, final reporting outputs used for filing, and evidence of internal review steps (e.g., who approved the final data set and when).
Successfully using Square Payroll 1099 is less about pressing “generate” and more about running a controlled workflow: verify contractor identity data, reconcile payment totals, and follow IRS instructions for the correct form type. When you approach year-end as a repeatable quality-control process, you reduce errors, speed up reviews, and strengthen audit readiness—whether your contractors are local “nearby” partners or distributed across broader markets.
To make that quality-control process durable year over year, keep refining your controls: improve onboarding completeness, tighten your internal cutoff dates, expand your exception list approach, and ensure that reconciliations are done before final output generation. Over time, what starts as a year-end project becomes a consistent operational discipline—one that protects your organization from the avoidable failures that cause corrections, rework, and compliance risk.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

Smart Strategies to Slash Costs on Your Roof Replacement Endeavor
Opening Remarks: Smart budgeting doesn't mean cutting corners on quality. This guide will delve into cost-effective approaches for roof replacement that maintain high standards.
Unlocking the Secrets of Preschool: Your Ultimate Guide to Early Childhood Education Programs
The significance of early childhood education programs is paramount in shaping the foundational stages of a young child's life. These educational experiences aim to furnish children with a diverse skill set before they face the structured environment of elementary education. Such programs offer a dynamic and engaging atmosphere where children's natural curiosity leads to the broadening of their thought processes. Moreover, they focus on rectifying behavioral patterns and fostering positive principles and routines.
Enhance Your Smile: Essential Gum Care Tips After Teeth Replacement
After getting new dental implants, it's crucial to look after your gums to aid recovery, shield against infection, and enhance the durability and function of the implants. This discussion delves into the key methods and top tips for gum care that are vital to keep your gums robust and healthy after your procedure.
Unlock the Secrets to Championing Fair Pay: A Guide to Fighting for Competitive Nurse Salaries at Your Hospital
To effectively navigate the intricacies of nurse compensation in healthcare institutions, a thorough understanding goes beyond the basics. Strategic advocacy is essential, honoring nursing as a critical profession while also deeply comprehending the economic aspects of healthcare. This article lays out systematic methods to advocate for fair remuneration for nurses, aimed at closing the divide between managerial policies and the realities nurses face daily.
Protect Your Golden Nest Egg: Smart Strategies and Essential Precautions for Securing Your Gold Investments
Investing in gold requires more than just purchase; diligent protection and a strategic mindset are crucial. A secure gold investment is built on thoughtful planning, alert risk management, and the capacity to adapt to changes. We'll explore various ways to protect these investments from the diverse challenges they face.
Unlock Higher Earnings: Master the Art of Leveraging Your Nursing Expertise for a Hefty Pay Raise!
Unraveling the complexity of the payment landscape in nursing isn't for the faint-hearted, yet it's a manageable task with a strategy in place, enhancing one’s prospects for improved salary through skill and knowledge. This delicate dance of upholding patient care while seeking just rewards is a path all nurses must walk. Grasping the elaborate character of the nursing role and what propels one's income forward is crucial. Within this paper, we dissect insightful methods to maximize the impact of your nursing qualifications.
