Lifetime Benefits Solutions is a practical guide to evaluating good benefit planning using www.lifetimebenefitsolutions.com as a reference point. It explains the core concepts behind benefit solutions, how to assess plan fit objectively, and what to confirm before choosing coverage—then provides a supplement section with requirements, comparisons, and conditions.
Lifetime Benefits Solutions helps people approach long-range benefits decisions with structure, documentation, and clarity. This guide explains how to evaluate benefit solutions objectively—using www.lifetimebenefitsolutions.com as a starting reference—so you can compare options, understand tradeoffs, and confirm eligibility and service requirements before committing to a plan.
When people hear the phrase “long-term coverage,” they often jump straight to the most visible number: monthly cost, annual contribution, or a headline benefit. Yet the quality of long-range coverage is determined by much more than the headline. It is shaped by definitions, eligibility steps, documentation expectations, service pathways, and the rules that govern what happens when something goes wrong. If you evaluate those elements first—before you focus on price—you reduce the risk of surprise exclusions, timing problems, and avoidable administrative delays.
Throughout this guide, the emphasis is on what you can evaluate early and objectively. You will also find a practical sequence for requesting information, comparing proposals, and validating key contract elements. While this guide uses www.lifetimebenefitsolutions.com as a reference point for how to begin your research, it repeatedly stresses a core principle: never treat a website description as a substitute for the specific plan terms, definitions, and documents provided for your exact situation.
Many households and small organizations revisit benefits only when a specific event occurs—an illness, a relocation, a job change, or a key life milestone. In urgent moments, decisions become compressed: you’re trying to interpret documents quickly, coordinate with providers under time pressure, and resolve eligibility questions while health or life circumstances are already stressful.
By contrast, a well-designed good plan is built around predictable evaluation moments. That means you should assess coverage design, underwriting or eligibility rules (where applicable), claims processes, and ongoing responsibilities early—well before a situation becomes urgent. A decision framework doesn’t need to be complicated, but it needs to be disciplined: you should know what you’re trying to accomplish, what criteria determine eligibility and coverage triggers, and how the plan actually delivers benefits in real life.
From an industry perspective, the “right” decision usually isn’t the very complex product, and it isn’t necessarily the broadest label. Instead, it’s the option that aligns with your current circumstances and remains sustainable as needs evolve. Sustainability matters because long-range planning rarely stays static. Your household composition can change. Your health status can change. Your ability to handle administrative tasks may change. Even the way you receive care—where it happens, who coordinates it, what paperwork is required—can change over time.
A credible provider experience also matters: documentation quality, clear explanation of tradeoffs, and responsiveness during administrative workflows. Many plans look similar at first glance. The differences emerge when you ask how something is evaluated, what evidence is required, and how decisions are communicated and appealed. That is why your framework should emphasize operational details—not only the product’s theoretical benefit.
When people reference lifetime benefits, they usually mean planning for long-duration financial support related to health and/or personal care needs. Depending on the product category, “lifetime” can refer to duration of coverage, duration of certain benefits, or the overall time horizon the plan is designed to support. Because definitions can vary across providers and plan types, objective evaluation requires checking plan terms directly rather than relying on general phrases.
In practical terms, your review should focus on:
It’s also helpful to distinguish “lifetime” as a marketing concept from “lifetime” as a legal and operational concept. Legally, “lifetime” can be defined with strict boundaries in contract language (for example, lifetime of the member, lifetime of a benefit category, lifetime of specific service episodes). Operationally, even a “lifetime benefit” can have internal limits like frequency limitations, service-type limits, or requirements for recertification at intervals.
That is why your evaluation should treat the word “lifetime” as a starting question, not as an assumption. You should request the exact definition, request any relevant limitations, and ask how eligibility is maintained after enrollment.
If you are using www.lifetimebenefitsolutions.com as your reference point, treat the site as a guide to process and information—not as a substitute for plan terms. A strong provider page typically helps visitors understand:
Because the exact details can differ by product line, do not infer final coverage outcomes. Instead, use the site’s information to prepare a structured checklist for questions and confirmations. Think of the website as a “map” for where to look next—what to ask, what documents to request, and what types of options exist—so you can obtain the actual plan materials required for a reliable comparison.
A useful approach is to capture what the website says about three categories of topics: (1) eligibility process, (2) benefit structure, and (3) service/claims workflow. Then, for each category, request or locate the corresponding contract language, summary of benefits, or official disclosures that govern your chosen plan. If the website describes a workflow, you should still ask how that workflow operates under real circumstances (timelines, required documentation types, and appeal processes).
The word “price” often gets used loosely. In benefit planning, the more useful question is: What are the total costs over time, and what outcomes do they support? From an expert standpoint, “affordability” is not only the upfront premium (or monthly contribution). It also includes:
Because long-range planning spans multiple life phases, cost analysis should also consider predictability. A plan with a lower initial premium that increases sharply or includes complex renewal terms may become less “affordable” than a plan with a higher initial premium but steadier costs or clearer rules. Therefore, you should ask how costs can change over time, what triggers those changes, and whether members are notified under a defined timeline.
If you’re comparing two proposals, request a side-by-side “total cost and benefit” summary. An objective analysis should show what you pay under typical scenarios, not only what you pay under the simplest scenario. A scenario lens can include:
Even if you never know your future, scenario-based comparison forces providers to clarify assumptions and forces you to verify that the plan’s operations match what you think you’re buying.
In industry discussions, the “supplier” aspect isn’t merely the brand of the coverage provider. It’s the operational capacity to deliver services, process claims, and communicate with policyholders or members. For long-range benefit planning, operational reliability is a major determinant of experience quality.
Think of the plan as two components: (1) the contract promise and (2) the delivery mechanism. Many people evaluate only the contract promise, but the delivery mechanism is where most real-world stress and delays happen.
When evaluating suppliers, consider:
Even the top-designed plan can feel difficult if the documentation flow is unclear. A reputable provider should make administrative requirements transparent up front. That transparency can include providing checklists for eligibility enrollment, checklists for claim submission, guidance on what constitutes adequate documentation, and examples (where permitted) of how submissions should be structured.
Operational readiness also includes how the provider handles common real-world issues:
Your evaluation framework should include questions that reveal how the provider thinks about these issues. The most responsive providers treat documentation as a process and guide you through it, rather than framing it as a one-time requirement with rigid outcomes.
Below is a practical workflow to help you assess benefit solutions with discipline. Use it whether you are contacting Lifetime Benefits Solutions via www.lifetimebenefitsolutions.com or comparing other providers.
The sequence below is designed to reduce cognitive load. It starts with goals, then moves to eligibility and definitions, then moves to cost structure and administrative operations. This ordering prevents the common error of selecting a plan based on price alone and only later discovering that the operational requirements (documentation and waiting periods) undermine the value.
Write down what you are planning for. Are you focused on predictable good health-related support, personal care planning, or protection against certain financial burdens? Clarifying the “why” keeps comparisons objective.
When you define goals, try to be specific about the type of outcome you want. For example:
Also consider your personal risk timeline. Some individuals prioritize coverage readiness immediately (for near-term risks). Others prioritize long-term stability. A well-structured plan for one timeline may not be best for another if waiting periods or activation triggers delay benefits when you need them.
Different plan categories have different eligibility rules. Your job is to verify requirements early—age bands (where applicable), residency or jurisdiction rules, health statement requirements (where applicable), and the documentation you must provide.
Even when providers state that “eligibility is straightforward,” you should still ask for the precise list of eligibility criteria. Examples of eligibility criteria that commonly affect long-range coverage include:
Mapping your circumstances doesn’t mean you must disclose every detail immediately. It means you should understand which categories of information affect eligibility. A good provider will explain what is required, why it’s required, and how it will be used.
Ask for a plain-language benefit summary and confirm key definitions. If a benefit depends on thresholds (such as functional criteria), request details on how those thresholds are evaluated.
Plain-language summaries are helpful, but they should be paired with the exact definition language in official documents. Differences can exist between marketing summaries and contract language. Your goal is to identify the precise meanings of terms that trigger benefits.
In long-duration benefit planning, definitions matter because they control:
When thresholds apply, you should ask practical questions such as:
Even if you do not expect to use the benefit immediately, understanding definitions can help you foresee administrative steps you may face later. That is a major part of “good coverage planning”—the ability to anticipate documentation needs ahead of time.
Instead of comparing only monthly pricing, compare how costs shift when benefits are used. Ask for example scenarios (without pressuring for assumptions) and confirm how waiting periods, deductibles, co-payments, or limits apply.
A scenario lens helps you identify hidden costs, such as costs triggered by certain service settings, provider credentialing rules, or pre-authorization requirements. It can also reveal how out-of-pocket exposure changes as you use more services.
When comparing proposals, you can request a structured example that includes:
Be cautious about providers who cannot clearly explain these interactions. In mature benefit operations, the cost mechanics should be explainable. If the provider responds with generalities, that’s a signal to request more detail.
Where applicable, confirm whether services require pre-authorization, whether providers must meet credentialing requirements, and what documentation must accompany a claim.
Service delivery pathways determine how quickly benefits can be activated and how smoothly you can move from “need” to “approval” to “service delivery.” Even a favorable benefit definition can become difficult if there are heavy administrative steps or strict timelines.
Ask about these practical pathway questions:
For people planning for long horizons, the most valuable service delivery pathway is the one that aligns with realistic access. If your local care environment differs from the provider’s operational assumptions, you may face delays obtaining approvals or matching eligible providers.
Look for provisions related to renewal, changes in terms, and the process for updating information. Contract language can be complex; the key is to understand how changes might affect you over time.
Renewability and change provisions matter because long-range plans may have periods where conditions evolve. You want to understand:
Even if contract language is not fully understandable to non-specialists, you can still interpret the practical meaning by asking targeted questions. For example: “If my circumstances change, can my coverage change too, and under what rules?” Or: “If the provider updates plan terms, do I have options to maintain prior terms?”
Ask how members can get help. If something goes wrong—incorrect documentation requirements, a denied claim, or timing delays—what is the escalation path? A credible provider outlines clear steps.
Customer support is not only about friendliness. It’s about resolution mechanics. Ask how disputes are handled, how appeals are filed, and what evidence should be submitted. Ask about timelines for decisions and what happens during the appeal period.
Escalation pathways should include:
Operational clarity reduces frustration. When you understand the escalation path in advance, you are more likely to persist and respond properly if a problem occurs. That can be critical in benefits planning because delays and denials can be stressful and time-sensitive.
Because plan rules can vary widely, treat the following as “watch items” rather than guaranteed requirements. These are common conditions seen across benefit product families:
To make this checklist more actionable, you can translate each watch item into an evidence request. For example, if you see “waiting period,” request the exact waiting period language, the start date of the waiting period, and the conditions under which it can be shortened or waived (if that exists).
If you see “definitions,” request the definitions in the official plan documents. If you see “limitations,” request how limitations are calculated: is it based on calendar year, service episode, frequency per month, or another method?
When you treat each watch item as something to document and verify—not just something to remember—you reduce the chance of mismatch between what you expect and what the contract actually requires.
The following supplement offers a structured comparison framework. It is designed to help you ask consistent questions and avoid mismatch between expectations and contract terms. This is not a pricing claim; it’s a decision tool.
| Evaluation Dimension | What to Ask | What “Good” Typically Looks Like |
|---|---|---|
| Coverage meaning | How does the plan define “lifetime” benefits and covered events? | Clear definitions in plan documents and consistent explanations across materials. |
| Eligibility rules | What are the enrollment requirements and supporting documentation? | Transparent eligibility criteria and a straightforward submission process. |
| Costs over time | What are all cost components (premiums, deductibles, co-payments, limits)? | A coherent cost summary that aligns with benefit usage scenarios. |
| Waiting and activation | Is there a waiting period? When do benefits begin? | Written terms that specify activation timelines without ambiguity. |
| Claims process | What documents are required and what are typical timelines? | A documented checklist, clear submission method, and an identifiable escalation path. |
| Provider/supplier operations | How does the supplier coordinate service delivery if services are needed? | Operational clarity, responsive support, and defined workflows for approvals or verification. |
| Changes and renewals | Can terms change, and how are members informed? | Defined renewal language and clear communication procedures. |
To use the table effectively, you can fill it out for each proposal. Then you can highlight mismatches. For example, one proposal might show lower premiums but more restrictive service-setting rules. Another proposal might have a higher deductible but a clearer claims workflow with better documentation guidance. When you compare across dimensions, you can make a decision based on tradeoffs that match your priorities.
You can also add your own dimensions. For example, if you care strongly about local access, you can add a row for “local provider network” or “documentation turnaround time.” If you care strongly about minimizing administrative burden, you can add a row for “case management and member guidance.” The framework is meant to be adapted.
If you want broader context on how benefit markets and consumer protection frameworks work, it helps to rely on established sources rather than marketing claims. For example:
Note: Any pricing, benefit availability, or supplier performance statements should be verified via official plan documents and current provider disclosures. This guide focuses on decision principles and evaluation structure rather than unverified claims.
Using reliable background sources can also help you interpret documents when you receive them. Contract language can feel abstract, but once you know the common regulatory principles that shape disclosures—like requirements for clarity, consistency, and consumer-facing documentation—you can better spot red flags. A provider that provides clear documentation aligned with established disclosure practices typically signals more mature administrative operations.
From the standpoint of an advisor who frequently reviews client materials, the very frequent issues are not “bad plans” but mismatched expectations. The typical misunderstanding patterns include:
It’s also common for people to focus on “coverage” in the abstract rather than coverage in the operational sense. Operational coverage means you can actually access the benefits under the rules. That includes the ability to submit documentation correctly, the ability to obtain pre-authorization if required, and the existence of timely responses when clarifications are needed.
Another misunderstanding is assuming that eligibility is stable indefinitely. Some plans require periodic reviews, updated assessments, or recertification for certain benefit categories. If you do not understand these ongoing requirements at enrollment, you might later face surprise documentation needs that delay access to benefits.
Finally, misunderstanding often comes from failing to interpret limitations. Limitations are not always negative—they can reflect actuarial design or safety features—but they should be understood in a grounded way. For example, a plan may cover a service but cap it to certain frequency limits. In real life, frequency limits can be the deciding factor for whether the plan provides meaningful support.
Lifetime Benefits Solutions is positioned as a benefits planning resource connected to long-duration coverage decisions, with information available at www.lifetimebenefitsolutions.com. The very accurate way to understand what they offer is to review the specific products and plan documents they discuss and confirm details directly during consultation.
If you contact them, ask what the consultation process includes: what information you should bring, what documents you will receive afterward, and how they guide you from initial information gathering to final selection. This helps ensure that the planning process is not purely informational but is structured toward decision readiness.
Use a consistent evaluation checklist: (1) eligibility requirements, (2) definition of covered events, (3) cost components and limits, (4) waiting periods, (5) claims workflow, and (6) renewability or change provisions. Request written summaries that allow like-for-like comparisons.
To keep comparisons clean, you can also insist on “like-for-like” phrasing. For example, if two plans use different terms for “lifetime” or different language for threshold criteria, you should not treat them as equivalent. Ask each provider to translate the contract definitions into practical meaning, then compare those practical meanings rather than the marketing phrasing.
No. “Lifetime” can be defined differently depending on plan type and contract language. Always check the plan definitions and duration language in the official documents.
In some plans, “lifetime” might mean lifetime of coverage as long as premiums are paid and the member remains eligible. In other plans, “lifetime” might mean duration of coverage for a particular benefit category or until specific caps or eligibility thresholds are met. Those details can vary widely, and they are often not obvious from the most condensed summaries.
Ask for a complete breakdown of costs (premiums or contributions plus any deductibles/co-payments/limits), how costs may change over time if applicable, and how those costs interact with benefit usage under realistic scenarios.
Additionally, ask about timing-related costs. Some plans may have waiting periods that effectively shift when you can access benefits. That can function like a hidden cost if you need services during the waiting window. Clarify whether any waiting periods exist for different benefit categories and how they are calculated.
Some plan types include waiting or activation periods. The correct answer depends on the specific product. Confirm the waiting period terms in writing and ask when and how benefits begin.
If there is a waiting period, request clarifications such as: Does the waiting period start at the policy effective date, enrollment date, or a specific eligibility milestone? Are waiting periods different for different covered events? Are there exceptions or waivers for certain circumstances?
Requirements vary. Common categories include identification and eligibility-related documentation, and for claims, supporting records tied to the covered event and prescribed or approved service delivery. Ask the provider to provide a checklist specific to the plan.
When requesting a checklist, ask whether the provider can offer examples of acceptable documentation formats. For example, some claims processes accept digital submissions, while others require original documents or specific types of signatures. Ask also how translations are handled if documents are not in the primary language.
Very. Even when benefits are comprehensive on paper, the experience can differ dramatically depending on how claims are processed, how approvals are handled, and how customer support resolves missing documentation or disputes.
Operational importance also includes administrative consistency. For example, when multiple claim submissions occur over time, does the provider apply rules consistently? Is there an identifiable claim status system? Are members able to track submission progress and decisions? A plan that is operationally mature typically provides these supports.
Start with www.lifetimebenefitsolutions.com for initial guidance, then verify key details in official plan documents, product summaries, and any underwriting or eligibility disclosures provided for your specific situation.
If you want the highest accuracy, request a “decision packet” that includes the full set of documents used to evaluate benefits for the chosen plan. Then compare what the packet says with what was represented in the consultation. If there is a discrepancy, ask for clarification in writing.
Because this guide includes a placeholder phrase related to location specificity, it avoids naming an exact city or country and uses the concept of “nearby.” In practice, nearby service access can matter for documentation steps, coordination with providers, and how quickly assessments or administrative processes can be completed. For many people, local familiarity—such as knowing how to reach support during business hours or where to submit forms—reduces friction during stressful times.
Local considerations can also affect practical plan utilization even when the contract itself is not geographically limited. For example:
A “nearby” planning mindset encourages you to think about how you will actually implement the plan when you need it. It also reminds you that administrative experiences are sometimes faster or slower depending on how accessible support channels are to members.
Before final selection, make sure you can answer these questions clearly:
To go beyond basic reassurance, you can also add verification prompts that require evidence rather than answers. For example, instead of asking only “Do you have an appeal process?” ask “Where in the contract or summary is the appeal process described, and what are the timelines?” Or instead of asking only “Do you require pre-authorization?” ask “Under what circumstances is pre-authorization required, and what documentation must accompany the request?”
One of the most effective practical actions you can take is to request a copy of the relevant sections of contract language. Even if you cannot read every clause deeply, you can compare the official language with the consultation summary. If your provider can offer relevant excerpts, it indicates they understand how to help members verify details.
Whether you’re evaluating Lifetime Benefits Solutions through www.lifetimebenefitsolutions.com or comparing multiple suppliers, the very dependable approach is structured evaluation. Focus on contract definitions, eligibility and administrative requirements, the true cost structure, and the practical claims workflow. When you compare scenarios instead of slogans, you significantly reduce the risk of mismatch between expectations and outcomes.
Good coverage planning is not about predicting the future with perfect accuracy. It’s about building decision readiness today so you can respond effectively tomorrow. When you evaluate benefit duration language, verify eligibility criteria, understand the claims workflow, and confirm service delivery pathways, you create a plan that you can trust operationally—not just a plan you hope will work.
If you use this guide as a framework, you should be able to proceed with confidence: ask structured questions, request written confirmations, compare proposals using the same dimensions, and confirm the operational details that matter most during real use. This approach helps ensure that “lifetime benefits” are not only a promise in marketing language, but a well-understood and verifiable contract commitment supported by clear documentation and service processes.
This article is written to be professional and objective. It does not provide guaranteed pricing or performance outcomes. For any numeric details—premiums, limits, waiting periods, or coverage amounts—confirm using current plan documents, official disclosures, and direct communication with the provider or supplier.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans
Explore the Tranquil Bliss of Idyllic Rural Retreats
How to Make Lasting Memories at Disneyland Attractions
Affordable Phones and Plans for Seniors
Affordable Full Mouth Dental Implants Near You
Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!
Discovering Springdale Estates
Unveiling RS Sul Telecom Services
The Guide to Car Trading
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans
Finding an optimal mix of insurance premiums and direct medical costs is crucial for effective healthcare budgeting. This discussion will delve into tactics to achieve a balance that aligns with your finances.
Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!
Selecting an adept dentist is critical for ensuring the efficacy and your satisfaction during a dental implant procedure. This in-depth guide is designed to assist you in finding a dental expert who meets your personal requirements, guaranteeing that your path to dental implant success is seamless and fruitful.
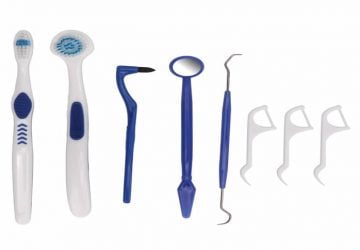
Protect Your Perfect Smile: Master the Art of Defending Your Teeth Against Acid Attacks
Though they may tantalize the palate and invigorate the senses, foods and drinks with high acid content are a double-edged sword with regard to oral wellness. Continual exposure to these substances progressively strips away the protective enamel from our teeth, which can lead to increased sensitivity, changes in coloration, and a variety of other dental complications. This composition offers insight into relishing these zesty favorites while safeguarding your teeth from damage.
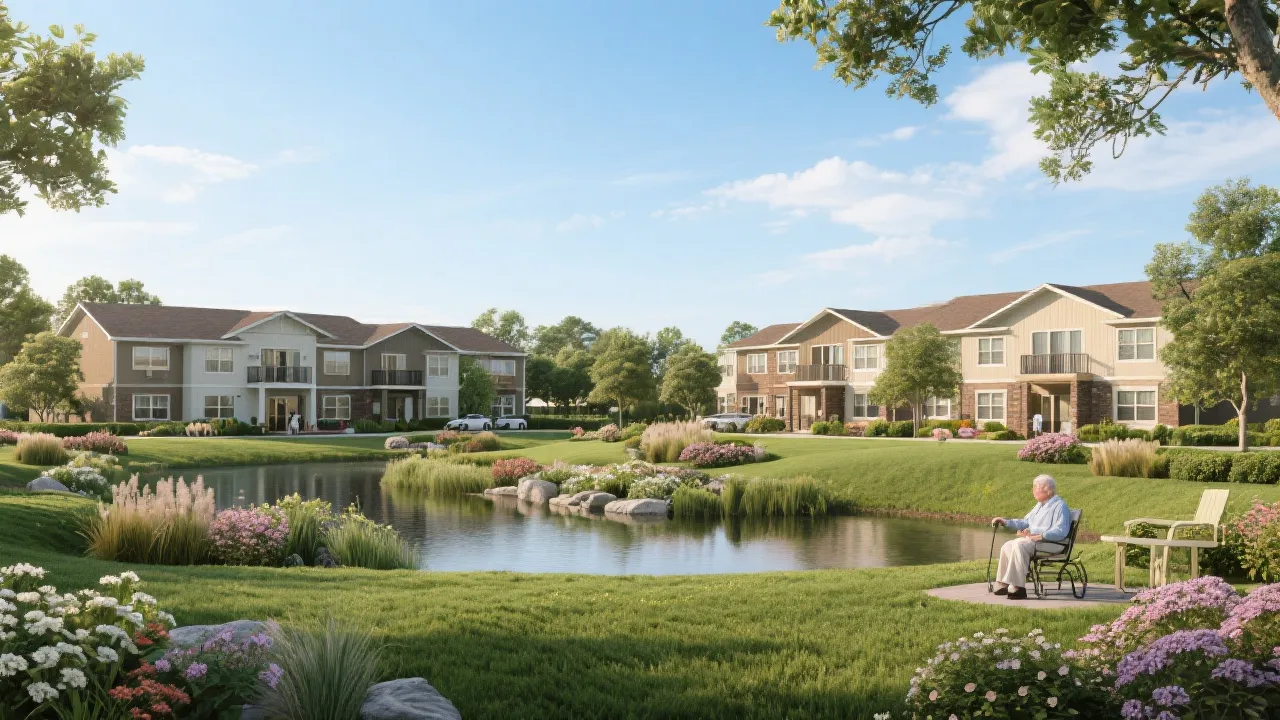
Discovering Heartis Eagle Mountain
Heartis Eagle Mountain is a prominent senior living community that offers a range of services and amenities aimed at enhancing the quality of life for its residents. Situated in a peaceful setting, it combines exceptional care with engaging activities, providing a holistic environment that caters to seniors' physical, emotional, and social needs.
Unveiling the Top Dental Implant Options for Seniors: Transform Your Smile with the Ultimate Guide to Restored Radiance
The significance of oral health cannot be understated for the elderly population as they are commonly afflicted with tooth loss due to a multitude of factors, including decay and gum disease. Dental implants have risen to prominence as a prime method of teeth replacement, acclaimed for their long-lasting nature, functional prowess, and striking similarity to our own teeth. This discussion delves deeply into the realm of dental implants to demonstrate why they are considered the optimal choice for aged individuals aiming to enhance their smiles and overall life quality.
Boost Your Defenses: 20 Proven Strategies for a Stronger Immune System
Having a robust immune system is essential to protect our bodies from harmful microorganisms and preserve our general health. Although some elements that affect our immunity are out of our hands, many lifestyle decisions can help us enhance our immune defenses naturally. This piece delves into 20 practical methods to empower your immune system, increasing your capacity to ward off diseases and sicknesses.