This guide explains how Intuit Payroll supports accurate pay runs, compliant tax handling, and day-to-day payroll workflows. It reviews what payroll teams typically need—employee data, pay schedules, approvals, and reporting—along with practical implementation considerations, risks to watch, and evaluation criteria so you can choose the right setup with confidence.
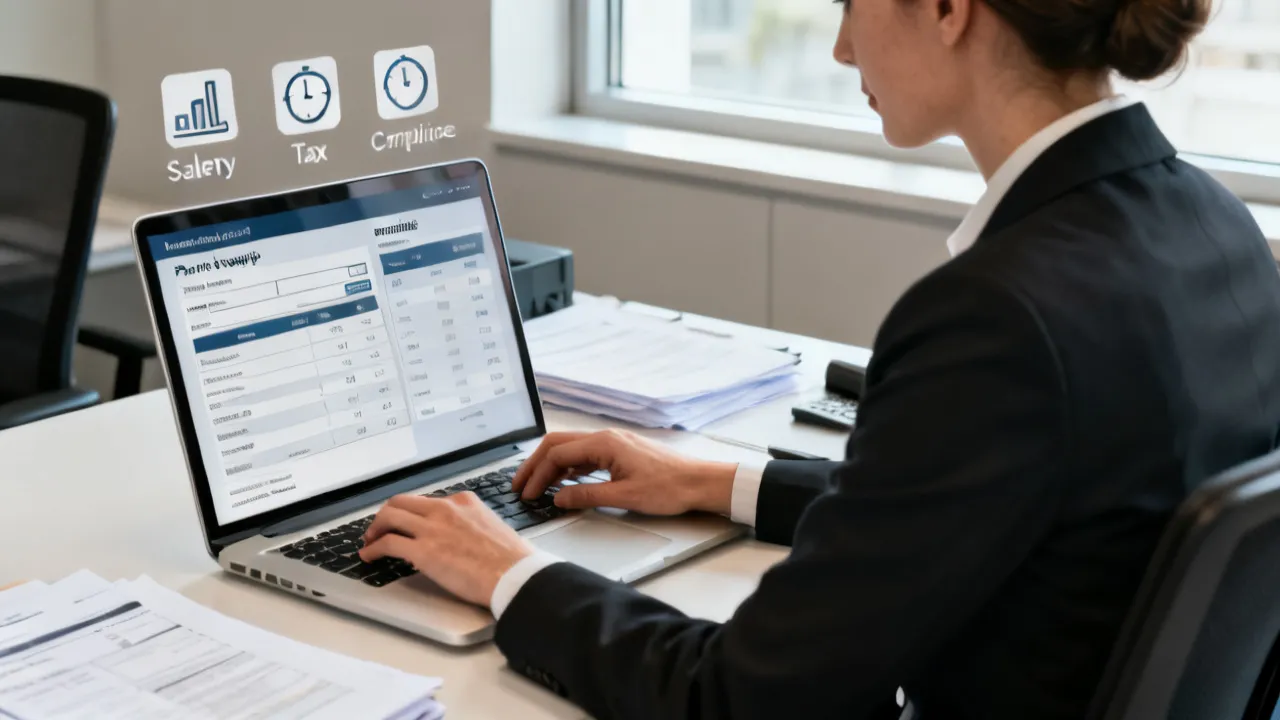
Intuit Payroll is built to help organizations streamline payroll processing, improve pay-run consistency, and support compliant reporting—so payroll teams can spend less time on repetitive tasks and more time on exception handling. For operations leaders, HR managers, and accountants, the key advantage is not just “running payroll,” but doing it with a workflow that connects employee records, pay schedules, deductions, and tax-related outputs in a controlled way.
From an industry-expert standpoint, payroll software succeeds when it reduces manual effort without weakening controls. That means clear pre-pay checks, predictable data flows, auditable approvals, and straightforward reporting for internal review and external obligations. Intuit Payroll is often evaluated precisely on these dimensions: usability for routine tasks, depth of configuration for different employment types, and the quality of output available for year-end and ongoing compliance.
Below, you’ll find a structured analysis of how to think about implementation, governance, and ongoing operations when using Intuit Payroll, along with a supplemental guide presented later in the article.
When you review Intuit Payroll, evaluate it as a system of record for pay inputs and a system of output for payroll and tax documentation. In practice, teams should confirm that the platform supports:
Even the top payroll system can fail operationally if people bypass controls or if processes around updates (new hires, terminations, rate changes) aren’t disciplined. That’s why a “capability list” must be paired with a process review.
Payroll is a recurring cost, but “top value” depends on implementation effort, support quality, and how quickly the organization can reach stable operations. Because exact Intuit Payroll pricing can vary by plan type, payroll frequency, company size, and packaging, the very objective approach is to treat pricing as an itemized business case rather than a single figure.
In supplier evaluation terms, consider the following supplier-related factors:
Practical note: Before committing, request the plan specifics directly from the supplier and confirm costs per pay run cycle, any user tiers, and the expected total cost of ownership over the first 12–24 months (including internal labor for training and validation).
Additionally, cost should include the “hidden” expenses of operational maturity. Payroll teams often underestimate the effort required for:
When you treat Intuit Payroll as a long-term operating system—not just software that calculates pay—you can compare vendors more fairly and reduce the likelihood of unplanned costs later.
From an expert perspective, very payroll issues don’t originate from payroll “logic” alone. They begin earlier—at the point where data enters the system or where approvals are missing. Common failure points include:
To mitigate these risks, a strong payroll governance model should be established around Intuit Payroll: clear owners, defined cutoffs, documented approvals, and a repeatable reconciliation routine after each run.
It also helps to understand the typical “error lifecycle” in payroll operations. Most payroll errors have a pattern: they are either (1) data correctness errors (wrong employee details, wrong rates, missing deductions), (2) timing errors (effective dates and cutoffs not aligning), or (3) process errors (approvals missing, changes applied without review, corrections processed inconsistently). A reliable system reduces the probability of each class of error, but governance ensures that when errors happen, they are detected quickly and corrected consistently.
When using Intuit Payroll, pay particular attention to:
Payroll compliance requirements differ by jurisdiction and employment classifications, and organizations must align their payroll configuration with local rules. While Intuit Payroll can support the mechanics of calculation and reporting, compliance outcomes depend on correct configuration and consistent usage.
To reduce compliance risk, teams should verify:
If you operate near public-facing deadlines (e.g., statutory filing windows), build a calendar that includes internal review time—especially for first-time runs after a migration or a major configuration change.
To strengthen compliance further, consider implementing a compliance checklist by event type. Instead of only validating payroll totals, validate the payroll “event” itself:
Even when the system produces the right numbers, compliance failures can occur when documentation is insufficient. Audit readiness means being able to show configuration basis, approvals, and how exceptions were handled.
Very organizations use multiple systems: HRIS for employee lifecycle, time tracking for hours, accounting software for posting, and sometimes document tools for policy acknowledgments. Intuit Payroll’s effectiveness increases when integration is purposeful.
From an industry viewpoint, the integration strategy should follow a “controls-first” approach:
When integrations are loosely governed, the organization experiences “silent drift”—data differences that become visible only after payroll is processed.
To avoid silent drift, establish integration controls such as:
Another integration dimension is operational ownership. A common failure mode is when payroll managers assume the HR team “owns” data changes, while HR assumes payroll “owns” the pay rules configuration. In practice, you need explicit responsibility for both sides: who updates the master data, who validates the downstream impact, and who approves final payroll run data.
Even when a payroll platform is user-friendly, implementation should be treated like a controlled change. A typical roadmap includes discovery, setup, migration, validation, and go-live with post-launch monitoring.
Key principles include:
Launching with a limited scope—such as a single pay group—can reduce risk while you refine cutoff routines and reporting expectations.
To expand on a robust implementation, consider dividing the work into “streams” that can run in parallel:
Parallel streams reduce total project time, but they also increase the importance of a strong governance cadence (weekly meetings, sign-offs, and documented decision points).
If your organization operates in English-speaking markets, many payroll operations share similar themes—clear pay periods, defined cutoffs, and strong documentation for audits. Yet localization still matters: payroll rules, required reporting formats, and compliance timing vary by jurisdiction. Teams often adopt “local payroll office habits,” such as:
When you configure Intuit Payroll, keep local compliance obligations front-and-center, and ensure that your reporting and record-keeping align with what auditors and regulators typically request.
Localization also affects the human process. For example, if your workforce is distributed across time zones or jurisdictions, your cutoff policy should reflect the time zone reality—otherwise “on time” becomes ambiguous and errors increase.
Common localization pitfalls include:
When localization is handled well, Intuit Payroll becomes a consistent operational engine rather than a source of unpredictable edge-case handling.
The following comparison table reframes supplier and implementation considerations into a checklist you can apply during procurement and deployment planning. It does not include pricing numbers, since plan costs depend on plan selection and business context.
| Category | What to Validate for Intuit Payroll | Inputs You’ll Need | Conditions / Requirements |
|---|---|---|---|
| Setup Readiness | Pay schedules, pay types, deduction definitions, and employee status mapping | HR roster export, payroll configuration assumptions, deduction lists | Defined cutover date; agreed rules for effective dating |
| Data Migration | Quality of employee master data and pay rate history | Historical payroll data (if used), current employee details | Data cleansing process; validation sign-off before go-live |
| Workflow Controls | Approval steps, permission roles, and audit trail visibility | RACI roles, approval policies, cutoff schedule | Separation of duties; documented exception handling procedure |
| Reporting and Reconciliation | Payroll registers, summary reports, and outputs for finance use | General ledger mapping approach, reconciliation templates | Reconciliation performed each run during the initial stabilization period |
| Compliance Outputs | Tax-related reporting forms and summaries | Jurisdiction requirements, employee classification rules | Regular review of reporting requirements when regulations change |
| Integrations | Data flow correctness between HR/time/accounting systems | API/integration specification or export-import schedule | End-to-end test cases for edge conditions (retro pay, terminations) |
| Support and Change Management | Responsiveness to configuration issues and release communication | Support contacts, escalation criteria, internal training materials | Incident log and post-resolution verification process |
To make this checklist even more actionable, you can add a final column called “Evidence.” For each validation item, specify what proof you will retain (screenshots, export files, approval screenshots, reconciliation worksheets, or signed-off test results). Evidence turns validation into defensible governance rather than subjective confidence.
Payroll operations and software selection are typically guided by established governance practices and compliance expectations. For compliance frameworks and control-oriented approaches, many organizations align internal processes with recognized guidance such as:
Because exact documentation and compliance requirements vary by country and industry, you should confirm your local obligations through official regulator guidance and your professional advisors. If you tell me your jurisdiction, I can tailor the compliance and reporting checklist more precisely.
Even without specifying a particular framework, you can apply a practical “control lens” to Intuit Payroll:
These control lenses help payroll teams avoid overfocusing only on calculations and instead build confidence across the entire operational process.
Use the steps below as a structured launch plan. Adjust them to your organization’s payroll frequency, employee mix, and existing systems.
Document who can enter changes, who can approve them, and when changes are allowed before each payroll run. Establish a single escalation path for late items.
To operationalize this step, create a cutoff calendar that includes both HR events and payroll run events. For example:
Define how changes are handled if they arrive after cutoff:
Because Intuit Payroll is designed to follow configured processes, consistent cutoffs reduce confusion and support audit readiness.
Decide where the authoritative employee data lives and where time or hours are maintained. Ensure Intuit Payroll receives correct inputs for every pay cycle.
A strong system-of-record decision typically answers:
When the system-of-record is unclear, you often get duplicate truths. For instance, HR might show a pay rate that payroll doesn’t see because the rate change effective date wasn’t captured in the import process. Clarifying system ownership prevents these “it was true somewhere” disputes.
Set up pay rates, pay types, recurring deductions, and any special cases. Validate effective date logic and confirm how updates apply across future runs.
Configuration success depends on modeling real employment scenarios. Many payroll teams start with a simplistic configuration, then discover later that exceptions require additional pay types or deduction rules. Build an inventory of pay scenarios before configuring:
For effective dating, define a policy for:
Even if Intuit Payroll supports the necessary logic, misconfiguration creates audit risk. A disciplined configuration process reduces the chance of “invisible” issues that only appear in later pay periods or year-end reports.
Clean and validate employee records. Check identifiers, pay rates, deduction eligibility, and termination dates (if importing historical status).
Migration isn’t just importing records—it’s mapping and validating them. At minimum, you’ll want to validate:
To reduce migration risk, run a data quality report before go-live. Many teams create a simple “migration discrepancy list” that categorizes issues by severity:
Then sign off on each critical/high issue before launch. Evidence matters here because the migration “foundation” becomes the starting point for every subsequent audit question.
Conduct a simulation with a small group or historical scenario. Compare results to your prior process totals at both the employee line level and summary totals.
Testing should go beyond totals. True testing includes scenario realism. Consider creating test cases for:
During test payroll, require documentation of:
Parallel checks are particularly useful. Even if you no longer have a legacy system, you can compare against historical payroll outputs or a spreadsheet-based “expected output” model.
Confirm that payroll summary reports reconcile to your accounting approach (e.g., by cost centers, departments, or payroll liability accounts—depending on how you operate).
Reconciliation should not be a manual scramble each time. Build a reconciliation routine that includes:
To strengthen reconciliation, define a “reconciliation tolerance.” For example, you may allow zero variance for line-level comparisons, but allow small rounding variances for aggregated totals. The key is to define tolerances in advance and document them.
During stabilization, reconcile more frequently than you think you need. After 2–3 successful cycles, you can adopt a lighter routine if governance is stable and errors are consistently absent.
Before you finalize the actual run, verify that employee data and changes are complete. Use a checklist that includes high-risk items: new hires, terminations, rate changes, and deductions.
Build a validation checklist that can be completed quickly on run day. Example items:
A mature payroll team treats validation as an operational discipline, not a last-minute effort. If validation occurs too late, errors become expensive corrections and employee support volume spikes.
After the first few pay runs, perform heightened monitoring: review adjustments, check corrections, and collect feedback from HR and finance stakeholders.
Post-run review should include a structured “lesson learned” section. Track:
This post-run approach helps you convert payroll from an event into an improving system. Over time, you refine cutoffs, configuration templates, and integration validation routines.
Maintain a change log for payroll configuration. Ensure only authorized users can make system-level updates and that each change has a business reason and test evidence.
Change control is one of the most overlooked aspects of payroll reliability. Most payroll organizations can “run payroll” even when things are messy. But audit readiness and long-term reliability require controlled configuration changes.
A practical change-control workflow includes:
When change control is weak, payroll teams compensate with extra manual checks, which can mask root issues. Over time, payroll becomes “hero-based” rather than control-based. Strong change control keeps the system predictable.
To keep Intuit Payroll operations stable, organizations should meet these conditions:
To expand on these conditions, it also helps to establish performance metrics for payroll operations. For example:
Metrics create feedback loops. When issues occur, you can focus improvement efforts on the most impactful areas instead of treating every problem as unique.
Intuit Payroll is used to support payroll processing workflows—managing employee pay data, calculating payroll amounts based on configured pay rules and deductions, and producing payroll and reporting outputs that finance and HR teams rely on.
In practice, teams use it not only to calculate net pay, but to generate a structured set of outputs used for accounting postings, internal reviews, employee communications, and tax or statutory reporting.
Use a checklist and run a controlled test payroll before go-live. Validate employee master data accuracy, pay rates, deduction setups, effective dates, and compare outputs to your expected results at both summary and employee line levels.
For thorough validation, add scenario tests for the highest-risk events. Most payroll organizations experience repeated problems in the same categories (retro pay, terminations, deduction eligibility changes). Target those scenarios first.
Yes in many implementations, but reconciliation depends on how your finance team maps payroll components to ledger accounts and cost centers. Ensure your internal reconciliation approach aligns with the reports and summaries Intuit Payroll provides.
To make reconciliation sustainable, document the mapping from each payroll component (gross pay, withholdings, employer contributions, net pay, and liabilities) to accounting outputs. That mapping becomes part of your audit evidence.
Typical drivers include missing or late employee updates, incorrect effective dates, misaligned time inputs, incomplete deduction rules, and insufficient pre-pay validation and approval controls.
Software reduces calculation errors, but not operational errors. When people enter wrong data, skip approvals, or apply changes without verifying the effective date logic, payroll outputs become “correct according to incorrect inputs.” That’s why governance and validation are essential.
Establish a documented policy for cutoff exceptions—such as whether changes apply to the current pay run or the next one. Use an approval step and record the rationale for any override.
It’s also helpful to categorize exceptions. For instance:
Then apply stricter approval requirements for high-impact exceptions.
Yes. The initial pay runs are a critical stabilization period. A post-run review helps you detect configuration gaps, refine workflows, and reduce the need for corrections later.
During stabilization, it’s common to implement “accelerated learning” cycles: identify issues quickly, fix root causes (not only symptoms), and test again with a small subset where possible before expanding.
Build a total cost of ownership view: plan costs, implementation effort, integration work, support needs, and the internal time saved versus your current process. Request plan details from the supplier and validate what is included for your organization size and pay complexity.
Value is not only time savings—it’s also reduced risk. Consider how payroll errors affect employee trust, HR workload, finance close schedules, and potential compliance exposure.
Maintain configuration governance, monitor changes in payroll requirements in your jurisdiction, run regular reconciliation checks, and ensure year-end activities are planned early with data completeness reviews.
Compliance confidence also depends on continuous improvement: periodic audits of deduction configurations, spot checks on employee master data, and a proactive approach to regulatory changes so configurations don’t change under time pressure.
If you’re considering Intuit Payroll or expanding its usage across pay groups, treat the decision like a risk-managed operational upgrade. Prioritize:
In many organizations, the “winning” payroll tool is less about features on paper and more about implementation discipline—clean data, clear ownership, and consistent run-day practices.
To add depth to these recommendations, consider running a pilot governance assessment before full deployment. A governance assessment measures how well you can operate the system under realistic conditions:
These questions help you determine whether Intuit Payroll will become a stable operational engine or remain a source of unpredictable operational friction.
Reliable payroll operations require more than trusting the system’s calculation. Finance teams need certainty that payroll outputs align with ledger expectations and liabilities. A repeatable reconciliation routine provides that certainty and serves as a monitoring control over time.
While the exact reconciliation steps depend on your accounting setup, a robust routine typically includes:
To operationalize reconciliation, teams often create:
During early stabilization, you may perform more detailed reconciliation, including employee-level checks. Over time, you can shift to sampling-based checks if accuracy is consistent and controls are stable.
One caution: reconciliation routines should be updated when configuration changes. If you change deduction rules or introduce new pay types, your reconciliation mapping must reflect the new outputs. Otherwise, the routine may detect differences that are actually expected due to configuration changes—or worse, it might fail to detect real issues.
Exception handling is where payroll teams spend most of their time. A payroll system should help manage exceptions without undermining controls. When using Intuit Payroll, build a clear exception handling procedure for at least the following categories:
For each exception type, define:
Without a standardized exception handling playbook, payroll corrections become inconsistent and auditability drops. That inconsistency often leads to recurring issues and increased employee support volume.
Employee master data is the foundation of payroll accuracy. Even a well configured payroll system can produce errors if master data is inconsistent or incomplete. Data quality controls should therefore be part of routine payroll operations, not only something addressed during migration.
Key employee master data fields that often affect payroll include:
To maintain data quality over time, you can implement periodic controls such as:
These controls reduce the odds that errors will be “baked into” payroll runs and then require corrections later.
Training is often seen as a one-time onboarding task. In payroll operations, training is a continuous capability. The goal isn’t only to teach people how to click through screens; it’s to teach them how to think in terms of controls, cutoffs, effective dates, and reconciliations.
High-value training typically includes:
Runbooks should be written so they can be used under time pressure. A good runbook includes:
When runbooks exist, payroll teams spend less time trying to remember steps and more time ensuring correctness.
Payroll is a high-control environment because it includes sensitive personal information and financial reporting impacts. Permissions and separation of duties should therefore be designed to prevent unauthorized changes and reduce fraud risk.
A common control design is to split:
Separation of duties reduces the risk that a single user can both alter payroll inputs and approve final outputs. Even if fraud risk is low in your organization, separation of duties is a standard control expectation in many audit approaches.
When implementing Intuit Payroll, ensure:
Strong permissions also make operational troubleshooting easier because you can track where changes came from.
Employee self-service (where available) can reduce support workload, but communication quality matters. A self-service portal is effective only if employee notifications and payslip delivery are timely and consistent.
Consider these operational elements:
Even if Intuit Payroll handles the payroll calculations, communication gaps can produce confusion. For example, if employees don’t understand why a deduction changed or why a correction resulted in a different net pay, HR and payroll support volumes increase. Clear communication reduces friction and helps maintain trust.
After go-live, teams often focus on “staying afloat.” A better approach is to establish monitoring for payroll reliability. Continuous improvement turns payroll operations into a process that becomes better over time.
Monitoring can include:
Continuous improvement also includes a periodic control review. For example, every quarter you can review:
This approach prevents the “configuration drift” problem that many payroll operations experience when small changes accumulate without structured governance.
Intuit Payroll can be a practical foundation for payroll processing when your organization approaches it as a controlled system: configure pay rules correctly, manage employee data with discipline, reconcile outputs reliably, and maintain compliance through governance. If you build your rollout around test cycles, approval workflows, and reconciliation routines, you’re far more likely to achieve predictable pay outcomes and reduce operational friction over time.
If you share your jurisdiction and whether you need integrations with HR/time/accounting systems, I can tailor a validation checklist and governance model to match your operating context.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

Unveiling RS Sul Telecom Services
RS Sul Telecom emerges as a prominent entity in the telecommunications industry, providing reliable services across various regions. This article delves into the offerings of RS Sul Telecom, the benefits it presents to both individual and business clients, and its impact on the modern telecom landscape.
Understanding Rlock Advpl in Business
Rlock Advpl represents a pivotal advancement in business software solutions, offering enhanced security and efficiency for enterprise resource planning systems. This article delves into the intricacies of Rlock Advpl, its application in modern businesses, and the benefits it offers in streamlining operations and safeguarding data. As an expert tool, Rlock Advpl is essential for businesses looking to optimize their IT infrastructure.
Unveiling Atranet Innovation
Atranet represents a cutting-edge concept in networking technology. Harnessing its capabilities can transform digital communication by providing seamless connectivity. Designed to optimize data transfer, security, and efficiency, Atranet is shaping the future of how we connect and share information. This article delves into its structure, applications, and potential impacts on industry practices and consumer experiences.
Understanding Polysulfide Adhesive Applications
This comprehensive guide explores the applications and benefits of polysulfide adhesive, highlighting its unique properties and widespread use in construction, aerospace, and automotive industries. Known for its flexibility and resistance to various environmental factors, polysulfide adhesive is a key component in sealing and bonding applications, providing durability and reliability in demanding conditions.
Comparing Vtex with Salesforce Commerce
This article provides an in-depth comparison between Vtex and Salesforce Commerce, two leading digital commerce platforms. Each offers unique features suited to different business needs. Vtex is renowned for its collaborative commerce approach, while Salesforce Commerce shines with its comprehensive customer relationship management capabilities. Explore their differences, strengths, and insights from industry experts.
Understanding the Latest Chrome Version
This article delves into the intricacies and features of the latest Chrome version. Chrome, developed by Google, is one of the very popular web browsers globally, known for its speed, simplicity, and security features. Each update aims to enhance user experience through improved functionality and performance. Understanding these updates is crucial for both everyday users and developers.
