This guide explains how Intuit Payroll supports compliant, reliable paycheck processing for businesses of different sizes. It reviews core concepts behind payroll administration, outlines what teams typically need to implement payroll smoothly, and provides an expert checklist to evaluate fit, setup steps, and ongoing controls—so you can make informed decisions based on operational needs and local compliance.
Intuit Payroll can streamline how payroll is calculated, paychecks are managed, and payroll workflows are maintained—especially when your priority is consistent processing and audit-ready records. The very important step is not “choosing a system,” but matching your organization’s payroll complexity (employees, pay frequencies, deductions, reporting needs, and internal controls) to the capabilities you’ll use day to day. Focus on configuration accuracy, compliance workflows, and data integrity first; then evaluate user experience, reporting clarity, and support responsiveness.
In practical terms, you’re trying to answer two questions before you sign anything:
When those are clear, user experience and “nice-to-have” features become secondary. That’s because payroll failures typically aren’t caused by a lack of features—they’re caused by configuration mismatches, insufficient governance, or unclear accountability between HR and finance.
Payroll is frequently underestimated because it feels repetitive. In practice, payroll processing sits at the intersection of employee trust, regulatory compliance, cash-flow timing, and information security. A small mistake—such as an incorrect filing setting, a misapplied pay rate, an incomplete deduction mapping, or a late adjustment—can cascade into downstream issues: reversed entries, corrected filings, employee payroll disputes, or internal rework.
There’s also a compounding effect: payroll is often the system that “proves” what you paid and why. If your payroll platform produces inconsistent records or lacks traceability, your organization can spend weeks reconstructing “what happened last cycle” when a single report is questioned by leadership, auditors, or employees.
When organizations choose a payroll platform such as Intuit Payroll, they are generally trying to reduce avoidable errors and shorten the cycle between “time worked” and “pay delivered.” From an operations perspective, the real win is consistent handling of payroll inputs (employee data, earnings types, deductions, and pay schedules) and consistent outputs (pay statements, accounting entries, and required reporting artifacts).
But you get those benefits only when payroll becomes a controlled operational workflow, not an ad-hoc set of tasks. Modern payroll software can be an advantage precisely because it can enforce structure: standardized input fields, rule-based calculations, repeatable processing cycles, and documented output that can be reconciled and reviewed.
Think about payroll as a “control system” with three core functions:
A platform helps when it supports all three functions without forcing your team to manually “patch” gaps in configuration.
While exact feature availability can vary by plan and jurisdiction, very modern payroll solutions in the Intuit ecosystem are designed to help businesses:
In professional practice, “supporting compliance” isn’t just about generating reports. It’s about ensuring that your payroll configuration aligns with your workforce profile and that your internal workflow can produce evidence of what was done and when.
To make this more concrete, consider some common day-to-day scenarios where payroll platforms can reduce operational friction:
The operational advantage is that these scenarios become structured tasks that follow a repeatable workflow instead of an improvised routine.
An expert approach is to translate your payroll reality into a short set of requirements and then verify them against the platform’s real usage—preferably with a test group or trial period. Consider the following:
If any of these areas are high complexity, configuration quality and role-based workflow controls become critical. Many payroll issues aren’t “software failures”; they are process mismatches.
To expand this evaluation approach, you should also ask more “operationally realistic” questions during demos and trials:
Finally, assess “organizational fit,” not just functional fit. If your team is small, you may need a platform that is straightforward to administer. If your team is larger, you may need more granular controls, delegation, and governance options.
Pricing for payroll services commonly varies based on factors such as employee count, pay frequency, jurisdictional needs, and selected add-ons. Because pricing structures can change and differ by plan, you should verify current pricing directly with the provider’s official materials or an authorized reseller.
When planning your budget, avoid focusing only on headline cost. Instead, estimate your total cost of ownership by including:
That approach produces a more realistic comparison than comparing only a single monthly figure.
It’s also wise to evaluate hidden cost drivers that appear frequently in payroll transitions:
If you’re comparing multiple systems, request a one-page implementation plan from the provider or reseller. This is not to get “sales promises,” but to establish a baseline timeline so you can budget internal resources accurately.
Even when a business conceptually “buys payroll,” it is often part of a broader ecosystem involving HR tools, accounting systems, tax reporting workflows, and sometimes payment services. Therefore, “supplier” evaluation should include:
From an operational audit viewpoint, your supplier choice affects your ability to explain decisions, reconcile outcomes, and meet deadlines without improvisation.
It can also affect how quickly you recover from issues. A stable payroll supplier isn’t just “always on”—it has repeatable incident procedures, transparent communication, and documented responsibilities.
When evaluating the supplier ecosystem, verify operational alignment across the following:
This is where “supplier” becomes a strategic component. Payroll adoption is not purely a technical project—it’s a service delivery model.
Payroll is highly jurisdiction-specific. If your workforce is based in a particular region, you’ll need settings that reflect local wage rules, withholding requirements, and reporting expectations. In practice, businesses plan for “nearby” coverage: employees may live or work in commuting areas, but the payroll configuration still must match applicable local requirements. It’s wise to confirm how the system handles local tax jurisdictions and whether your setup includes the correct regional parameters before your first full processing run.
For UK- or EU-style payroll environments (conceptually), teams often align payroll workflows with local HR norms—clear pay statement delivery timing, consistent year-end record handling, and careful documentation of employee changes. In North American contexts, teams typically emphasize payroll cutoffs, deduction handling, and timely remittance records. Regardless of geography, the operational discipline is similar: get configuration right, then enforce a repeatable cycle.
To make localization evaluation more actionable, test these areas during a pilot:
Localization isn’t only about taxes. It also affects pay statement content requirements, wage reporting, and sometimes garnishment processes. Even if the software is configured correctly, your internal data collection must also capture the fields the software needs.
That’s why localization evaluation should include a data audit. Before adoption, identify what jurisdiction-related fields you currently store (employee address, work state/province, country, legal entity, tax code equivalents, etc.). Then map those fields to the platform’s required inputs.
Before you run a production payroll, treat setup like a controlled implementation. An expert checklist typically includes the following:
These checks reduce the likelihood that a configuration mismatch will only surface after employees receive pay—when correction is more disruptive.
To expand the checklist into something teams can actually run, you can convert each item into a testable confirmation:
One of the most effective governance practices is to maintain a “configuration evidence file.” This is an internal folder (digital or physical) that stores:
This evidence becomes invaluable during audits, internal reviews, or when questions arise about specific pay runs.
The following section is designed to help you evaluate Intuit Payroll in a structured way. It does not provide pricing figures; instead, it captures decision criteria, typical sources of requirement, and the operational conditions you should confirm.
| Evaluation area | What to compare for Intuit Payroll | Why it matters | Source to verify (official/non-exaggerated) |
|---|---|---|---|
| Feature scope | Core payroll processing, reporting views, employee profile management, adjustment handling | Determines whether common payroll events can be processed without workarounds | Provider documentation and plan descriptions from Intuit |
| Compliance workflow support | Configured settings that match your payroll jurisdictions; ability to produce required records | Reduces risk of filing/reporting misalignment | Local tax authority guidance and the provider’s compliance documentation |
| Accounting alignment | Export or integration outputs suitable for your accounting close process | Helps ensure payroll totals reconcile to finance records | Provider integration guides and your accounting policy documentation |
| Security and permissions | Role-based access, approval controls, and audit trails | Improves internal control and reduces accidental edits | Provider security/administration documentation |
| Operational onboarding | Data import options, setup templates, and onboarding assistance | Impacts time-to-first-correct-run | Provider onboarding guides and implementation top practices |
| Support model | How help is delivered (support channels, escalation, typical onboarding support) | Reduces downtime risk during first pay cycles | Provider support policy pages and terms |
To make this table more useful during evaluation meetings, you can convert each row into a question you bring to the demo:
Use this sequence as a practical implementation plan. Adjust based on your internal HR and finance maturity.
To make adoption smoother, consider adding two additional steps that many teams overlook:
During those stabilization cycles, use a “four-eye principle.” For example, payroll preparers cannot also approve final processing. Even if the team is small, you can enforce a review mechanism with a designated approver.
You can also mitigate risk by selecting test employees that represent your complexity. If all your test employees are simple salaried employees, you will miss the hard cases that usually cause most errors.
These conditions become requirements in practice if you formalize them into a pre-go-live signoff. In other words, you can create a go-live checklist that leadership reviews and signs, based on:
By treating adoption as a controlled change, you reduce the chance that a last-minute setting or missing employee profile breaks production.
Another requirement worth confirming is operational bandwidth: do you have enough time and staff availability between cutoffs and processing deadlines? Payroll systems are typically designed to prevent errors, but timing matters. If your team routinely runs close to cutoff times, you need a process adjustment, not just software configuration.
Payroll modernization is broadly associated with improved process control and better data visibility, not merely convenience. Industry analyses often highlight that organizations adopt HR and payroll platforms to reduce administrative burden, improve reporting accuracy, and support standardized workflows.
For a grounded view, readers can consult reputable sources such as:
Because payroll is regulation-driven, the strongest evidence is less about “percentage improvements” and more about operational outcomes: fewer manual recalculations, clearer documentation, and more consistent audit trails.
To translate “research themes” into a practical adoption lens, consider these typical outcomes organizations target:
However, research also implicitly warns of risks. If modernization is treated as “install software” without process redesign, the organization may simply automate current errors. The advantage comes when payroll modernization supports better governance, data quality, and reconciliation discipline.
One reason payroll evaluations fail is that requirements get described too abstractly. For example, “we need to support hourly employees” is not enough. Hourly payroll complexity usually depends on how overtime is calculated, whether hours are captured accurately, and how deductions interact with different earnings bases.
In this expanded approach, you can categorize payroll complexity into several dimensions and evaluate whether Intuit Payroll can handle each dimension cleanly:
Start with earnings complexity and break it down into these components:
Then test how those components are modeled in the system. Good payroll systems allow your team to record the event once and rely on configured rules to calculate outcomes, rather than requiring manual formulas in spreadsheets or repeated recalculations.
If Intuit Payroll supports the right configuration primitives—effective dates, earnings codes, proration, retro logic, and consistent reporting—you should be able to process typical and edge-case events without bypassing the system’s logic.
Deductions and withholding can be one of the most error-prone areas. To evaluate them, consider:
During onboarding, use test cases that mimic your real deductions. For instance, if you have both a benefits deduction and a retirement deduction, ensure both are configured and verified simultaneously. Problems often appear when one deduction is correct while the other is misconfigured.
Payroll reporting is not only for management; it’s also for internal audit and compliance. Evaluate whether Intuit Payroll provides:
Audit readiness improves when you can answer questions such as:
When you select a payroll platform, you’re buying the ability to explain and prove decisions—not just compute numbers.
The best payroll calculations are still a risk if workflow is unclear. Evaluate internal control complexity by confirming:
In many organizations, the payroll team wants to move quickly and may inadvertently undermine controls. Adoption is the moment to establish discipline: keep roles clear, define escalation paths, and avoid “everyone can do everything” setups.
To operationalize this, set up a RACI model (Responsible, Accountable, Consulted, Informed) for payroll tasks. For example:
This makes it easier to enforce governance and reduce conflict when questions arise.
Even when payroll software is configured correctly, migration work can introduce errors. This is why implementation planning should include specific data quality checks.
Common migration challenges include:
To reduce migration risk, do a “pre-migration audit” in a spreadsheet or data validation tool. Verify that:
Then, once imported into the new system, repeat targeted checks during the pilot. Don’t assume data imported correctly because it “loaded.” Validate the loaded outputs by running payroll for test employees.
Reconciliation is where payroll adoption becomes a finance advantage. Without reconciliation discipline, organizations often discover issues late—after payroll is already delivered and reports are already distributed.
A reconciliation plan should answer four questions for every payroll run:
How you reconcile depends on your accounting approach. Some organizations use direct integration exports; others rely on mapping payroll totals into journal entries. Either approach is valid if documented and consistent.
What matters is that your reconciliation method is repeatable and evidence-based. Your reconciliation checklist should include sign-offs and time stamps where appropriate.
During the first two pay cycles, you may want a more intensive reconciliation approach. For example:
Once confidence is established, the reconciliation may become more streamlined.
User experience matters, but it should be evaluated through operational lens. A payroll UI that is friendly can still be risky if it encourages shortcuts or makes it hard to find errors.
When you evaluate Intuit Payroll’s usability, test how quickly your team can perform essential workflows:
Also evaluate training needs. A system that requires extensive training may increase operational risk for users who change roles or go on leave.
To operationalize usability assessment, ask the provider or implementer for sample workflows and test them yourself. For example, create a mock payroll event (e.g., an overtime week for one hourly employee) and record how the system responds, where errors appear, and how quickly corrections can be made.
Payroll deadlines are unforgiving. During the first cycles, you need support that is responsive and practical. When evaluating support, confirm:
It’s not enough to assume support is “good.” During evaluation, ask for examples of how support is delivered during onboarding. A strong support model will also emphasize preventative guidance—helping your team avoid the most common configuration mistakes.
Many organizations focus heavily on go-live and then relax governance. Payroll governance should continue after adoption because workforce changes, policy updates, and process improvements can introduce configuration drift.
To prevent drift, establish ongoing governance practices:
A mature governance model treats payroll configuration like a controlled environment. If someone can change payroll rules without review, the risk is not only errors—it’s inability to prove what was changed.
Understanding failure modes helps you avoid them systematically. Here are common patterns that organizations experience during payroll adoption:
Many teams run setup and assume that because the system accepts data, results are correct. But correctness requires payroll testing that includes your real complexity: overtime, deductions, retro adjustments, effective dates, and jurisdiction mapping.
Mitigation: run test payrolls with representative employee profiles and reconcile results to expected totals.
Missing pay rates, wrong effective dates, incomplete employment status, or incorrect location fields can produce payroll errors.
Mitigation: perform a pre-go-live employee data audit and validate outputs for each pay category.
If the same user can prepare and finalize payroll without oversight, errors may go unnoticed.
Mitigation: configure role-based permissions and enforce approvals. Add a reviewer role who checks totals and exceptions.
If finance doesn’t reconcile payroll totals to journal entries or expected totals, issues will surface later.
Mitigation: require reconciliation sign-off and maintain evidence for audit readiness.
Payroll deadlines are rigid. If last-minute changes are frequent and unstructured, errors increase.
Mitigation: define a change-control process with cutoffs, approval requirements, and documentation.
When something is wrong, teams may improvise. That can lead to repeated corrections and inconsistent reporting.
Mitigation: implement a formal correction policy and test it during the pilot where possible.
To make your adoption effort more robust, convert the expert checklist into readiness sign-offs. This is helpful because it aligns leadership, HR, and finance around objective criteria.
For example, your readiness sign-offs can include:
This structure reduces ambiguity and creates a defensible narrative about why go-live happened when it did.
It can be, particularly when a small business needs repeatable payroll processing, clearer reporting, and a consistent workflow for approvals and adjustments. The key is whether your pay structure (hourly/salaried, deductions, and adjustment frequency) aligns with what the platform supports without extensive custom workarounds. During evaluation, run a test scenario that mirrors your typical payroll events.
For small teams, the most common issue isn’t “feature gaps”—it’s that there may be fewer people to separate duties or catch errors. So, if you’re small, prioritize role-based permissions and ensure there is a clear review step even if staffing is limited.
Very payroll processes require a formal correction workflow: document what changed, identify the effective date, confirm which payroll run(s) are impacted, then re-run or adjust according to the platform’s correction features. Establish a written correction policy and ensure only authorized personnel can submit changes. The objective is to maintain evidence and reduce repeated errors.
To reduce correction risk after adoption, test corrections during the pilot. For example, simulate a retro pay change for one employee and confirm that the system produces updated outputs and that your reconciliation plan captures the difference.
Verify that payroll configuration—such as withholding-related settings and jurisdiction parameters—matches your workforce circumstances. Use provider documentation and local tax authority guidance. Before your first full run, perform a test review that includes typical employee scenarios and any special deductions you use.
Compliance verification isn’t only about the software. It’s also about the data you collect: employee address/location, effective employment dates, and the correct categorization of employees for withholding rules.
Many payroll platforms provide exports or integration pathways that allow finance teams to reconcile payroll totals to journal entries. Whether it fits your exact chart of accounts and close process depends on your accounting setup and your internal reconciliation method. Validate this during a pilot by comparing expected totals to processed outputs.
When you validate, also check timing. Payroll exports must be available on your schedule to support your close calendar. Confirm the workflow for retrieving exports and mapping totals.
Look for documented security controls such as role-based access, audit logs, secure session handling, and data protection measures. Then verify operationally that your team uses least-privilege permissions: payroll preparers should not have unnecessary rights to approve or finalize without oversight.
Also confirm your internal security practices: who manages user accounts, how access is reviewed for new hires and terminations, and what happens if someone leaves the organization.
Implementation time depends on data readiness and complexity. If your employee records are clean and your pay rules are straightforward, setup may be relatively quick. If you have multiple deductions, retro pay patterns, or complex approval workflows, you should budget more time for configuration, testing, and staff training. A prudent approach is to run at least one test cycle before production.
To estimate more accurately, break implementation into phases: discovery/documentation, data cleanup, configuration, testing/reconciliation, training, and go-live stabilization.
Switching introduces operational risk mainly around configuration, data migration, and process continuity—not typically around “supplier unreliability.” Mitigate by validating outputs in a controlled test, setting up clear approval workflows, and running production with additional review during the first one to two pay cycles.
Also consider continuity planning: confirm how to proceed if you encounter a system issue during a cutoff window, and ensure your team knows the escalation path.
Maintain records of payroll inputs (configuration, approvals, employee changes), payroll outputs (pay statements and totals), and reconciliation evidence (how you verified accuracy). Requirements vary by jurisdiction, but the general principle is to keep enough documentation to explain how and why payroll amounts were computed and processed.
Common evidence sets include configuration snapshots, approved payroll run reports, correction logs, approval screenshots or exports, and reconciliation checklists with sign-offs.
Adopting Intuit Payroll is very effective when treated as process design—not just an IT purchase. By evaluating fit against your payroll complexity, verifying compliance-related configuration, validating accounting reconciliation, and implementing a disciplined approval and correction workflow, you can reduce avoidable errors and strengthen operational reliability. The top outcomes come from careful setup, rigorous first-cycle review, and ongoing governance as your workforce and payroll needs evolve.
The strongest signal you’ve adopted successfully isn’t just that payroll “runs.” It’s that you can confidently answer audit and business questions about each payroll period: what was processed, which rules applied, what changed, and how totals were reconciled. When those answers are easy to produce, payroll transitions from a recurring administrative risk to a dependable operational advantage.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

Exploring the Retipster Club Advantage
The Retipster Club is an invaluable resource for real estate investors, offering a plethora of insights, tools, and community support to boost investing endeavors. Aimed at helping both novice and seasoned investors, the club provides educational materials, success stories, and expert strategies tailored to the ever-evolving real estate market landscape. Dive into this analysis to understand the manifold benefits the Retipster Club offers to enhance real estate success.
Navigating the Retipster Club
This article delves into the unique offerings of the Retipster Club, a community designed for individuals interested in real estate investment, providing educational resources and networking opportunities. Discover how the club supports its members through expert advice, comprehensive guides, and a robust community platform, all tailored to foster insightful and profitable investment strategies.
Pmoc Abrava: Practical Procurement and Quality Considerations
This guide explains how to approach Pmoc Abrava procurement with a quality-first, compliance-minded process. “Pmoc Abrava” is discussed as a term used in sourcing contexts, covering typical decision factors such as specification clarity, supplier capability, documentation, and handling requirements—using an objective framework for safer purchasing, risk control, and consistent performance.
Unveiling Grunig & Hunt's PR Models
This article explores the seminal work of Grunig & Hunt in developing models of public relations. The Grunig & Hunt models, fundamental to understanding PR theory, provide insight into the strategic approaches and methodologies utilized in the field. Each model offers a distinctive perspective on communication and engagement strategies, relevant to both academic discussions and practical applications.
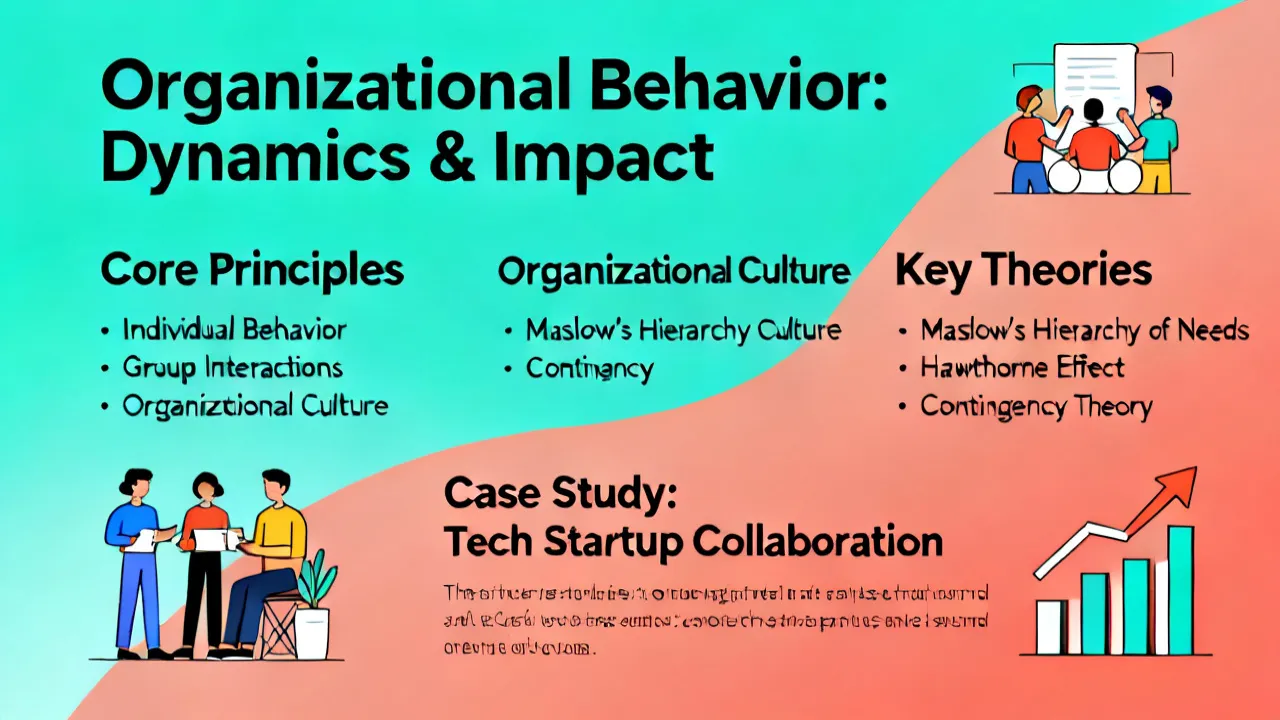
Understanding Organisational Behaviour Slideshare
This article delves into the significance of Organisational Behaviour Slideshare for both educators and professionals. Organisational Behavior is a field that examines the impact individuals, groups, and structures have on behavior within organizations, aiming to improve an organization's effectiveness. With Slideshare's platform, these insights are easily shared, promoting a collaborative learning environment.
Understanding Ltda Epp for Supplier and Compliance Decisions
Learn how “Ltda Epp” impacts supplier selection, contract structure, and compliance planning. This guide explains, in objective terms, what the label typically signals in company registration and how it can affect procurement processes, risk checks, and document readiness. It also frames practical conditions, comparison points, and decision steps to help you evaluate suppliers with clarity and consistency.
