This guide explains how to manage contractor payments and prepare Square Payroll 1099 reporting with an objective, compliance-first approach. It outlines the purpose of 1099-NEC and common contractor documentation practices, clarifies what data must be accurate, and provides expert considerations for recordkeeping, review workflows, and eligibility requirements.
If you pay independent contractors through Square Payroll, your goal is to capture payment details accurately enough to support 1099 reporting where applicable. Start by aligning your payout records to the IRS definitions for “nonemployee compensation,” then implement a review workflow that validates contractor identities and totals before you file. Treat documentation—W-9 collection, payment logs, and reconciliation—as a controls system, not an afterthought.
From an industry perspective, the top results come when finance, HR/operations, and the person generating tax forms share the same source-of-truth: your payment ledger. In practice, Square Payroll 1099 workflows succeed when they are treated like a repeatable process with clear conditions, audit trails, and end-of-year checkpoints.
Note: This article provides general guidance and process considerations. Tax obligations depend on your specific facts and jurisdiction; consult a qualified tax professional for advice.
“Square Payroll 1099” is commonly used to describe the operational steps around reporting contractor payments using Square-based payroll records that may need to flow into IRS Form 1099 series filings (very notably Form 1099-NEC for certain nonemployee compensation). In many businesses, the term effectively refers to end-of-year reporting workflows that connect payment data, contractor identities, and form-ready totals.
Objectively, a 1099 reporting obligation is triggered by the IRS rules governing payments to nonemployees. For many businesses, the operational challenge is not merely generating a form, but ensuring the underlying inputs—who was paid, how much they were paid, and whether the contractor supplied required tax identity information—are consistent and complete.
To put it another way: Square can help you capture payout events, but the “1099” portion is fundamentally an information-reporting system. That system needs accurate and traceable information. When businesses interpret “Square Payroll 1099” as only a software export task, they often discover gaps later—missing W-9 data, mismatched names/TINs, totals that don’t reconcile cleanly, and inconsistent classification of what counts as reportable compensation.
Therefore, the right mindset is to treat the process as an end-to-end workflow: contractor onboarding and identity management → payment capture and classification → reportable totals computation → reconciliation and exceptions → review → filing and distribution → archival and retention.
From a compliance and risk standpoint, inaccuracies can lead to corrected forms, delayed filings, contractor inquiries, and increased scrutiny. The IRS requires that information returns be accurate and timely. Inconsistent totals between your accounting records and the amounts reported can create avoidable administrative and tax complications.
Reliable reference points include:
For authoritative details, businesses typically rely on the IRS official instructions for the relevant tax form and the IRS information returns filing guidance for the specific tax year.
Beyond compliance, there are operational consequences. Incorrect identity fields—such as a name that doesn’t match the contractor’s tax records or a TIN entered with formatting errors—can cause electronic matching failures. If a contractor receives a 1099 with a mismatched TIN/name combination, the contractor may contact you to correct it, or the issue may surface when you reconcile data with what the IRS receives.
In addition, corrections have a domino effect. If you adjust totals late in the season, you may need to regenerate files, re-check recipient distribution timing, and update internal records. These “late season” changes are also harder to audit because the documentation trail becomes fragmented. In contrast, when you design the process for accuracy earlier, you reduce rework and preserve confidence in your numbers.
Accuracy also matters for internal decision-making. Many businesses use payment totals for budgeting, contractor management metrics, and cost-of-services analysis. If those totals are wrong, your operational reporting can be wrong too. A single process that supports both 1099 reporting and internal analytics can pay dividends.
While each company’s setup differs, successful “Square Payroll 1099” processes often resemble this structure:
To expand that workflow into a practical operational design, consider that each step has “quality checks” and “handoffs.” For example:
In many organizations, end-of-year reporting is a high-stakes cycle with limited time. Professionals therefore emphasize controls rather than last-minute cleanup. Consider:
Controls aren’t necessarily heavy bureaucracy. In practice, a “defensible” process can be lightweight but structured. The key is that you can answer, quickly and consistently: “Where did this number come from?” and “Who approved the exception decisions?”
For example, separation of duties can be implemented in several scalable ways:
Change control is particularly important for contractor identity. If a contractor’s name or TIN is corrected after you have produced initial drafts, you need a record of:
This is not only useful for compliance. It also supports smoother internal communication. Without change logs, you can’t easily explain why an amount shifted or why a name appears differently than the prior draft.
The scope of 1099 reporting hinges on what payments are considered reportable “nonemployee compensation.” In practice, businesses need to evaluate contract types, payment categories, and operational arrangements.
From an objective compliance standpoint:
Because classification drives reporting, the “Square Payroll 1099” process should include a brief review of payment categories and contractor scopes—not just a totals exercise.
To make this actionable, you can think of reportability classification as a mapping exercise. Square records and your operational categories might be organized in one way, while IRS reporting categories may be defined differently. The mapping is where mistakes often occur.
For instance, your organization may categorize spend by service type (“design,” “consulting,” “marketing”) or by internal department. However, reportability depends on the underlying arrangement and what counts as nonemployee compensation for the applicable 1099 form. Therefore, your process should document a classification rule set that determines which transaction types flow into the reportable totals.
In practice, companies often use one of two methods:
Either approach can work, but the organization must be able to explain the rule set. If you cannot explain why an amount is included, excluded, or categorized into a reportable bucket, your process becomes fragile.
Another classification risk is mixing reportable and non-reportable compensation within the same contractor relationship. For example, a contractor may perform some reportable services and also receive reimbursements for certain costs (depending on facts). A defensible workflow accounts for these scenarios by tracking which payments are part of the reportable amount and which are excluded under your documented logic.
Very reporting errors trace back to identity and tax information mismatches: incorrect names, missing TINs, or inconsistent entity type details. A structured intake process helps.
Consider implementing these controls:
This reduces rework and improves consistency between your records and the reported form data.
To expand this control into a system, consider the full life cycle of W-9 data. Many teams only think about W-9 collection at the start of the engagement, but issues can arise later:
A robust workflow usually includes a verification step. Verification does not necessarily mean you must guarantee IRS-level matching in every case, but you should implement a quality check such as:
Also, “W-9 collection” is often a collaborative process. If operations or HR onboard contractors but finance generates 1099s, you want a standardized handoff. That means having a shared checklist or ticket workflow that states: “No payments are considered report-ready until W-9 is received and stored properly.” For companies that pay frequently, this can prevent end-of-year surprises.
If you handle a large contractor base, consider segmenting your outreach strategy. For example, you might categorize contractors by payment frequency, payment size, or whether they are new vs. recurring. Then you can prioritize follow-up for those most likely to need a 1099.
Reconciliation is where many organizations either prevent issues or discover them late. A robust approach aligns totals by contractor and by payment window.
For example, you can:
Keep in mind that reporting totals may not mirror financial income exactly if your chart of accounts or accounting categories differ from reporting categories. The reconciliation method should therefore be designed to support the reporting definition, not only the bookkeeping presentation.
It helps to distinguish between two reconciliation goals:
Those two goals may overlap but are not always identical. For instance, your accounting might allocate expenses across cost centers or categories, while 1099 reporting might depend on payment classification. As a result, it’s common that you reconcile in more than one dimension: total payments overall, then drill down to contractor-level reportable amounts.
A practical reconciliation design might include the following components:
When reconciliation is done well, it becomes a “proof” that you applied the reporting rules consistently. When done poorly, it becomes a list of unexplained differences that you cannot resolve confidently.
To improve reconciliation quality, many teams also perform a sampling step. For example, they might select a small subset of contractors—those with the largest amounts, those with new onboarding, and those with unusual patterns—and verify the totals directly back to individual transactions. Sampling helps validate that the mapping from Square to reportable totals works as intended.
Even without quoting specific dates (since IRS filing deadlines can vary by year and administrative circumstances), a disciplined internal timeline usually improves quality. Common top practice involves:
This approach reduces rushed corrections and supports smoother distribution to contractors.
A filing season calendar is not just about “when” tasks occur; it’s also about “what” must be completed and “who” owns each task. A simple calendar can include:
Many organizations underestimate the time required for exception resolution. Even if your reconciliation is fast, missing W-9s and identity issues require follow-ups and sometimes require guidance on how to handle TIN-related situations. If you wait until late year, you reduce your ability to respond thoughtfully and document your decisions.
Another scheduling tactic is to run “mini-reconciliations” during the year. For example, quarterly or mid-year checks can detect problems early—like a payment classification rule that started being applied incorrectly due to a change in operational coding. Fixing early prevents year-end total distortions.
The table below compares practical options for structuring a contractor reporting workflow using Square Payroll records. It is written as a supplement to your main process, with conditions and requirements so you can decide what fits your operations.
| Process option | Top fit for | Step-by-step execution (high level) | Conditions / requirements |
|---|---|---|---|
| System-led totals | Small to mid-size teams with consistent payment categories |
1) Extract contractor payment totals from Square Payroll for the reporting period. 2) Validate contractor identity fields are present. 3) Reconcile totals to accounting records by contractor. 4) Review exceptions and finalize report-ready amounts. |
You must define the authoritative ledger and document any adjustments. |
| Ledger-led reconciliation | Teams with complex categories or multiple payment types |
1) Start from accounting entries that correspond to reportable payments. 2) Trace back to Square Payroll events for auditability. 3) Prepare contractor totals aligned to the reporting definition. 4) Confirm tax identity completeness before form generation. |
Requires clear mapping between payment classifications and reporting buckets. |
| Two-person review workflow | Organizations prioritizing internal control and reduced error risk |
1) Preparer generates report data from Square Payroll. 2) Reviewer validates identity fields and payment totals. 3) Both sign off on exceptions and final totals. 4) Archive the supporting documentation. |
Must define roles, review criteria, and an exception resolution process. |
In practice, many organizations use a hybrid model. For example, they might run system-led totals extraction for efficiency, but still do ledger-led validation for a subset of contractors or for the exception cases. Or, they might implement two-person review as a control layer even if totals come directly from Square.
Whichever approach you choose, you should be able to articulate why it is appropriate for your business. If your payment categorization is consistent and your contractor onboarding process ensures W-9 completeness, system-led totals may be sufficient with proper review. If your accounting has complex allocations and you need to ensure reportability classification aligns with IRS rules, ledger-led reconciliation may reduce risk.
This supplement is grounded in widely used IRS information reporting principles for Form 1099 series obligations and the importance of accurate TIN/name data and recordkeeping. For authoritative details, use the IRS official instructions and filing guidance for the specific tax year and form (for example, Form 1099-NEC instructions when applicable). If you handle backup withholding scenarios, rely on IRS guidance related to TIN verification and withholding requirements.
Even without quoting IRS text in detail, you can build a defensible workflow by ensuring it covers the themes the IRS emphasizes across information returns:
Many tax professionals view recordkeeping not as a compliance burden but as a risk management mechanism. When there is an error, the ability to reconstruct and correct quickly helps reduce downstream impact.
The following guide is intentionally practical and process-focused.
Identify which contractor payments are potentially reportable under the relevant 1099 form rules. Document your classification logic (e.g., what payment types you treat as reportable versus non-reportable).
Ensure each contractor has the required tax identity information on file (commonly collected via a W-9 in the U.S.). Track missing or invalid information early to avoid end-of-year rush.
Generate contractor payment totals for the applicable reporting period using your Square Payroll records. Use consistent date boundaries and document how totals were derived.
Compare system totals to ledger totals. For differences, investigate and categorize them (timing differences, reversals, refunds, or classification adjustments).
Flag outliers such as extremely high or low amounts, contractors with missing tax info, and cases where identity fields appear inconsistent.
Review name/TIN alignment and contractor entity type details. Fix data issues through documented edits rather than ad-hoc corrections.
Ensure that your “reportable” totals follow the rules you documented. Do not assume that every payout automatically belongs in the reportable bucket.
Use a checklist and require a second review step for final approvals. Ensure amounts and identifiers match the approved totals.
Archive backups: exports, reconciliation workpapers, documentation of exceptions, and contractor tax identity records.
To further strengthen the step-by-step guide, consider adding micro-controls around each step—controls that make errors less likely and make detection faster. Examples include:
These micro-controls help turn the process from “a set of tasks someone does” into “a controlled system you can defend.”
Defensibility also depends on the consistency of how your team behaves across the year. A process that works in theory but breaks during busy periods tends to accumulate silent errors. So it helps to set behavioral expectations early, such as:
Additionally, “traceability” should be practical. You don’t need every possible link to be manually documented line-by-line for every contractor, but you should be able to locate supporting information for each exception and for the overall mapping logic.
Many teams find it helpful to create a “reporting package” folder structure that includes:
This reduces the time it takes to respond to internal questions or external inquiries.
It typically refers to the end-of-year workflow of using Square Payroll payment records to support IRS 1099-series reporting for independent contractors. The specific 1099 form depends on the payment types and IRS reporting rules applicable to your business.
Not necessarily. Reportability depends on the IRS rules for the relevant form and the nature of the payments. Your classification logic—what you treat as reportable nonemployee compensation—should be documented and consistently applied.
In many U.S. contractor workflows, a W-9 provides tax identity information needed to produce accurate information returns. Missing or inconsistent identity details are a common source of corrections, so collecting and validating W-9 information early helps reduce risk.
Use a method aligned to the reporting definition, not only to accounting categories. Compare contractor-level totals for the reporting period, investigate differences (timing, refunds, reversals, classification changes), and document your findings in reconciliation workpapers.
Use a defined exception process: flag the account, follow up promptly for missing information, and involve responsible leadership or your tax professional for how to handle unresolved issues under IRS rules (including potential TIN-related requirements).
No. This article is general process guidance. Tax obligations are fact-specific and may vary by jurisdiction and transaction type, so consult a qualified tax professional for advice tailored to your situation.
Record retention periods can vary based on applicable rules and internal compliance policies. As an objective top practice, retain reconciliation workpapers, exported payment data, contractor identity documents, and any exception documentation for the duration required by law and your organization’s policy. Check IRS guidance and your professional advisors for specifics.
Most corrections stem from identity and total mismatches. To reduce them:
An audit trail is evidence that supports how your final numbers were produced and approved. Typically it includes:
Not always. Your 1099 reporting scope may vary by payment type and contract structure. Your workflow should apply consistent internal logic for what is reportable and what is excluded, but you can maintain separate mapping rules and reconciliation steps for different categories when needed. The important requirement is that your inclusion/exclusion logic is documented and consistently applied.
To expand on these pitfalls, it helps to understand why they happen. Common root causes include:
To counter these root causes, organizations often implement:
Square Payroll 1099 reporting works top when it is treated as a structured controls process: correct inputs (identity and tax documentation), consistent payment capture, defensible totals through reconciliation, and a disciplined review workflow. By focusing on traceability and exception management, businesses can improve accuracy, reduce year-end strain, and support smoother information return preparation in line with IRS information reporting expectations.
When the process is designed as a system—complete with clear conditions, audit trails, separation of duties, and exception handling—it becomes repeatable. And when it is repeatable, it improves year-over-year. Each reporting cycle teaches you where data quality breaks down, where classification rules need refinement, and where your internal handoffs can be strengthened. That continuous improvement is what turns a “1099 scramble” into a predictable compliance workflow.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

Exploring the Retipster Club Advantage
The Retipster Club is an invaluable resource for real estate investors, offering a plethora of insights, tools, and community support to boost investing endeavors. Aimed at helping both novice and seasoned investors, the club provides educational materials, success stories, and expert strategies tailored to the ever-evolving real estate market landscape. Dive into this analysis to understand the manifold benefits the Retipster Club offers to enhance real estate success.
Navigating the Retipster Club
This article delves into the unique offerings of the Retipster Club, a community designed for individuals interested in real estate investment, providing educational resources and networking opportunities. Discover how the club supports its members through expert advice, comprehensive guides, and a robust community platform, all tailored to foster insightful and profitable investment strategies.
Pmoc Abrava: Practical Procurement and Quality Considerations
This guide explains how to approach Pmoc Abrava procurement with a quality-first, compliance-minded process. “Pmoc Abrava” is discussed as a term used in sourcing contexts, covering typical decision factors such as specification clarity, supplier capability, documentation, and handling requirements—using an objective framework for safer purchasing, risk control, and consistent performance.
Unveiling Grunig & Hunt's PR Models
This article explores the seminal work of Grunig & Hunt in developing models of public relations. The Grunig & Hunt models, fundamental to understanding PR theory, provide insight into the strategic approaches and methodologies utilized in the field. Each model offers a distinctive perspective on communication and engagement strategies, relevant to both academic discussions and practical applications.
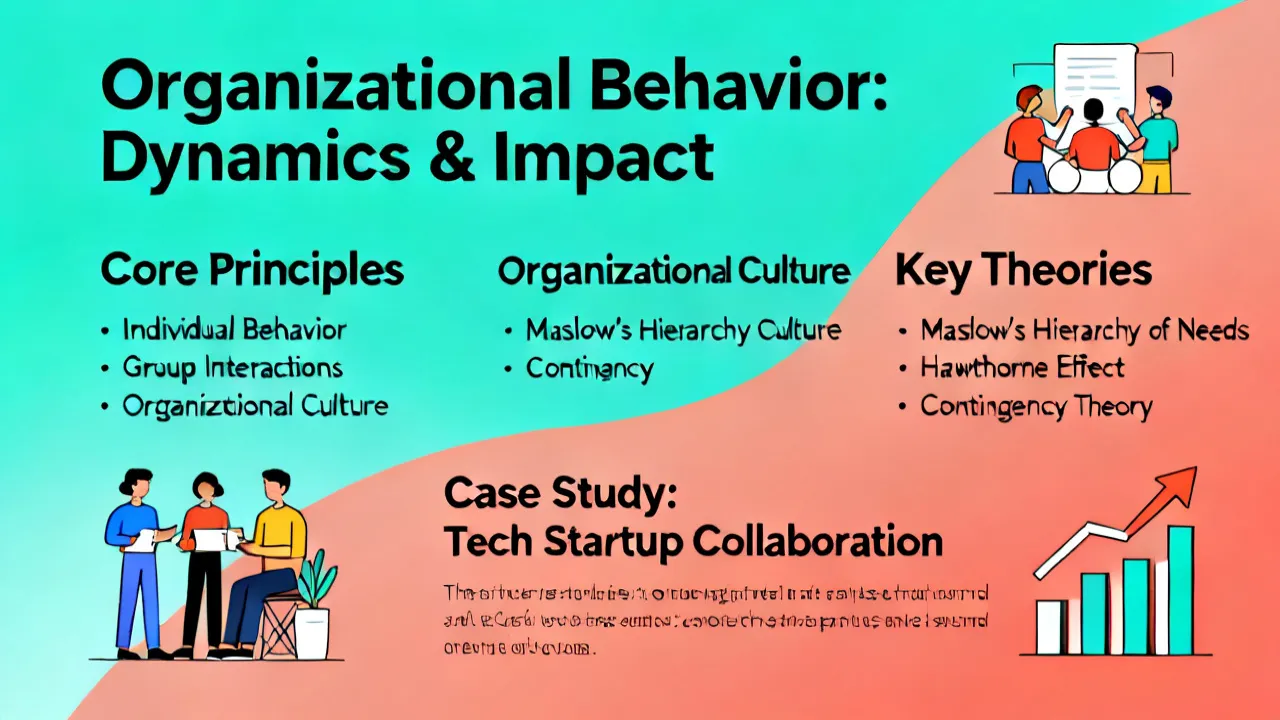
Understanding Organisational Behaviour Slideshare
This article delves into the significance of Organisational Behaviour Slideshare for both educators and professionals. Organisational Behavior is a field that examines the impact individuals, groups, and structures have on behavior within organizations, aiming to improve an organization's effectiveness. With Slideshare's platform, these insights are easily shared, promoting a collaborative learning environment.
Understanding Ltda Epp for Supplier and Compliance Decisions
Learn how “Ltda Epp” impacts supplier selection, contract structure, and compliance planning. This guide explains, in objective terms, what the label typically signals in company registration and how it can affect procurement processes, risk checks, and document readiness. It also frames practical conditions, comparison points, and decision steps to help you evaluate suppliers with clarity and consistency.
