This guide explains how to manage Square Payroll 1099 reporting for independent contractors with a clear, objective approach. You’ll learn what “Square Payroll 1099” typically means, how 1099-NEC and related forms affect businesses, and what documentation practices reduce filing errors. Background context covers IRS basics, recordkeeping expectations, and workflow considerations.
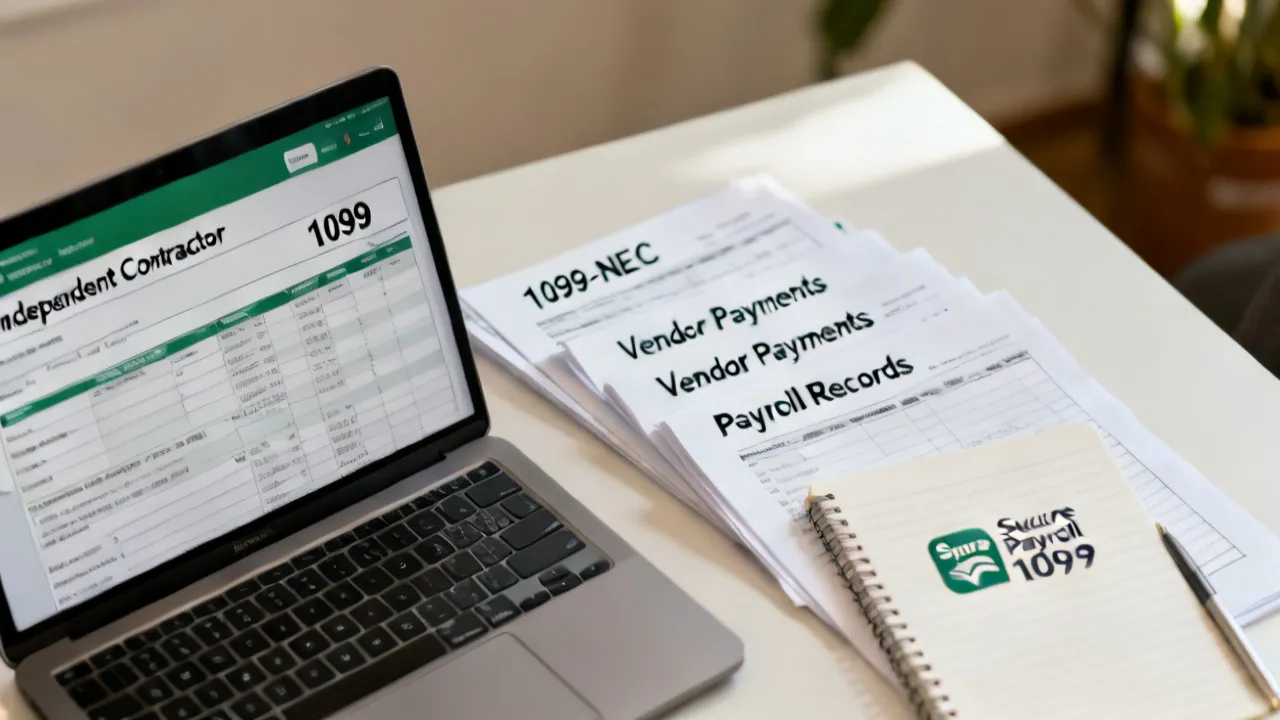
If you use Square Payroll (or processes tied to Square Payroll) and you may have independent contractors, your first priority is to confirm whether you must issue a 1099-NEC and to establish a reliable data trail for who was paid, how much, and under what tax year. This is the practical heart of “Square Payroll 1099” for many small and mid-sized businesses: accurate contractor identification, payment aggregation by tax year, and timely preparation of IRS forms and statements.
From an expert workflow standpoint, the goal is not just to “generate forms,” but to align your operational records (invoices, contractor profiles, payout schedules, and payment confirmations) with IRS reporting expectations. When you get that alignment right, the rest—review, reconciliation, and delivery—is comparatively straightforward.
Important: Tax rules can be nuanced and fact-specific. The discussion below is educational and focuses on standard compliance practices commonly used in contractor payment reporting. For definitive obligations, consult official IRS guidance or a qualified tax professional.
In the United States, businesses often report certain payments to non-employees using IRS forms commonly referred to as “1099s.” For independent contractors, the very relevant form in many scenarios is Form 1099-NEC (Nonemployee Compensation), which is typically used to report certain payments made to people who are not treated as employees.
While details depend on circumstances (for example, the type of services, payment arrangement, and the contractor’s status), businesses generally aim to capture three core elements:
This is where a payroll or contractor-payment system like Square Payroll often becomes operationally relevant: it can help centralize payout data that you later need for reporting.
However, “centralize” is not the same as “compliance automatically happens.” A platform can simplify reporting, but your compliance obligations still depend on correct contractor classification, correct taxpayer information, correct aggregation rules, and diligent review.
In practice, very reporting problems stem from predictable sources: incomplete contractor profiles, mismatched names, late collection of tax forms, and payment categorization that doesn’t match the reporting basis. A robust process addresses those early.
Below are core actions that reduce the risk of creating a year-end scramble. Think of these as “build the reporting engine” steps rather than last-minute paperwork steps.
Before generating any “Square Payroll 1099” outputs, validate who is actually a contractor (non-employee) and whether you have contractual arrangements consistent with independent contractor status. Misclassification can create cascading tax problems—both reporting and payroll-related.
This matters because if you incorrectly treat an employee as a contractor, you might fail to withhold payroll taxes and may misreport payments. Conversely, if you treat a contractor like an employee, you may miss a 1099-NEC reporting obligation, depending on the facts.
Practical way to do this early:
Even if your main focus is 1099 reporting, classification is the first domino in the compliance chain. When classification is wrong, everything downstream—payment totals, forms, and documentation—gets harder to fix.
Many businesses rely on contractor-provided information to produce accurate 1099 reporting. A missing or incorrect taxpayer identification number can lead to compliance friction and potential penalties.
Most businesses collect the contractor’s tax information on Form W-9. Your goal is to have the contractor provide:
Why validation matters: W-9 details are sometimes entered with formatting differences (e.g., spacing, punctuation, capitalization), and the platform may display names in a way that differs from what’s on the W-9. You want to ensure the “recipient record” in your reporting system matches the W-9 as closely as possible.
Practical validation steps:
As you do this, create a “tax info readiness” standard: you should know which contractors are complete and which are pending so year-end doesn’t become a guessing game.
Your reporting totals should reflect the correct tax year and the correct payment categories. Even if Square Payroll tracks payouts clearly, you should reconcile totals against your payout/export reports and supporting accounting entries.
Here’s the key mindset shift: 1099 reporting is about aggregation by tax year, not merely about “payments that happened during the year” in an informal sense. The IRS requires reporting based on the tax-year amounts that meet the reporting rules (and those rules may incorporate details about the payment type and when it counts).
Common reconciliation risk points include:
To keep this under control, reconcile in layers:
When you reconcile in layers, you can quickly isolate where discrepancies arise instead of discovering them after forms are drafted.
Forms are only as good as the underlying data. Review contractor names, tax identification numbers, and payment totals for each recipient. If you spot an issue, resolve it while there’s still time to correct data and re-export or regenerate statements.
Recipient-level review is often the highest-impact step. Many businesses can reconcile total amounts but still make errors in individual recipients due to:
Good review practice includes:
Correction should not be an afterthought. Treat it as part of the workflow.
“Square Payroll 1099” is often used as shorthand for the reporting workflow around independent contractors paid through a system that integrates with payroll-like features. Even when a platform is not literally a “1099 form generator” in the narrow sense, teams commonly refer to their end-to-end process as “Square Payroll 1099” when it covers:
From an industry perspective, the top approach is to treat these as operational controls rather than a last-minute filing task. Year-end should be a finishing step—not the first time you reconcile totals.
To make it more concrete, consider what “Square Payroll 1099” means in practice for a small business owner:
When those elements are built during the year, year-end becomes more predictable.
Below is a practical supplement you can use to compare a typical “Square Payroll 1099” setup with a more manual or accounting-led approach. This is designed to help you decide how to structure your process, not to claim that one method is universally superior.
| Area | System-assisted approach (often aligned with “Square Payroll 1099”) | Accounting-led approach (manual reconciliation emphasis) |
|---|---|---|
| Primary data source | Payout tracking and contractor profiles within the platform | General ledger, payment batches, vendor/contractor master data |
| Data validation | Profile checks, tax detail completeness, export review | Cross-checks between GL lines and recipient-level totals |
| Reconciliation | Compare platform totals to accounting reports by payout date/tax year | Reconcile accounting totals first, then map to recipients |
| Recipient-level accuracy | Review each recipient’s name/TIN and total payments from exports | Validate recipient records directly from accounting/vendor master |
| Audit trail | Use platform records plus exported statements and adjustment logs | Use GL history plus payment confirmations and adjustment memos |
| Common failure mode | Late profile updates or partial contractor data | Mapping errors between GL entries and recipients |
| Typical top practice | Run interim checks (e.g., monthly) to catch drift before year-end | Maintain a consistent chart of accounts and vendor/contractor mapping rules |
The following content is framed as general compliance guidance based on IRS form instructions and general reporting principles. Because requirements can vary by facts and payment types, treat this as a structured checklist rather than legal advice.
Sources (official or commonly referenced): IRS instructions and IRS guidance related to Form 1099 series reporting and nonemployee compensation, including the annual Instructions for Forms 1099-NEC and IRS resources on 1099 reporting and taxpayer identification number (TIN) handling.
Step-by-step guide
Conditions/requirements to watch
Many business owners use the phrase “Square Payroll 1099” to describe a year-end routine that blends payroll-like data handling with independent contractor reporting. Depending on your setup, this can include:
Even when you rely on Square-related exports, your compliance still depends on your review and reconciliation. In other words, “Square Payroll 1099” is top treated as a data pipeline that supports your obligation to report accurately.
It can help to separate two tasks that are often mixed:
When operational controls are strong, reporting tasks become easier and less error-prone.
It’s commonly used to describe the year-end workflow for independent contractor reporting when your contractor payments are tracked through, or organized alongside, Square Payroll-related processes. The compliance goal is to determine whether you must report certain payments on IRS 1099 forms (often 1099-NEC for nonemployee compensation) and to prepare accurate recipient statements and filings.
No. Whether you must file depends on factors such as payment type and contractor status, as described in the applicable IRS instructions for the tax year. The correct approach is to review your situation against current IRS guidance and consult a tax professional for edge cases.
Typically, you should reconcile recipient identity data (legal name and TIN) and payment totals by tax year. You should also confirm that the sums from your system exports match the totals in your accounting records, with documentation for any adjustments.
Use a single source of truth for contractor profile information, verify incoming contractor tax information promptly, and implement a pre-filing review step that flags inconsistencies. If you find errors, correct them before filing and document the changes.
Incomplete or inconsistent tax information can prevent accurate reporting. Your top course is to follow IRS guidance and your internal compliance process for requesting corrected information, then reconcile totals once the corrected data is obtained.
Exports are a helpful starting point, but you should still perform a review and reconciliation. Platforms can reduce manual work, yet the compliance outcome depends on accuracy of the underlying data and your adherence to IRS requirements.
Yes. Filing and recipient statement deadlines are specified by IRS guidance for each tax year. Plan early by running interim checks well before year-end so that corrections can be made in time.
Record retention expectations depend on circumstances and applicable legal requirements. Generally, retain documentation that supports your payment reporting decisions, including contracts, payment records, system exports, and correction logs.
From an expert operational standpoint, compliance is easier when you treat it like a controlled process rather than a scramble. Consider the following practices:
Set an internal checkpoint after each payout cycle or at monthly intervals to verify that contractor profiles are complete and that payment categorization aligns with your reporting approach. This prevents last-minute surprises.
You can implement a simple quality gate checklist like:
Even if you run the full review only annually, monthly checks catch mistakes earlier when they’re cheap to fix.
Use the exact legal names received from contractors, and avoid informal aliases. When you normalize data, ensure you do not introduce formatting drift that could cause mismatches.
For example, a contractor may provide “Acme Design, LLC” on the W-9, but your system might store “Acme Design LLC” (missing a comma). That small difference can matter when you are trying to match IRS expectations and avoid recipient confusion. Your safest practice is to store the name exactly as received from the W-9 and keep that value stable unless you update with an amended W-9.
If you correct recipient details or payment totals, document the reason and timing. When questions arise later, a clear audit trail saves time.
Your adjustment log can be as simple as a spreadsheet with columns like:
That log is extremely useful when you compare versions of exported data and need to explain why a total changed.
Even if Square-related processes provide strong tracking, make sure your accounting treatment and your reporting totals align. Where discrepancies exist, resolve them methodically rather than forcing totals to “fit.”
A methodical approach includes:
This alignment reduces the risk that you’ll reconcile totals to the wrong period or misapply categories.
The first thing you should do—before even thinking about generating any 1099-NEC outputs—is to build a “data map” that explains how contractor payments in your workflow become recipient-level totals in your reporting process. Many businesses skip this step and then waste time later trying to figure out where totals came from.
A data map does not need to be complicated. It should answer questions like:
Once you can answer those questions, the “Square Payroll 1099” process becomes much more manageable because you can trace totals from start to finish.
Consider building your data map with the following components:
When your data map exists, you can also train whoever helps you (bookkeeper, accountant, assistant) so the workflow is consistent year after year.
Sometimes a checklist is easier to understand if it is tied to a realistic example. The following scenarios illustrate common first-step tasks that businesses typically do early in the “Square Payroll 1099” cycle.
An agency has:
First steps:
This approach prevents the common failure mode where the agency knows total payments but discovers late that one contractor’s tax ID was missing or entered incorrectly.
A retail store hires:
First steps:
This reduces the risk of having a late-year scramble for a handful of contractors who received payments but whose tax info is missing.
An e-commerce business pays a developer for ongoing website maintenance, and sometimes there are adjustments like refunds or service credits.
First steps:
Handling adjustments early avoids the common pitfall of generating 1099 totals that do not reflect corrections.
Even though the user asked what to do first (not a full timeline), the “first step” is easier when you know roughly how the year-end process will unfold. Here is a practical timeline framework that many compliance-friendly businesses follow.
This timeline isn’t meant to replace IRS deadlines (which can vary by year and filing method), but it provides a strategy: you reduce risk by handling issues early, not late.
Accurate contractor identification is more than “having a list of names.” In 1099 reporting, it means your reported “payer-recipient relationship” is consistent and traceable and that the recipient’s tax identity matches IRS expectations.
When identifying contractors, focus on:
A practical tip: create a “recipient ID” concept internally. Even if your platform stores names, use a stable internal identifier (like contractor profile ID) so that you can map payments to the same recipient record even if the displayed name changes after a corrected W-9 is received.
Consistency reduces the likelihood of duplicate recipient records and prevents errors where payments are split across two records for the same contractor.
Aggregation errors are among the most common reasons businesses need corrections. These errors usually come from confusion about which date and which amount should be included.
While the exact basis depends on the reporting instructions and facts, you can prevent many issues by implementing consistent internal rules:
A helpful “sanity checklist” before you finalize totals:
If you do this review while you still have time to correct data, you reduce the chance of needing corrections after filing.
Your “data trail” is the set of records you can show to support your reporting decisions. Even if you are not facing an audit, a well-organized trail makes corrections and explanations easier.
Start collecting and storing:
A good practice is to store these in a folder structure by tax year and within it by contractor or by data type. For example:
This reduces the time spent searching for documents and helps maintain continuity year to year.
One of the biggest real-world challenges is that some contractors don’t provide W-9s promptly, or their info is incomplete. This isn’t unusual. The key is to have a plan for what to do first and when to escalate.
A practical “incomplete information” workflow includes:
If you “push forward” without a plan, incomplete data can create a last-minute correction cycle that is stressful and time-consuming. By handling incomplete information early, you keep the process manageable.
To make the process tangible, here are quality gate checks that you (or your bookkeeper/accountant) can run on exports before you finalize anything:
These checks do not require advanced software. They require discipline and a willingness to pause if something looks wrong.
Because the question is framed around “Square Payroll 1099,” it’s useful to explain how to think about a platform in your compliance workflow. A platform can be:
But it should not be the only thing you trust. Treat it as one component of a broader compliance system that includes your accounting records and your document archive.
A helpful principle is: trust but verify. Trust the platform for data capture and organization. Verify correctness through reconciliation and recipient-level checks.
If your platform allows corrections to recipient records, you should also ensure your workflow captures the change history or that you maintain an external adjustment log. That way, when totals change due to corrections, you can trace why.
Many businesses get stuck before they even begin the actual 1099-NEC process. Here are common pitfalls that delay the first steps and how to avoid them:
Fix: adopt onboarding/first-payment W-9 collection as a standard practice.
Fix: choose a single recipient master list and sync your other lists to it.
Fix: confirm contractor vs employee classification with a consistent approach and document the rationale.
Fix: reconcile totals, then do recipient-level checks; do not stop after tie-out.
Fix: define an adjustment rule early and apply it consistently to avoid misreported amounts.
Because 1099 reporting rules can vary based on the facts, this guide intentionally avoids claiming universal applicability or guarantees. The compliance steps should be validated against:
In addition, there are sometimes edge cases where the practical “Square Payroll 1099” workflow still helps, but the inclusion/exclusion logic may require more careful interpretation (for example, special payment types or unusual contractor arrangements). When in doubt, you should consult official guidance or a professional.
Managing “Square Payroll 1099” successfully comes down to disciplined data handling: confirm contractor classification, collect accurate tax information, reconcile payment totals by tax year, and perform a rigorous recipient-by-recipient review. When your system exports and accounting records agree—and you can explain any corrections—you significantly reduce the risk of errors and rework.
If you want, share your general situation (e.g., whether you pay independent contractors only, whether you use contractors for services, and how payouts are recorded). I can help map an appropriate checklist for your workflow while staying consistent with IRS guidance principles.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

Exploring the Retipster Club Advantage
The Retipster Club is an invaluable resource for real estate investors, offering a plethora of insights, tools, and community support to boost investing endeavors. Aimed at helping both novice and seasoned investors, the club provides educational materials, success stories, and expert strategies tailored to the ever-evolving real estate market landscape. Dive into this analysis to understand the manifold benefits the Retipster Club offers to enhance real estate success.
Navigating the Retipster Club
This article delves into the unique offerings of the Retipster Club, a community designed for individuals interested in real estate investment, providing educational resources and networking opportunities. Discover how the club supports its members through expert advice, comprehensive guides, and a robust community platform, all tailored to foster insightful and profitable investment strategies.
Pmoc Abrava: Practical Procurement and Quality Considerations
This guide explains how to approach Pmoc Abrava procurement with a quality-first, compliance-minded process. “Pmoc Abrava” is discussed as a term used in sourcing contexts, covering typical decision factors such as specification clarity, supplier capability, documentation, and handling requirements—using an objective framework for safer purchasing, risk control, and consistent performance.
Unveiling Grunig & Hunt's PR Models
This article explores the seminal work of Grunig & Hunt in developing models of public relations. The Grunig & Hunt models, fundamental to understanding PR theory, provide insight into the strategic approaches and methodologies utilized in the field. Each model offers a distinctive perspective on communication and engagement strategies, relevant to both academic discussions and practical applications.
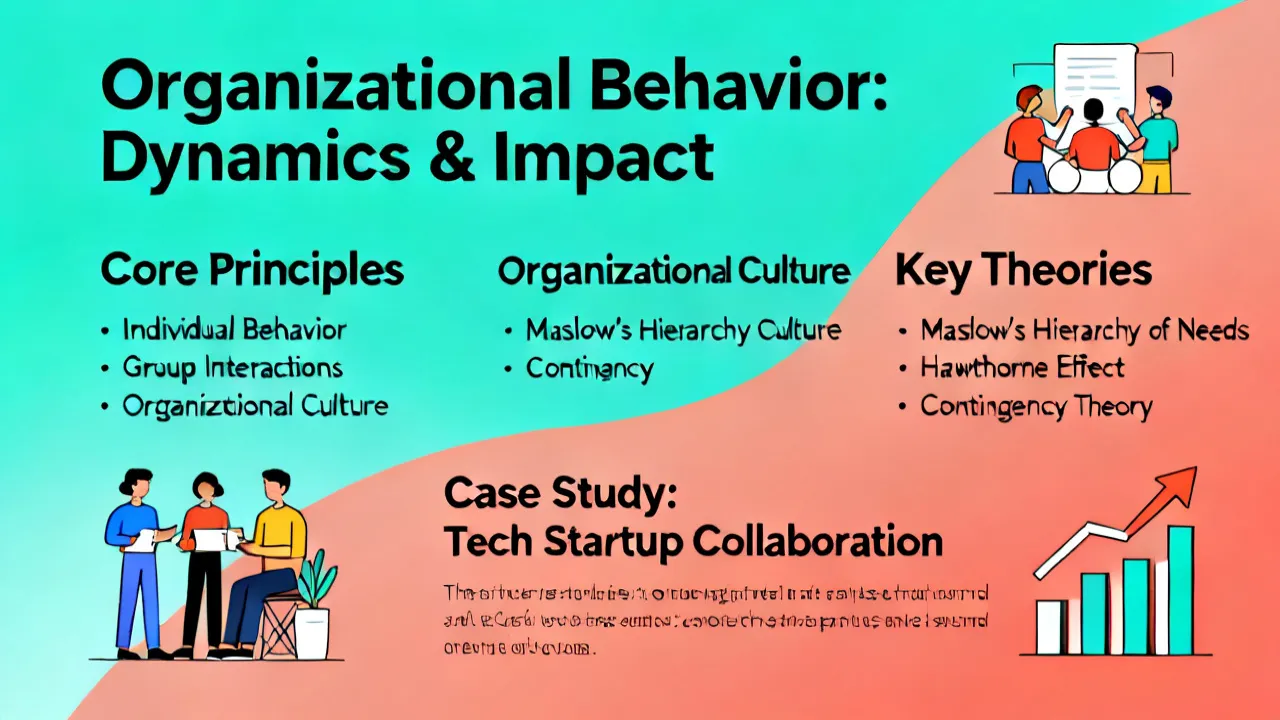
Understanding Organisational Behaviour Slideshare
This article delves into the significance of Organisational Behaviour Slideshare for both educators and professionals. Organisational Behavior is a field that examines the impact individuals, groups, and structures have on behavior within organizations, aiming to improve an organization's effectiveness. With Slideshare's platform, these insights are easily shared, promoting a collaborative learning environment.
Understanding Ltda Epp for Supplier and Compliance Decisions
Learn how “Ltda Epp” impacts supplier selection, contract structure, and compliance planning. This guide explains, in objective terms, what the label typically signals in company registration and how it can affect procurement processes, risk checks, and document readiness. It also frames practical conditions, comparison points, and decision steps to help you evaluate suppliers with clarity and consistency.
