This guide explains how to handle Square Payroll 1099 reporting with clear, compliant workflows. It provides objective context on what 1099 forms are, why independent contractor reporting matters, and how payroll systems intersect with IRS requirements. You’ll also find a practical comparison-style checklist, step-by-step conditions, and FAQs for implementation decisions.
If your organization pays independent contractors through Square Payroll, the very important starting point is understanding which workers are treated as contractors for tax purposes and how your payroll workflow should produce accurate 1099 reporting. In practice, “Square Payroll 1099” guidance is less about a single click and more about consistently classifying payees, capturing required information, and verifying the final reporting outputs before submission.
From an industry perspective, the top 1099 outcomes come from strong operational hygiene: clean payee records, accurate contractor status, correct tax forms triggered by payment types, and a documented internal review process. This is especially relevant when businesses manage multiple pay types across gigs, affordablelance services, marketing engagements, and other non-employee work arrangements.
When a company first approaches “Square Payroll 1099,” the most common mistake is to start at the end of the year. The practical reality is that compliance is created months earlier—often at onboarding, at the moment you decide whether someone is truly a contractor, and at the time you capture payee identification details that later show up on tax forms. In other words, 1099 reporting compliance is best treated as an ongoing data-quality program rather than a year-end scramble.
This article expands on what to do first, why it matters, and how to operationalize your process so that Square Payroll reports what you expect—and the IRS receives what it needs. Throughout, the focus remains on workflow design: the classification policy you use, the data governance you implement, the mapping between payment transactions and 1099 reporting outcomes, and the review steps that help prevent errors.
IRS Form 1099 series reporting generally supports tax information reporting for payments made to non-employees. While the exact form depends on the payment category, many businesses encounter “1099” in the context of contractor payments. When you use a payroll or payments platform such as Square Payroll, you typically expect the system to help compile payee information and generate the relevant tax documents based on the information you’ve provided and the payment activities recorded in your account.
However, technology doesn’t replace tax responsibility. Employers and businesses remain responsible for ensuring that the information submitted to the IRS and furnished to contractors is accurate and complete. That means classification decisions, name/address accuracy, and proper handling of tax forms must be managed with care.
It can be helpful to think of 1099 reporting as a “data contract” between your business and the IRS. The IRS uses the information to match income reported by payees and to support compliance checks. If your forms contain incorrect names, addresses, or tax IDs, you can create downstream issues for both the contractor and your organization—potentially including IRS notices and time-consuming corrections.
Even if Square Payroll automates many parts of the process, compliance still depends on: (1) whether the payees are truly in-scope for the type of 1099 you file, (2) whether you captured the right identifiers at onboarding, and (3) whether the transaction amounts included in the report correspond to what the IRS considers reportable.
In many businesses, 1099 reporting involves more than “contractor payments.” Depending on how your payments are structured and categorized, you might also encounter requirements related to other 1099 forms. While this article concentrates on the typical contractor/1099 workflow, your “first step” should be understanding which category applies to your payments and which forms your organization might need to file.
Before focusing on the mechanics of Square Payroll 1099 output, align these foundational points:
To stay compliant, you want the entire team that touches contractor payments to understand the logic behind 1099 reporting. That includes operations staff who onboard payees, finance teams who reconcile payments, and administrators who handle updates to payee details. If each role uses different assumptions about contractor status or payment categorization, errors multiply quickly.
Additionally, you should define ownership. For example, decide who is responsible for: (a) contractor classification determinations, (b) collecting and maintaining W-9 or equivalent information, (c) updating addresses, and (d) validating final report totals. Assigning responsibility is one of the simplest but most powerful compliance controls, because it turns vague “someone will check it” behavior into an accountable process.
In a real-world workflow, “Square Payroll 1099” is rarely a standalone task. Instead, it functions as part of a year-round operations loop:
Because businesses vary widely in how they hire contractors, a platform like Square Payroll is top treated as a reliable data processor—not a sole decision-maker. Your classification policy and data governance are what determine whether the generated forms are defensible.
Operationally, this means you need to design your “contractor payment lifecycle.” Consider a typical lifecycle:
When the lifecycle is managed in a consistent manner, 1099 reporting becomes a predictable output from a well-maintained data system. When it isn’t, year-end becomes an excavation project: searching for missing identifiers, determining what belongs on which form, and trying to reconcile mismatched categories.
From an accounting and controls perspective, the very effective strategy for Square Payroll 1099 compliance includes three layers:
Payee fields are the foundation of accurate 1099 reporting. Use consistent onboarding forms, require validated inputs, and maintain a change log when corrections are made. Even minor discrepancies can complicate tax matching.
In practice, “data governance” means you define what counts as complete payee data and where that data is stored. For example, you might require the contractor’s:
Data governance also means you control how updates happen. For example:
One of the operational best practices is to require contractors to submit updated information using a formal process (often a structured form), rather than relying on informal email updates. Informal updates are more prone to typographical errors, incomplete fields, or outdated information being used accidentally.
Another best practice is to implement a “missing data” report. As contractors are onboarded, you can monitor which payees are missing required identifiers. Catching missing fields during the year is vastly easier than trying to repair them after the tax year closes.
Decide what transactions should contribute to the 1099-related totals for your workflow. This is where misinterpretation commonly occurs—especially when businesses have mixed payment categories or multiple types of services.
Transaction-to-form mapping answers the question: “Which payments are considered reportable under the 1099 forms we file?” Even if Square Payroll provides reports, you still need to understand how the platform defines and categorizes payments.
Common mapping questions include:
To strengthen compliance, document your mapping rules. Documentation can be simple, such as a one-page internal policy. But the documentation is essential because it creates a consistent reference that finance, operations, and administrators can use when questions arise.
Even if your business uses a standardized workflow, you can still have edge cases. For instance, some contractors might receive bonuses, late fees, or reimbursement for expenses. Depending on how those are recorded, they may or may not be treated as reportable payments. A documented mapping rule prevents ad-hoc decisions.
Additionally, you should validate that the categories your team uses internally correspond to how Square Payroll generates the 1099 totals. For example, if your team tags one type of work “marketing” and expects it to be treated a certain way for reporting, you should confirm that the platform mapping aligns with that expectation. Otherwise, you can be including amounts that should not be included (or excluding amounts that should be included).
Before filing, perform a reconciliation between internal totals and the totals shown in your reporting outputs. Assign responsibility for review so there is a clear owner for corrections and a documented audit trail of changes.
Review and sign-off procedures are where many compliance programs either succeed or fail. The platform output can be correct or incorrect depending on the quality of upstream data. Reconciliation is your final defense.
A strong review process typically includes:
Sign-off can be structured as a formal approval step or a ticket-based workflow where a reviewer must mark the forms “approved” before submission. The key is that there should be evidence that someone actually performed the review.
Some organizations implement a two-step review for higher risk roles. For example, an administrator might generate drafts and handle corrections, while a finance lead might reconcile totals and approve submission.
The table below compares practical approaches to managing Square Payroll 1099 reporting workflows. It is designed as an operational supplement; the top option depends on staffing, contractor volume, and how standardized your internal processes are.
| Approach | Top for | Core requirement | Primary risk if skipped |
|---|---|---|---|
| Platform-driven reporting with internal reconciliation | Businesses using Square Payroll as the primary payee/payment system | Consistent payee onboarding and verified outputs before filing | Totals mismatch and avoidable corrections later |
| Hybrid workflow (platform + spreadsheet control logs) | Mid-size teams with higher contractor activity and multiple payment categories | Documented mapping rules from transactions to reporting categories | Incorrect inclusion/exclusion of amounts |
| Manual oversight focused on classification and payee data | Organizations with complex contractor relationships or frequent onboarding changes | Clear classification policy and rigorous payee data checks | Misreporting due to incomplete or incorrect payee identifiers |
When choosing your approach, consider your internal “failure modes.” For example, if errors frequently occur because payee data is incomplete, then focus on onboarding and data completeness controls. If errors occur because payments are categorized inconsistently, then focus on mapping rules and transaction tagging discipline.
You can also use the comparison table as a diagnostic tool. If you are currently operating with only a platform-generated draft and no internal reconciliation, then you’re likely exposed to the highest risk scenario for Totals mismatch. If you already have reconciliation but still face rework due to missing identifiers, then your immediate improvement should target onboarding completeness rather than end-of-year totals.
Use the checklist below to structure your year-end and near-year-round readiness. These are operational conditions commonly needed for dependable 1099 reporting outcomes. Always confirm rules and deadlines with authoritative IRS materials or qualified tax professionals.
Condition/requirement: Your classification decisions should be consistent with applicable tax guidance and the factual relationship you have with each worker. Maintain internal documentation supporting classification determinations.
This is the true “first step” because it determines whether 1099 reporting is even relevant for a given payee. Before you worry about Square Payroll output, you need a classification policy that your organization applies consistently.
In many businesses, classification can be complicated by factors such as:
Even if the IRS classification rules are outside the scope of this article, the operational takeaway is clear: do not treat classification as a one-time checkbox during onboarding. Establish a policy, train relevant staff, and maintain documentation that supports your decisions.
Documenting classification decisions can include internal memos, onboarding checklists, contract language, and records showing how work was actually performed. That documentation may not be required to file a form, but it can become important if questions arise later.
From a compliance operations standpoint, it is also useful to categorize your contractor types. For example, define whether you treat certain payees as “one-off project contractors” versus “ongoing advisory contractors.” Even though both may be contractors, treating them as different categories can help you apply consistent data and reporting logic.
Condition/requirement: Verify that each contractor’s name and address align with the records you will use for reporting. Resolve known discrepancies early rather than at submission time.
Accurate payee identity information typically includes legal name formatting and current address. A common issue is that contractors provide information in a way that doesn’t exactly match IRS records. This can happen due to abbreviations, punctuation differences, or different name orderings.
Operationally, you can reduce identity errors by implementing:
If you have a contractor who has moved mid-year, the address used on the tax form should reflect the correct current address at the time of reporting. The practical question your organization should answer is: “Which address do we use if an update happens after the payment year ends?” Your internal process should define how to handle that timing.
Another important concept is the difference between display name and legal name. Display names may be shorter and easier for internal use, but tax reporting should use the legal name that matches tax documentation. If your Square Payroll setup uses both fields, confirm you’re sourcing the correct field for tax form generation.
Condition/requirement: Confirm that amounts recorded in Square Payroll reflect the services or payment categories intended for 1099 reporting in your workflow. Where applicable, establish a rule for borderline cases (e.g., refunds, adjustments, or non-reportable items).
This step is often where operational teams run into “it looked right in the reports, but the forms came out differently” issues. That mismatch typically occurs when the platform categorizes transactions differently than your internal expectations.
To align payments to reporting, you should:
For example, consider a scenario where a contractor invoice is partially refunded due to an error in deliverables. If your team records the refund as a separate payment entry, you might inadvertently inflate gross totals unless the platform netting logic matches your intended treatment. By defining rules upfront—such as netting refunds against original amounts or excluding certain adjustment types—you reduce the chance of incorrect reporting.
Similarly, reimbursements may be treated differently than compensation for services. If reimbursements are recorded in the same payment workflow, you need to ensure they don’t contaminate totals intended for reporting. This might require a separate reimbursement workflow or a specific tagging approach within Square Payroll.
Finally, make sure that the reporting period is correct. Payments near the end of the year can be recorded with timestamps that might affect whether they appear in the current tax year’s reporting output. A review process should flag unusual timing issues and ensure the year-to-date totals align with internal accounting records.
Condition/requirement: Run any available previews or reporting summaries before formal filing. Compare totals to internal transaction records and investigate outliers.
Most businesses underestimate how valuable previews are. A preview gives you an opportunity to correct problems before you submit forms to the IRS and furnish them to contractors.
A best-practice review package might include:
When reviewing, focus on both quantity and quality. Quantity issues involve whether the right number of contractors is included. Quality issues involve whether the data is correct and whether amounts align to expected reportable categories.
It’s also useful to document what you find and what you change. If you later need to explain why a correction was made, documented evidence helps. Even if you never face an IRS inquiry, documentation improves internal confidence and consistency.
Condition/requirement: Provide time for contractors to correct payee information if your process supports it. Keep a record of changes and the reason for each correction.
Corrections are not a failure. Corrections are part of a healthy compliance workflow—when handled early. A correction window provides time to gather updated information and to re-run previews until the output is stable and accurate.
Internal correction windows can be structured in two phases:
To implement this effectively, define the communication process. For example:
Also define what happens if the contractor does not respond. Your process should include a decision: Do you proceed with existing data, request additional documentation, or flag the contractor for manual review? The decision should be consistent with compliance strategy and tax professional guidance.
Keep a correction log. The correction log should include:
This log becomes an audit trail. While it might not be submitted to any agency, it provides internal reliability and reduces errors during the correction process itself.
Condition/requirement: Submit tax forms and furnish copies to payees based on current IRS requirements and your filing method. Ensure formatting and submission specs are followed for electronic or paper filing.
Deadlines for information returns and furnishing copies to contractors can vary by form type and filing method. If your workflow is fully automated, the system might show submission status or draft-ready forms—but you still need to ensure that you use the correct filing method and meet the actual IRS deadline.
To avoid last-minute surprises, build a calendar. A compliance calendar should include:
Also confirm your chosen method of filing. If you file electronically, you may need to confirm system requirements, file formats, and submission confirmations. If you file by paper, your process needs to include address verification for mailing and proof of mailing where applicable.
Furnishing copies to contractors introduces another operational layer. You should ensure that the method of furnishing (electronic vs. paper) is consistent, trackable, and meets requirements.
Because 1099 requirements can differ by payment type and classification, businesses should rely on authoritative IRS guidance and current instructions. The IRS provides background on information returns and the responsibilities of filers through official publications and instructions associated with each form type. For foundational context, review:
Reliable sources: IRS official publications and form instructions (e.g., IRS.gov pages for Form 1099 series and instructions).
Even though your platform may handle data formatting and generate forms, your compliance remains anchored in understanding the IRS instructions. That includes knowing which payments are reportable, what thresholds might apply, and how to handle common issues like corrected information returns.
Operationally, you can keep a folder or repository with the relevant IRS instructions for each form type you plan to file. Assign responsibility to update that repository each year. The reason is simple: rules and instructions can change, and your workflow should reflect the current year’s guidance.
Across finance and operations teams, several pitfalls show up repeatedly. Treat these as guardrails when you design your process.
Many teams discover too late that payee details were incomplete or transaction categories were inconsistent during the year. Instead, set up a routine for periodic validation—especially after onboarding new contractors and after changes to payment types.
To fix this, treat 1099 readiness as a series of checkpoints. For example:
This approach reduces the chance that the only visibility into a problem occurs at year-end. It also reduces contractor corrections at the end of the year, because issues are discovered earlier.
Even with strong platform support, internal totals should be checked. A short reconciliation step reduces costly corrections after submission.
Some teams assume that if a platform generates the 1099 output correctly, then their job is done. But platforms are not omniscient; they operate based on inputs. If inputs are wrong or categorized inconsistently, the output will be wrong too.
Reconciliation can be lightweight but should exist. A common practical method is:
Even if the amounts match overall, reconciliation by contractor can uncover data issues like a contractor being excluded or a name/address mis-match causing separate entries.
Square Payroll 1099 forms reflect your reporting choices and the data you provide. If there is ever a question about the underlying classification, documented decisions and consistent application of your policy are critical.
Documentation helps you answer questions such as: Why did you treat this person as a contractor? Why did you include them in the reporting? How did your workflow decide what form applies?
From an operational standpoint, create a “classification evidence” package for contractors. It might not need to be extensive for each person, but it should exist and be accessible. For example:
If you frequently hire contractors, standardized documentation reduces the burden on staff and improves consistency in how classification determinations are recorded.
If a contractor’s legal name or address needs correction, you need a predictable workflow for receiving and applying updates. Build a process before deadlines create urgency.
Contractors are often busy, and they may not respond quickly to compliance requests. Without a proactive workflow, you might scramble to fix identity information too late. That can lead to filings using outdated information and increased risk of errors.
Proactive communication can be simple. For example:
Also clarify what constitutes “legal name” and “address.” Contractors may submit an address they use for correspondence but not for tax records. Your process should encourage them to use the address intended for tax reporting.
Your organization’s scale affects how you should structure the process around Square Payroll 1099 reporting.
Small businesses might only pay a handful of contractors. That means you can focus on simplicity. Still, even small businesses can make big mistakes if they treat onboarding informally or if they skip data-quality checks. A single missing identifier can cause rework and corrected filings.
Mid-size organizations often have higher contractor volume and multiple internal teams. In those settings, the biggest risk is inconsistency. One team might categorize payments correctly while another team uses a different category structure. A mapping document and periodic audits address that risk.
Multi-department teams create another operational challenge: handoffs. If the person who onboarded a contractor is not the person who reconciles totals, communication breakdowns can occur. A structured workflow, clear ownership, and documented review steps solve this.
Regardless of size, the same principle applies: compliance is created at the source of data and reinforced through review.
In practical terms, it refers to using Square Payroll (or associated reporting functions) to produce tax information returns related to contractor payments, based on the payee and payment data recorded in your system. Your organization still must ensure classifications and reported details meet applicable IRS requirements.
Practically, this means that the outputs you see are only as accurate as the data and rules that feed them. A correct “Square Payroll 1099” outcome is therefore a combination of correct inputs (classification and payee information) and correct operational process (mapping and reconciliation).
Not necessarily. Whether a form is required depends on the contractor’s classification, the type of payments made, and applicable IRS rules for information returns. Review the instructions for the relevant 1099 form and confirm your obligations based on your payment categories.
Your first compliance step is not “to generate forms for everyone,” but to understand which payments are reportable and which payees are in scope based on facts and circumstances. Once you establish in-scope rules, your workflow can apply them consistently.
Use a controlled onboarding process that captures legal name and address consistently, re-check records when changes occur, and avoid relying on informal “display names.” Run a review step before filing to spot mismatches early.
It helps to treat name and address fields like “high-precision” data. Avoid abbreviations unless the IRS-reported name uses abbreviations. Maintain consistency in punctuation and spacing where possible.
Also, consider training internal staff who collect information. People often think they are entering the right data, but small transcription differences can lead to mismatches. A short training session can prevent many errors.
Corrective steps depend on the nature of the error and the form type. Typically, you may need to file corrected information returns and furnish corrected copies to contractors where required. Follow the IRS instructions for correction procedures or consult a qualified tax professional.
Operationally, you should ensure your internal correction process is capable of producing revised outputs quickly. That means your system should allow you to update payee details and regenerate forms, and your documentation should track what was corrected and when.
Also, keep in mind that corrections can trigger further contractor communication needs. If the contractor relies on the form for their own tax filing, they may need a revised copy. Plan for that as part of your correction workflow.
Platforms can help compile and generate reporting outputs, but compliance responsibility remains with the filer. Ensure your internal controls, classification decisions, and payee data governance are strong enough to support the forms you submit.
It’s useful to think of Square Payroll as a tool for data processing and form generation, not as the decision-maker for classification or reporting eligibility. Your organization must determine what should be reported and must ensure the inputs are accurate.
To strengthen your compliance posture, keep evidence of your review steps. Even if the platform documentation exists, internal evidence of your reconciliation and corrections is what supports your responsibility as the filer.
Yes. Information return deadlines vary by form type and filing method, and the rules can change over time. Plan your workflow calendar around the latest IRS deadlines and the time required for payee data review and corrections.
Deadlines are not only submission dates. They include internal deadlines for data cleanup, contractor response deadlines for updates, and buffer time for resolving anomalies. Build realistic timelines rather than assuming you will correct issues instantly on the submission week.
To make “what to do first” more concrete, here is an expanded set of first actions your organization can take immediately—before you generate any 1099 drafts. These actions align with compliance best practices: classification, data completeness, mapping rules, and review accountability.
Document how you decide whether a worker is a contractor. Ensure that people who onboard contractors can apply this policy consistently. If you already have a policy, review it for internal consistency and confirm it’s being used in practice.
Even if you never file a corrected return, a classification policy helps ensure you’re not unintentionally building compliance risk by reporting forms for people who are actually employees (or vice versa).
Define exactly what information you must collect for each contractor in your workflow. Your list should mirror what you need for tax form generation and should include a method for capturing updates.
For example, your onboarding checklist might include:
Make this checklist standard. Avoid improvisation. Each improvisation becomes a potential inconsistency.
Before you rely on any platform mapping, document your internal mapping rules. Determine what categories in Square Payroll (or your upstream invoice/payment process) correspond to reportable totals for the 1099 forms you intend to file.
Write down:
This mapping document can be used as a training reference and as a troubleshooting guide when totals don’t match.
Instead of waiting for year-end, run a monthly check for data completeness and transaction mapping consistency. This might be as simple as reviewing a report of contractors lacking required identifiers and scanning for unusual transaction patterns.
For example, you can look for:
Monthly checks reduce the probability that you will discover problems for the first time in the last quarter.
Design the reconciliation step before you need it. Identify the person responsible for reconciliation, define where the internal totals live, and decide how you will investigate differences.
Reconciliation routine should include:
Once this routine is standardized, you reduce decision-making pressure and improve consistency year over year.
Decide how you will handle contractor updates to name/address/tax identifiers. Set communication templates and define a timeline.
When contractors know what to expect and when to respond, you can avoid last-minute corrections and stabilize the reporting cycle.
Maintain a folder or internal record that includes the drafts you generated, the reconciliation notes, and the final submission status. This is not about bureaucracy; it’s about ensuring you can answer questions later if something appears off.
This evidence file can include:
If your organization ever needs to respond to an issue, this evidence file can speed up investigation.
The “first step” to stay compliant with Square Payroll 1099 reporting is not to click generate forms. It is to establish compliance-ready inputs and workflow controls: confirm contractor classification policy, ensure payee identity data quality, document payment-to-report mapping rules, and implement internal review routines before you rely on the platform output.
Once those elements are in place, Square Payroll becomes a powerful tool for generating forms based on accurate data. Without them, the platform can faithfully generate incorrect forms—creating avoidable correction work and compliance risk.
Square Payroll 1099 reporting works top when it’s treated as a structured operational workflow: accurate payee records, consistent transaction categorization, reconciliation before submission, and documentation of classification decisions. By applying a controls-first approach, you can reduce avoidable errors, support clearer contractor communication, and maintain confidence in your reporting cycle.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

Exploring the Retipster Club Advantage
The Retipster Club is an invaluable resource for real estate investors, offering a plethora of insights, tools, and community support to boost investing endeavors. Aimed at helping both novice and seasoned investors, the club provides educational materials, success stories, and expert strategies tailored to the ever-evolving real estate market landscape. Dive into this analysis to understand the manifold benefits the Retipster Club offers to enhance real estate success.
Navigating the Retipster Club
This article delves into the unique offerings of the Retipster Club, a community designed for individuals interested in real estate investment, providing educational resources and networking opportunities. Discover how the club supports its members through expert advice, comprehensive guides, and a robust community platform, all tailored to foster insightful and profitable investment strategies.
Pmoc Abrava: Practical Procurement and Quality Considerations
This guide explains how to approach Pmoc Abrava procurement with a quality-first, compliance-minded process. “Pmoc Abrava” is discussed as a term used in sourcing contexts, covering typical decision factors such as specification clarity, supplier capability, documentation, and handling requirements—using an objective framework for safer purchasing, risk control, and consistent performance.
Unveiling Grunig & Hunt's PR Models
This article explores the seminal work of Grunig & Hunt in developing models of public relations. The Grunig & Hunt models, fundamental to understanding PR theory, provide insight into the strategic approaches and methodologies utilized in the field. Each model offers a distinctive perspective on communication and engagement strategies, relevant to both academic discussions and practical applications.
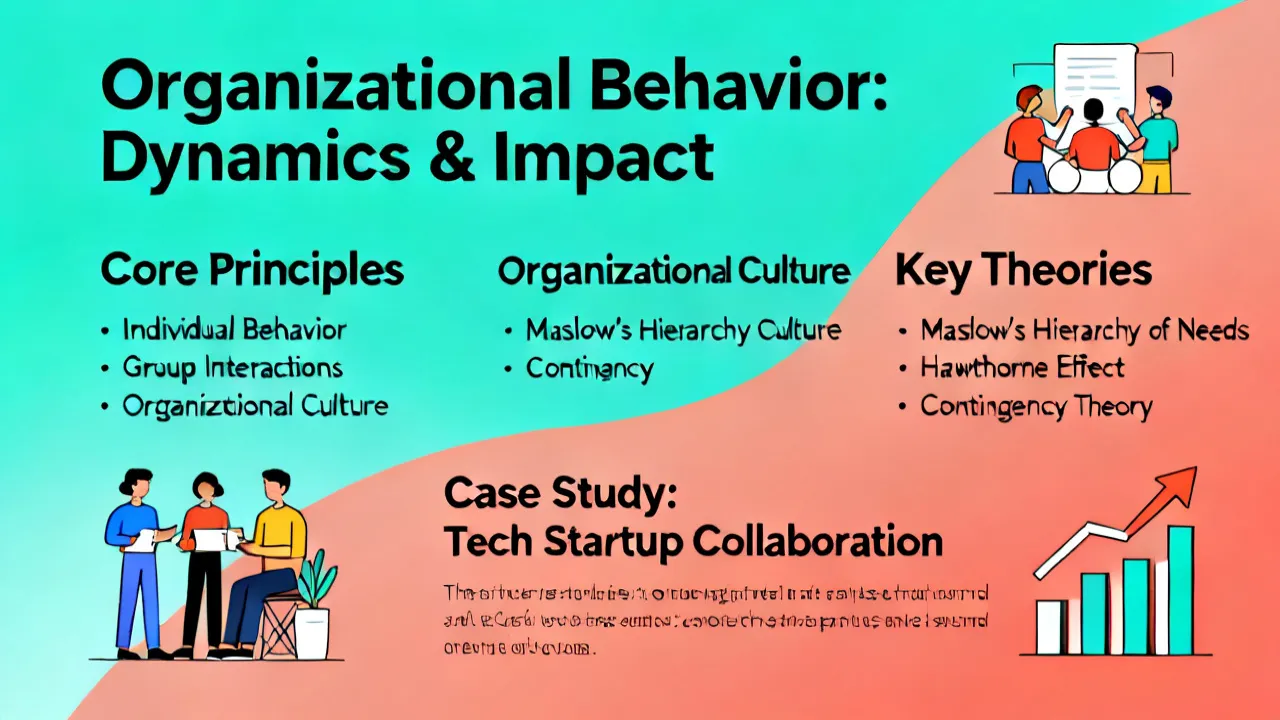
Understanding Organisational Behaviour Slideshare
This article delves into the significance of Organisational Behaviour Slideshare for both educators and professionals. Organisational Behavior is a field that examines the impact individuals, groups, and structures have on behavior within organizations, aiming to improve an organization's effectiveness. With Slideshare's platform, these insights are easily shared, promoting a collaborative learning environment.
Understanding Ltda Epp for Supplier and Compliance Decisions
Learn how “Ltda Epp” impacts supplier selection, contract structure, and compliance planning. This guide explains, in objective terms, what the label typically signals in company registration and how it can affect procurement processes, risk checks, and document readiness. It also frames practical conditions, comparison points, and decision steps to help you evaluate suppliers with clarity and consistency.
