This guide explains how to manage 1099 contractor reporting when using Square Payroll and related workflows. It provides objective context on 1099 filings, contractor classification considerations, and common compliance checkpoints. Readers will gain practical, expert-oriented guidance on aligning payroll records, contractor identifiers, and reporting timelines for accurate Form 1099 workflows.
When businesses use Square Payroll 1099 workflows, the core compliance objective is consistency: the earnings totals derived from payroll/payments records must match the contractor tax reporting details used for Form 1099 submissions. From an industry-expert perspective, accuracy is less about “clicking the right setting” and more about establishing a disciplined system for (1) contractor classification, (2) tax form collection (notably W-9 data), and (3) reconciliation of payment totals and identities before filing. If the workflow is built correctly, the output becomes reliable. If it is built loosely, corrections become likely—often late in the year or during filing season.
In practice, Square Payroll 1099 is often discussed alongside broader 1099 processes because the underlying challenge is the same: translating payroll activity and contractor payments into reportable contractor totals—using correct contractor identifiers and preserving an audit trail suitable for tax review. That translation must also incorporate timing logic and exclusions. In other words, it is not only a reporting task; it is a data governance and tax compliance task.
The phrase Square Payroll 1099 is used loosely in many organizations to describe how payroll-related systems and workflows intersect with 1099 contractor reporting. Depending on how a business operates, the “Square Payroll 1099” workflow can include one or more of the following:
Because 1099 reporting rules are tax-specific and classification-dependent, the safest approach is to treat the process as a compliance workflow rather than a purely operational task. That mindset reduces avoidable reporting errors, improves internal defensibility, and helps a business respond if IRS questions arise or if a contractor disputes a reported amount.
In the United States, Form 1099 series reporting helps the IRS and contractors track certain types of non-employee compensation. While employees typically receive W-2 wage reporting, many independent contractors may receive Form 1099-NEC for certain payments. The legal distinction between “employee” and “independent contractor” is not determined by payroll software alone; it is determined by the facts and circumstances under applicable law.
For authoritative guidance, small businesses and payroll administrators commonly refer to the IRS’s official resources, including IRS instructions for Form 1099-NEC and IRS guidance on worker classification. (See IRS “Instructions for Form 1099-NEC” and IRS worker classification materials.) In practice, compliance teams use these resources to define:
Even when a business uses a payroll platform to streamline reporting, it still must interpret the IRS rules correctly and apply them consistently across its workforce.
Before focusing on configuration details, confirm these essentials. They are the most consequential for the accuracy of any Square Payroll 1099 workflow. Think of these as the “base layer.” If the base is unstable, the top layer—numbers that look correct—can still be wrong.
If any of these elements are weak, downstream reporting—whether through a payroll system, a bookkeeping pipeline, or an accountant’s reconciliation—becomes significantly more error-prone. The best way to avoid “mystery mismatches” is to lock down these essentials early and continuously.
From consulting work with accounting and operations teams, the same patterns tend to appear across industries. These root causes are often predictable and preventable if the workflow is designed with checks and data discipline.
The goal with a Square Payroll 1099-oriented process is to reduce these root causes through workflow design—not only through end-of-year corrections. A process that catches issues early is dramatically less stressful than one that tries to “repair everything” near year-end.
Below is a practical workflow you can adapt. It is written from a compliance-first viewpoint and aims to minimize avoidable errors. The core idea is to design a pipeline where each stage produces outputs that feed the next stage, with quality checks at each handoff.
Define a classification intake step before you add a worker to any payroll or contractor payment flow. Even if you use automated tools, you still need an internal approval gate. Keep documentation that supports your classification decision. The purpose of this step is not only to “label” workers; it is to make your reporting position defensible.
Condition: do not treat “software status” as proof of legal classification. Use the facts and circumstances approach recognized by the IRS and applicable regulations. A common mistake is assuming that if a contractor is set up as a contractor in the payroll system, the IRS would necessarily agree. That is not how worker classification works.
Practical suggestions that often help teams:
Ensure you have a current W-9 for each contractor. Verify that the contractor’s legal name and Taxpayer Identification Number (TIN) are correct and consistent with the IRS records you expect. Store W-9 updates when they occur. Many 1099 issues happen because onboarding occurs months (or years) before the business has meaningful payment totals—and updates are not requested or verified again before year-end.
Practical note: many businesses collect W-9s at onboarding, then confirm critical fields during the quarter when payment activity begins to accumulate. This reduces the risk of outdated TINs and avoids “discovering the problem at year-end.”
In addition to simply collecting W-9s, build a validation routine. Validation can include:
Also, have a defined process for missing or incorrect W-9s. Your process should specify: who follows up, when, and what actions are taken if the W-9 remains missing.
In a real operational environment, payments can include expenses, reimbursements, bonuses, credit card payouts, marketing fees, or other amounts that may not be treated the same way for 1099 reporting. Design your workflow so reportable contractor amounts are identifiable and extracted consistently.
If your process mixes categories, you will eventually face a “cleanup” stage that is slower and more error-prone. The cleanup phase often generates rework and may require multiple iterations of contractor contact and record correction.
To prevent category mixing, many mature organizations do the following:
This category separation creates a direct line from operational records to compliance totals.
Create a reconciliation schedule. For example, you can reconcile totals for each contractor for the reporting year using three sources:
This step catches timing drift, missing invoices, miskeyed amounts, or payee mismatches earlier—when corrections are manageable. A reconciliation checkpoint also helps you detect data pipeline issues such as incomplete exports, duplicate contractor records, or incorrectly categorized payments.
When designing reconciliation, define what “reconciled” means. For example, you may aim to reconcile at the contractor level:
Then verify that the payee identity fields (legal name and TIN) align across systems.
Before submitting to the IRS, confirm contractor totals and contractor identity fields. If a correction is needed, having a documented reconciliation reduces rework. The “corrections readiness” step should include:
Industry reality: corrections are not uncommon, but a mature workflow reduces both the frequency and the severity of corrective actions. If errors are detected earlier, the business has time to correct before final filing, and the contractor is less likely to be surprised by an IRS mismatch.
For compliance resilience, preserve:
This supports internal review and can assist if a question arises from an internal audit, the contractor, or a tax authority. When documentation exists, it reduces the risk of “knowledge dependency” on a single individual who understands the process only informally.
Many organizations treat 1099 preparation like a seasonal event. That approach often fails when payment volumes are high or when staff changes occur. Instead, implement controls throughout the year. Ongoing controls can include:
These controls do not need to be complex. They need to be consistent and measurable. The organization should be able to answer: “Are we trending toward accuracy?” Not merely “Did we survive filing season?”
Contractors change over time. They may update legal business names, change addresses, or provide a different TIN due to restructuring. These changes can create compliance risk if they are applied inconsistently across the payroll/payee system and the accounting ledger.
A controlled identity change process should define:
Without this process, you may end up reporting payments under an old name/TIN combination or duplicating contractors due to record splits.
The following supplement provides a structured comparison and checklist-style guide. It is designed to complement the main workflow rather than replace professional tax advice. A strong workflow uses both: operational steps and compliance checklists.
| Component | What to verify | Why it matters for 1099 | Conditions / requirements |
|---|---|---|---|
| Worker classification | Facts supporting employee vs. contractor status | Determines whether 1099 reporting is applicable | Use applicable IRS and legal criteria; document the decision process |
| W-9 / contractor identity | Legal name, TIN, and address consistency | Reduces filing rejections and correction needs | Maintain updated records; resolve mismatches prior to year-end totals |
| Payment categorization | Which payments are treated as reportable compensation | Prevents overreporting or underreporting | Apply a consistent internal policy for reportable vs. non-reportable amounts |
| Reconciliation logic | Date cutoffs and total computation method | Ensures numbers match across systems | Document your cutoff approach; reconcile before filing |
| Record retention | Exports, reports, and supporting documentation | Supports audit readiness and dispute resolution | Keep records per applicable retention practices and policies |
| Corrections handling | Process to identify errors and issue corrections | Reduces penalties and contractor confusion | Define approval steps, contractor outreach steps, and revision triggers |
| Backup withholding awareness | Rules for when backup withholding may apply | May impact reporting and contractor payment treatment | Monitor missing/incorrect TIN scenarios and follow IRS instructions |
Sources (official / reliable): IRS instructions for Form 1099-NEC and related IRS guidance on worker classification and backup withholding. For the very current requirements, always consult the latest IRS instructions and publications on the IRS website. Since tax requirements can change year to year, a workflow should include a step for updating policies based on the latest IRS guidance for the relevant filing year.
In many organizations, the 1099 task becomes a scramble because payroll and accounts payable data weren’t designed to be report-ready. If your team is using Square Payroll 1099 workflows, aim to make data readiness a continuous discipline. Data readiness means that by the time you begin final tax reporting, the data is already shaped the way reporting needs it.
Key elements of data readiness include:
This is the operational equivalent of building a clear chain of custody for financial reporting data. It ensures that when something does not reconcile, you know where it broke: onboarding, categorization, payment posting, export, or reconciliation.
To build a reliable workflow, it helps to view 1099 reporting as a mapping exercise. Each operational event (onboarding, service delivery, invoice submission, payment, adjustment, W-9 update) corresponds to one or more fields in the final 1099 record.
When teams succeed with Square Payroll 1099 workflows, they define a mapping such as:
Once this mapping is defined, you can build checks that confirm each mapping step remains intact as systems evolve. Without mapping clarity, teams often rely on “tribal knowledge,” which breaks when staffing changes or when system upgrades occur.
Discrepancies between payroll outputs and accounting ledger totals frequently trace back to differences in timing, categorization, and payment reversals. To reconcile effectively, it helps to know the common reconciliation patterns.
Practical techniques that teams use include:
When done properly, reconciliation becomes a repeatable, low-friction process rather than a one-time “panic event.”
Real businesses have edge cases. Mature Square Payroll 1099 workflows anticipate them and provide procedures for them. Below are common edge cases that require explicit handling to avoid filing errors.
Sometimes contractors are entered twice due to changes in name, imports, or onboarding errors. If the reporting process aggregates payments by contractor ID and the contractor exists under two IDs, payments may be split across two 1099 forms or omitted from one record entirely. A simple mitigation is to enforce a “unique payee identity” check during onboarding and during quarterly reviews.
If a contractor has not provided a W-9, you may face reporting and compliance complications. The workflow should define:
Also, consider backup withholding implications depending on circumstances. The best approach is to consult the relevant IRS guidance and maintain a documented policy.
Contractor invoices often combine professional fees and reimbursable expenses (mileage, supplies, lodging). If mixed amounts are coded incorrectly as reportable compensation, you may overreport. A robust workflow requires invoice-level categorization or line-item tagging that clearly separates reportable and non-reportable items.
Some payments occur near year-end and can be interpreted differently depending on whether you use service dates, invoice dates, or payout dates. The workflow should define the consistent rule and include cut-off testing before final totals are generated. When the cutoff rule is consistent and documented, you reduce confusion and prevent late-year surprises.
Manual adjustments can correct errors, but they can also create hidden risks. The workflow should require that manual adjustments are:
This ensures that manual adjustments do not become an uncontrolled variable.
Contractor tax data (including TIN information) is sensitive. If your organization uses a payroll platform and exports reports for tax preparation, you must ensure access controls and encryption practices are in place, consistent with internal security standards.
Practical security measures often include:
Security matters for compliance and for operational risk. A breach or data leak can create serious downstream consequences.
Even the best technology fails when responsibility is unclear. A mature Square Payroll 1099 workflow defines roles across finance, operations, and tax preparation support. Consider assigning responsibilities such as:
Clarifying ownership reduces gaps and duplication. It also supports internal review because the workflow outputs can be tied to accountable owners.
It generally refers to using payroll-related workflows (and the resulting payment records) to support contractor 1099 reporting. The precise approach depends on how your business records contractor payments and how you categorize those payments for IRS reporting. In some businesses, it may mean producing data exports for tax preparation; in others, it may involve internal reconciliation that bridges payroll, accounting, and contractor documentation.
No. Whether a 1099 applies depends on the type of payment and other IRS criteria, including worker classification and reporting thresholds. The correct form and reporting requirements should follow the official IRS instructions for the relevant tax year and payment type. A good workflow includes an internal decision tree or policy so staff understand what payments are eligible for 1099 reporting and which should be excluded.
Very important. Name/TIN mismatches are a frequent driver of filing corrections. Collect W-9 information early, validate key fields when feasible, and keep it updated when contractors provide new information. Additionally, ensure that contractor identity fields used for payments and reporting are consistent with the W-9, not just “close enough.”
Common reasons include date cutoffs, payment categorization differences, and timing differences between payroll entries and invoice posting. A reconciliation checkpoint—using documented logic—helps identify the cause before filing. Differences can also arise from refunds/reversals, duplicate payee records, or manual adjustments that were applied in one system but not mirrored in the other.
They can, but manual changes create risk if they are not documented and supported. A better approach is to correct upstream data issues and apply adjustments with traceability, clear rationale, and appropriate review. If you must adjust, treat it like a controlled change: require documentation, confirm its impact on reportable totals, and ensure it does not break reconciliation with accounting records.
Stop the filing process for the affected contractor, verify the correct contractor identity and reportable amount basis, update records, and re-run reconciliation. Keep a short audit note describing what changed and why. If the error affects multiple contractors (for example, an export mapping error), expand the check and validate the broader dataset.
Software can help with data management and reporting preparation, but it does not replace legal determination of worker classification or compliance with IRS rules. Always treat software output as a record to review, not as an automatic determination of tax outcomes. Your workflow should incorporate human review or at least automated checks that reflect IRS guidance and internal policy.
Use the IRS’s official Form 1099-NEC instructions, IRS guidance on worker classification, and related IRS publications for backup withholding and reporting rules. For anything complex, consult a qualified tax professional. Also, treat year-to-year instruction updates as part of operational compliance; build a process for reviewing changes when the IRS releases updated guidance.
A mature Square Payroll 1099 workflow is built on governance (classification), data accuracy (W-9 readiness), and reconciliation discipline (period cutoffs and payment categorization). Instead of waiting until filing season, teams should make compliance a steady operational practice with ongoing data readiness checks, clear ownership, and documented processes.
The result is fewer corrections, clearer audit trails, and greater confidence that contractor reporting matches the underlying record of payments. When your organization can explain how totals were computed, how identities were verified, and how timing decisions were applied, you reduce both risk and stress—and you create a system that can adapt as volumes, staff, and systems change.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

Exploring the Retipster Club Advantage
The Retipster Club is an invaluable resource for real estate investors, offering a plethora of insights, tools, and community support to boost investing endeavors. Aimed at helping both novice and seasoned investors, the club provides educational materials, success stories, and expert strategies tailored to the ever-evolving real estate market landscape. Dive into this analysis to understand the manifold benefits the Retipster Club offers to enhance real estate success.
Navigating the Retipster Club
This article delves into the unique offerings of the Retipster Club, a community designed for individuals interested in real estate investment, providing educational resources and networking opportunities. Discover how the club supports its members through expert advice, comprehensive guides, and a robust community platform, all tailored to foster insightful and profitable investment strategies.
Pmoc Abrava: Practical Procurement and Quality Considerations
This guide explains how to approach Pmoc Abrava procurement with a quality-first, compliance-minded process. “Pmoc Abrava” is discussed as a term used in sourcing contexts, covering typical decision factors such as specification clarity, supplier capability, documentation, and handling requirements—using an objective framework for safer purchasing, risk control, and consistent performance.
Unveiling Grunig & Hunt's PR Models
This article explores the seminal work of Grunig & Hunt in developing models of public relations. The Grunig & Hunt models, fundamental to understanding PR theory, provide insight into the strategic approaches and methodologies utilized in the field. Each model offers a distinctive perspective on communication and engagement strategies, relevant to both academic discussions and practical applications.
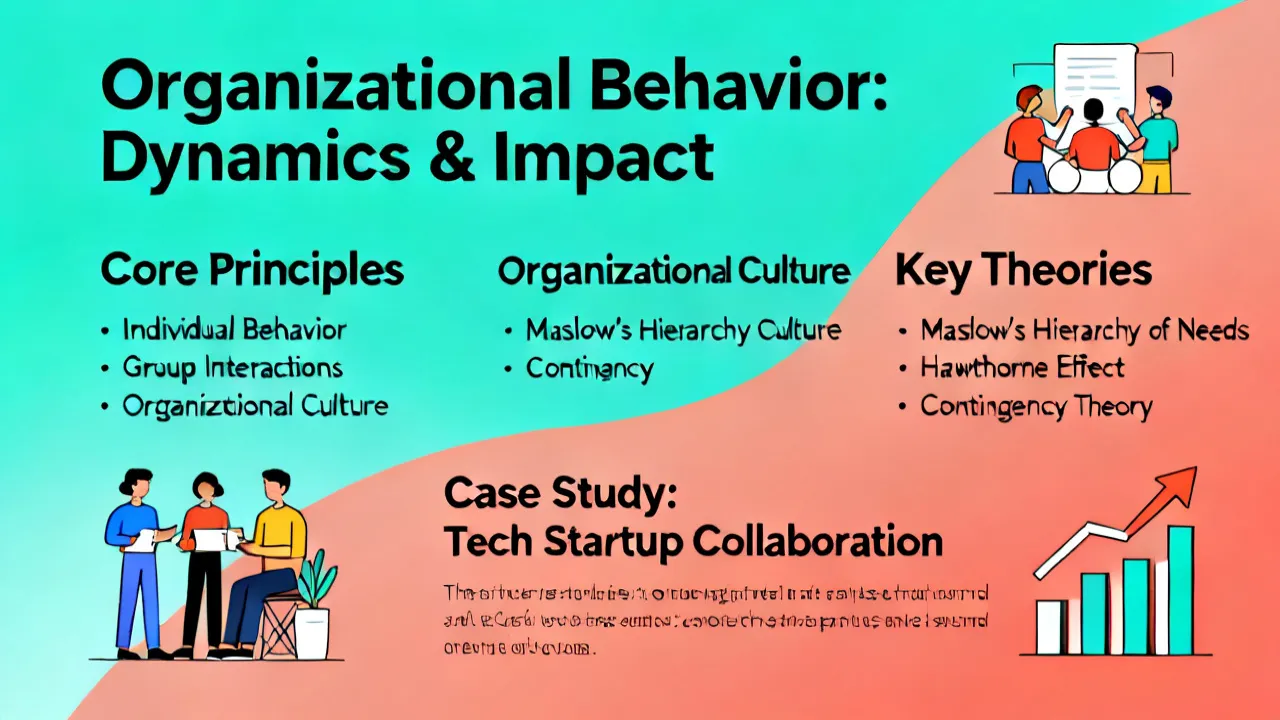
Understanding Organisational Behaviour Slideshare
This article delves into the significance of Organisational Behaviour Slideshare for both educators and professionals. Organisational Behavior is a field that examines the impact individuals, groups, and structures have on behavior within organizations, aiming to improve an organization's effectiveness. With Slideshare's platform, these insights are easily shared, promoting a collaborative learning environment.
Understanding Ltda Epp for Supplier and Compliance Decisions
Learn how “Ltda Epp” impacts supplier selection, contract structure, and compliance planning. This guide explains, in objective terms, what the label typically signals in company registration and how it can affect procurement processes, risk checks, and document readiness. It also frames practical conditions, comparison points, and decision steps to help you evaluate suppliers with clarity and consistency.
