This guide explains how Intuit Payroll works in real-world operations, from choosing a payroll plan to configuring filings and pay runs. It then provides objective context on payroll systems, compliance considerations, and implementation top practices. Readers get a clear overview of what to confirm before go-live, how to maintain accurate employee records, and which checks reduce avoidable processing errors.
Intuit Payroll supports accurate, organized payroll processing by centralizing employee details, calculating pay based on your configured rules, and helping you manage recurring pay runs. For many organizations, the practical value is less about “one-time setup” and more about creating a consistent workflow—so payroll is processed on schedule, records remain auditable, and corrections can be handled efficiently when employee information changes.
From an industry perspective, the very important decisions are usually the ones made before the first pay run: selecting the right payroll settings, confirming tax-related requirements for your workforce, aligning payroll schedules with your HR data, and ensuring that approvals and exceptions are handled with a repeatable process.
In day-to-day operations, payroll is rarely a single event. It’s a chain of activities that begins long before employees see their deposits: HR captures new hire details, managers validate time or earnings, payroll administrators check for missing data, approvals are completed, and finance prepares for reconciliation. Intuit Payroll aims to place many of those activities into a single, coordinated process—so your team isn’t rebuilding the payroll story from spreadsheets every cycle.
That “cycle consistency” matters because payroll errors tend to compound. A misconfigured pay rate or deduction doesn’t just affect one check; it can carry into subsequent pay periods, create reconciliation mismatches, and generate compliance exposure. When a payroll platform supports structured data entry, consistent period handling, and clear documentation of adjustments, it lowers the likelihood that a small mistake becomes a month-long remediation effort.
In practical terms, employers often feel the benefits of Intuit Payroll in a few consistent places: faster preparation for standard pay cycles, clearer visibility into what changed between periods, fewer ad hoc corrections because rules are pre-defined, and reporting outputs that can be used as inputs for accounting close. These improvements do not eliminate the need for careful review, but they can make the review more reliable—because the system provides structured outputs and history.
Payroll is a core business function that sits at the intersection of HR data accuracy, financial reporting, and regulatory compliance. When payroll systems are configured thoughtfully, they reduce manual data handling, help standardize calculations, and provide clearer audit trails for internal controls. A mature payroll workflow typically includes:
For employers evaluating Intuit Payroll, the goal is not only to “run payroll,” but to build a dependable operating rhythm: payroll preparation → verification → processing → payment distribution → reporting → review.
When you describe a payroll platform’s value this way, it becomes easier to evaluate “good.” Good is not simply accurate calculations. Good is also operational clarity: the right people know when they need to act, the organization has a consistent checklist for each period, and the system’s outputs can be trusted as the source of truth—especially when accounting needs reconcile amounts and when audits require evidence.
One way to define good payroll operations is to imagine a new payroll administrator joining halfway through the year. In a strong setup, they can quickly understand how pay periods work, where exceptions are handled, how corrections are approved, what documentation must be retained, and where key reports are generated. In a weaker setup, the new hire must ask many questions and rely on undocumented tribal knowledge.
Payroll platforms matter because they can reduce that reliance on tribal knowledge. Centralizing employee details and pay rules can be more than a convenience; it can be a control mechanism. Instead of multiple people maintaining separate versions of employee data and pay calculations, a single configured workflow ensures the calculations follow established rules.
It’s also worth acknowledging that payroll is often impacted by time-based data. For organizations with variable hours, timekeeping systems produce raw inputs that payroll transforms into pay statements. Even if you don’t integrate timekeeping, payroll still depends on timely and accurate inputs—such as hours, earned time, sick leave balances (where applicable), commissions, or custom earnings. Good payroll platforms support predictable handling of those inputs so the organization can meet compliance timelines.
Finally, payroll platforms matter because of trust. Employees expect payroll to be timely and accurate. When payroll is late or incorrect, it can erode confidence in the company. While employees may not see the behind-the-scenes workflow, they feel its consequences immediately. A payroll system that supports repeatability, documentation, and corrections can help maintain that trust.
While specific features can vary by plan and configuration, employers typically look for tools that cover the full lifecycle of payroll. In practice, teams evaluate Intuit Payroll against a checklist that includes:
As an expert, I recommend that you assess these items using a “day in the life” test—simulate a full pay cycle (including adjustments) and confirm that the system supports how your organization actually works.
To make this practical, think through the typical sequence of events for a payroll cycle in your organization and test Intuit Payroll against it. For example, ask: What happens when a new hire’s start date falls near a cutoff? What happens when a termination date is entered after hours have already been submitted? What happens when a manager requests an adjustment after payroll has been processed? Does the system provide a structured correction workflow (or at least a way to document and track the correction)?
Beyond the categories listed above, many employers also evaluate payroll capabilities through “operational questions,” such as:
In day-to-day use, another key capability is the platform’s ability to support “standardization without rigidity.” Payroll settings must be consistent enough to reduce errors, yet flexible enough to accommodate legitimate exceptions. That balance is what many employers experience as “workflow maturity.”
Consider also the difference between “processing” and “managing.” Some tools focus heavily on running calculations but provide weaker support for planning and review. A mature payroll platform helps you prepare for the next run—so the organization can confirm that employees are set correctly before the processing window.
In other words, you should judge Intuit Payroll not only on what it does during the pay run, but on what it enables before and after. Preparation and review are where many errors are prevented, while structured outputs and history reduce the time needed for corrections and reconciliation.
Regarding price information and supplier details: Intuit is the provider associated with Intuit Payroll, and pricing is commonly determined by factors such as organization size, selected features, and operational needs. Because pricing can change and may differ by region and plan type, treat any displayed or quoted price as an estimate until you verify it directly through the official supplier channel.
Practical cost evaluation typically includes not only subscription cost, but also implementation effort, internal time for setup, training time, and the cost of potential rework if settings are configured incorrectly. In payroll, rework can be particularly expensive because it can affect employee trust, accounting timelines, and compliance documentation.
To evaluate total cost of ownership, it helps to separate costs into four buckets:
Many organizations underestimate implementation and rework costs. For example, a misalignment between payroll outputs and your chart of accounts might cause delays during month-end close. If that misalignment is discovered late—after several pay cycles—you might need to adjust mapping logic or manually reconcile totals for multiple months. That kind of cost isn’t always measured directly, but it shows up as time, stress, and delayed reporting.
Another hidden cost is training. Even if the payroll system is intuitive, payroll operations often require specialized knowledge: how deductions affect taxable wages, how exceptions should be documented, how retroactive changes are handled, and what evidence should be retained. Investing in training early typically reduces errors and shortens troubleshooting time later.
Also consider the broader ecosystem. If your organization uses HR software, timekeeping tools, benefit platforms, or accounting systems, any integration approach (manual exports, API connections, or data mapping) can influence total cost. Even when integrations aren’t available or aren’t necessary, there may be operational overhead from importing or exporting data each period.
Ultimately, the most responsible approach is to treat the software price as only one component of a larger business case. The “value” of Intuit Payroll should be measured in terms of saved time, improved accuracy, improved audit readiness, and reduced operational risk.
Before you process payroll for the first time, use a structured preparation phase. Many avoidable issues stem from missing or inconsistent HR inputs. A reliable setup phase includes:
This approach helps your team transition from “software installation” to “operational readiness.”
To expand this planning concept, consider that setup is not a one-time event. Even after go-live, you’ll revisit setup when you add new employees, add new deduction types, change pay schedules, implement benefits changes, or introduce new compensation elements such as bonuses or commissions.
So the goal in the initial setup is twofold: first, establish a payroll configuration that is correct; second, establish a configuration discipline that makes future changes safer. A payroll discipline includes:
For pay schedule definition, pay attention to cutoffs. Many payroll issues are really cutoff issues. If HR data is entered after a cutoff, your payroll system may not calculate correctly for that period. Or your organization might discover too late that a termination date was captured but the hours/deductions for that period were already processed. To reduce that risk, align cutoffs across HR, timekeeping (if applicable), and payroll.
For employee data standardization, the concept isn’t only “accuracy,” but also “consistency.” Payroll systems usually expect data in specific formats and categories. If employee records are inconsistent—such as different ways of labeling departments, or pay rate types that don’t match configured earning categories—the payroll calculation may still run, but the outputs may not match your internal logic.
When configuring payroll rules, define your recurring and one-time compensation patterns clearly. Many organizations have recurring earnings (base salary, hourly wages, standard overtime rules) but also recurring deductions (benefits, garnishments, retirement contributions) and periodic adjustments (annual bonus, commissions). Each of those should be represented in the configuration in a way that mirrors how you actually run payroll.
Finally, the test pay cycle should not be “toy” data. It should represent real scenarios your organization experiences. Include at least one new hire case, one adjustment case (such as retro pay or a deduction change), and one edge case around cutoff timing. That approach reduces the risk that the system looks correct in a simplified test but fails in production.
Payroll systems influence how organizations collect, store, and report compensation-related information. While Intuit Payroll can support structured processing and reporting, responsibility for correct filings and compliance outcomes remains with the employer (and relevant professionals). Therefore, a thoughtful implementation should consider:
If your organization uses external accountants or payroll specialists, align early on: what reports they need, how you want corrections handled, and which data fields should be prioritized for accuracy.
Compliance is often discussed as “tax settings,” but it’s broader than that. Payroll affects income tax withholding, wage reporting, potentially unemployment and other contributions, and benefits-related reporting depending on jurisdiction. It also interacts with employment laws regarding wage deductions, timing of final pay, and recordkeeping requirements.
From an audit perspective, your payroll records must be both complete and understandable. Even if the calculations are correct, auditors often need to see evidence that: (1) payroll inputs were approved, (2) payroll rules were applied consistently, (3) adjustments can be traced back to specific requests and approvals, and (4) payroll records can be retained for the required retention period.
This is why workflow design is part of compliance. A payroll platform that supports role-based access, documented approvals, and change tracking (where available) can materially improve audit readiness. But the system alone is not enough. You need internal processes that ensure the right people authorize changes and that documentation is retained.
Consider also how payroll interacts with accounting close. Month-end close often requires summarizing payroll costs into appropriate accounts and producing reconciliations for accounts such as salaries expense, payroll liabilities, and taxes payable. If your payroll outputs aren’t aligned to your accounting expectations, you might create manual adjustments or reclassification entries. Those manual steps can introduce error and complicate audit trails.
To support compliance, ensure that the system’s reporting is available in a format that can be archived and reviewed. Internal policies should specify where payroll reports and supporting documents are stored and who is responsible for retention.
Finally, align with professional guidance. Payroll often changes due to new regulations, and systems can be updated as tax rules evolve. Your operational responsibility remains: verify the configuration, validate outputs, and consult professional support as needed for jurisdiction-specific requirements.
Use the following comparison table as a supplement to your evaluation. It focuses on practical criteria you can verify during onboarding and test processing. (No links are provided in the table.)
| Evaluation area | What to check for Intuit Payroll | Why it matters |
|---|---|---|
| Setup readiness | Whether employee data import, pay schedules, and deduction categories can be configured cleanly | Reduces first-run errors and rework |
| Pay run workflow | How you prepare, review, and process pay periods; whether exception handling is clear | Improves cycle consistency and approval clarity |
| Reporting outputs | Payroll summaries and reconciliation-friendly reporting for accounting review | Supports month-end close without manual extraction |
| Audit traceability | Availability of payroll history, adjustment records, and evidence of changes | Helps internal audits and compliance reviews |
| Operational support | Documentation quality and help resources available to your administrators | Shortens troubleshooting time during pay cycles |
| Total cost of ownership | Subscription pricing plus internal time and training effort | Reflects the true cost beyond the sticker price |
When you use this table, don’t treat it like a checklist you “finish.” Use it as a set of questions to drive your test pay cycle. For example, under “audit traceability,” test a correction scenario and confirm that the resulting payroll history and adjustment records are easy to locate and explain. Under “reporting outputs,” run through a month-end style reconciliation and validate that the reports contain the fields finance needs, in a format they can use.
Also consider your own organizational constraints. A small business might prioritize ease of use and quick setup. A larger enterprise might prioritize workflow controls, audit readiness, and deeper reporting. A payroll platform can be “good” for one type of organization and not optimal for another, so evaluate based on your operating model.
Every implementation has its unique details, but payroll systems generally require you to meet basic operational conditions. Consider these requirements as a checklist:
To elaborate, “accurate employee records” should be interpreted broadly. Accuracy includes correct pay frequency, correct employment status, correct classification, correct deduction eligibility, and correct start/end dates. Even when a pay calculation can proceed with missing data, incomplete data can yield incorrect results that you might not detect until after employees are paid.
For “approved payroll policies,” take time to define the exceptions. Exceptions are where payroll risk often concentrates. Examples include: retroactive rate changes, one-time bonuses, mid-period deduction changes, garnishments adjustments, and corrections for timekeeping errors. If you don’t define who can approve these exceptions and how to document them, you may end up relying on informal agreements that don’t hold up during reviews or audits.
For “consistent cutoffs,” ensure the system’s pay period calendar matches operational deadlines. Many payroll systems allow you to define cutoffs or rely on configured pay periods. If HR or timekeeping teams deliver data late, payroll results may shift between pay periods. That can be especially problematic for organizations that reconcile by period.
For “accounting alignment,” verify not only the totals but also the categories. Finance needs to know where payroll expense and payroll liabilities appear in the ledger. For example, taxes payable might need to be separated by type, while benefits contributions may need their own accounts. Testing reconciliation early can reveal mismatches before the first close.
For “access control,” adopt a principle of least privilege. Payroll settings and processing actions should not be editable by everyone. Define role groups: payroll administrators, approvers, and financial reviewers. Even if you use a small team, formalize roles so changes are intentional and traceable.
Below is a practical, step-by-step guide designed for organizations transitioning to Intuit Payroll or standing up payroll for the first time. This is not about “speed”; it’s about controlled accuracy.
This structured month helps minimize the operational stress that often accompanies payroll changes.
To further reduce risk, you can add two practical techniques to this month plan: (1) a “payroll runbook” and (2) a “discrepancy log.” A runbook is a short internal document that describes the steps for each payroll cycle. It includes who does what, when approvals happen, which reports are reviewed, and what the escalation path is if an issue appears. A discrepancy log is a place to record any differences found during testing and parallel review—what caused the difference, how it was resolved, and what evidence supports the final decision.
These two techniques may seem administrative, but in payroll they become time-saving assets. When a discrepancy emerges during a pay run, your team doesn’t have to interpret it from scratch. They can check whether it resembles a prior issue, whether it requires reconfiguration, or whether it was already resolved during testing.
Another risk-reduction practice is to create a small “test matrix” of employee scenarios. Even if you don’t have many employees, create test cases for the types of changes your payroll must handle. A test matrix could include:
This matrix helps ensure you’re not only testing the “happy path.” Payroll systems are often accurate in straightforward cases but require special handling for boundaries, retroactivity, and adjustments. The test matrix ensures those are validated.
During Week 3 testing, it’s also beneficial to involve a secondary reviewer if feasible. The secondary reviewer can be someone from finance or HR who compares outputs to expectations. The goal isn’t to “audit” the system manually but to catch configuration mismatches early.
During Week 4 parallel review, define what you will consider “success.” For example, success might mean: totals for gross pay and net pay match expected calculations within a defined tolerance; employee-level pay statements match expected scenarios; and reports required for accounting close are available and complete. If you find differences, assign root-cause responsibility and document how you’ll prevent recurrence.
Finally, before go-live, confirm that employees will be paid on schedule. Payroll is time-sensitive. The operational rhythm includes not only configuration but also communication. If employees need to be informed of payday dates, direct deposit updates, or final pay details in case of terminations, include those steps in your workflow runbook.
Intuit Payroll is used by employers to manage payroll processing—organizing employee compensation details, calculating pay for scheduled pay periods, and producing payroll-related reporting for review and accounting reconciliation.
In many organizations, it also serves as the system of record for payroll history. That matters because payroll is not only “payments” but also records used for financial reporting, employee inquiries, and audit support. When payroll history is accessible and structured, it becomes easier to respond to questions like: “What was the net pay for this employee last period?” or “How did that deduction change affect wages?”
Pricing is typically influenced by plan selection and organizational needs. Since pricing can change, you should confirm the current subscription terms directly with the supplier and document what is included in your plan (features, number of employees, and any add-on capabilities).
When you ask for pricing, also request clarity on what triggers additional fees. Some plans price by number of employees, some by payroll runs, and some by included features (like advanced reporting or additional support). The goal is to estimate your total annual cost based on how you actually plan to operate, not just the base subscription price.
You generally need accurate employee information (pay rates, pay frequency, employment status) and a clear view of how earnings and deductions should be applied. If your organization uses timekeeping inputs, ensure those processes provide consistent and complete data by the payroll cutoff.
To be thorough, create a data checklist aligned to payroll categories. That checklist might include: employee identifiers, pay rate amounts, pay frequency, effective dates for pay changes, deduction definitions, employment status, location or jurisdiction data (when relevant), and any special compensation items like bonuses or reimbursements. You also need to confirm how those data points map into the payroll system’s configuration.
Very payroll workflows support adjustments, but the ability to correct depends on your operational timing and the configuration of pay rules. Establish a correction policy in advance—who requests it, who approves it, and how you document the change.
Corrections often fall into two broad categories: (1) corrections that should be processed through an adjustment run or retroactive logic, and (2) corrections that require special handling like reprocessing or offsetting. Your internal policy should define which category applies to different issues—like a data entry error versus a policy-approved retro pay adjustment—so payroll administrators aren’t making inconsistent decisions during stressful periods.
Payroll software can support structured processing, but compliance responsibility remains with the employer (and any engaged tax or legal professionals). Use the system outputs as inputs to your compliance workflow, and validate withholding and reporting settings according to your jurisdiction and professional guidance.
Compliance is also about consistency. Even if the system calculates correctly, you still need to ensure that you file required reports on time and retain records for the correct retention period. Consider setting internal deadlines that align with payroll processing timelines but also leave room for review and corrections.
Start with a controlled diagnosis: confirm employee pay rate and deduction settings, verify pay period dates and hours inputs (if applicable), and review any special adjustments. Then compare the system outputs to your internal calculation logic and seek professional support if needed.
A practical troubleshooting approach is to treat the issue like a problem in a workflow, not just a “wrong number.” Ask: Did the issue come from employee data, pay period settings, timekeeping inputs, or configuration rules? By narrowing down the point of failure, you can resolve the issue faster and prevent recurrence.
Also consider that payroll problems sometimes emerge from timing. For example, if an adjustment was entered after payroll cutoff, the system may correctly apply it in the next pay period rather than the current one. This can look like a “calculation error” but is actually a period alignment issue. Checking cutoffs and effective dates can quickly clarify the situation.
Many organizations choose payroll platforms because they scale operationally. The key is to ensure the payroll workflow—permissions, approvals, employee onboarding steps, and reporting—can keep pace as headcount and pay complexity increase.
Growth introduces complexity. As you add employees, you must ensure onboarding data is correct and consistent. As you add locations, payroll may introduce additional jurisdictional factors. As you add compensation elements, payroll rules must be expanded carefully. A payroll platform can help you scale, but only if your internal processes for approvals, testing, and configuration management mature alongside it.
Record retention requirements vary by jurisdiction and organizational policy. As a top practice, retain payroll outputs, audit evidence, and documentation related to adjustments for the period required by applicable regulations and your internal control policies.
When deciding what to retain, treat payroll records as a combination of results and evidence. Results include pay statements, payroll summaries, and reports used for accounting. Evidence includes approval records, adjustment documentation, and configuration references (such as effective dates and rule changes). Retaining both categories helps you respond to employee questions and supports compliance audits.
For compliance and recordkeeping principles, employers can consult official guidance from relevant government agencies and credible professional publications. In the U.S., for example, tax and payroll reporting concepts are informed by materials from the Internal Revenue Service (IRS), and employment recordkeeping practices are supported by the U.S. Department of Labor (DOL) resources. Always align your payroll configuration with current official guidance.
Because payroll regulations can change, a good operational practice is to assign ownership for compliance monitoring. That could be a payroll administrator, an accounting lead, or an external specialist, depending on organizational size. The point is to ensure you aren’t relying on outdated assumptions about tax rates, filing requirements, or reporting formats.
Also consider that payroll accuracy isn’t only about calculations—it includes the data used to calculate them. If official guidance indicates changes to how certain items should be treated, your internal data inputs and configuration rules must be updated accordingly. Treat payroll configuration as an ongoing responsibility, not a set-and-forget task.
Intuit Payroll can be a strong operational foundation when implemented with discipline: correct inputs, clear approvals, test cycles, and consistent reconciliation. If you approach setup as an internal control workflow—rather than a one-time configuration—you reduce the likelihood of errors and improve confidence in every subsequent pay run.
When payroll is treated as a system, every cycle becomes an opportunity to strengthen reliability. Preparation improves because you learn from prior discrepancies. Reporting improves because you refine how outputs match finance’s needs. Audit readiness improves because you maintain evidence and ensure changes are traceable.
In the end, a payroll platform should help you execute a predictable process—so the organization can spend less time troubleshooting and more time ensuring that employees are paid correctly, on time, and with confidence. The most successful payroll implementations are the ones where software capability and operational discipline meet: a well-configured system plus a clear workflow that your team can follow consistently.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

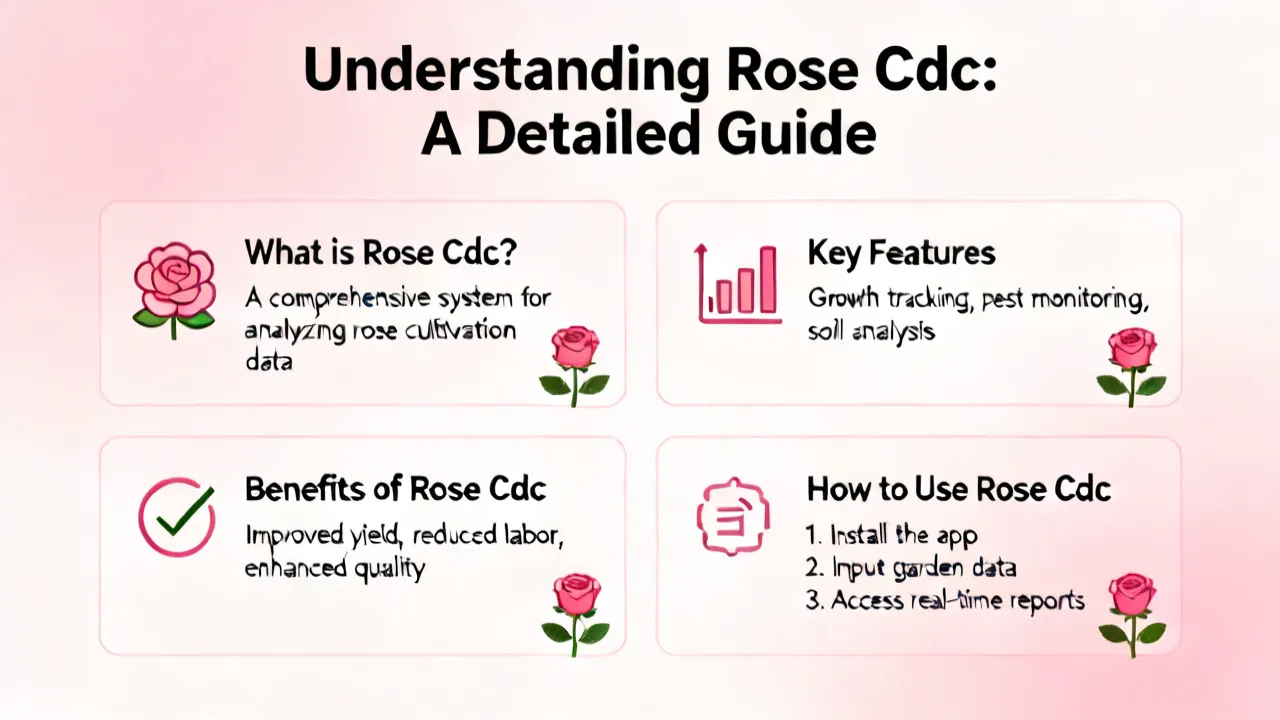
Understanding Rose Cdc: A Comprehensive Guide
This article provides an in-depth exploration of Rose Cdc, a term rapidly gaining attention in specific industries. Our discussion delves into the significance and application of Rose Cdc, its potential impact on various sectors, and expert insights into its future developments. This comprehensive analysis is designed to inform readers about the multifaceted aspects of Rose Cdc, its current applications, and potential advancements.
Understanding Compliance and AML Strategies
This article delves into the intricate realm of Compliance and Anti-Money Laundering (AML) strategies, highlighting their significance in the corporate world. Compliance AML refers to the organizational adherence to legal standards and regulations to deter financial crimes, ensuring transparent and ethical financial practices. This comprehensive guide examines these strategies' complexities and their pivotal role in safeguarding economic integrity.
Mastering Inbound B2B Strategies
The foundation of successful B2B strategies often lies in the effective implementation of inbound marketing techniques. In today's globally connected business environment, inbound B2B strategies have become critical for companies seeking to engage target audiences, optimize lead generation, and establish long-lasting partnerships. Understanding these strategies is essential for companies aiming to thrive in competitive markets.
Exploring B2B MBA Opportunities
Dive into the dynamic world of B2B MBA programs, designed for professionals seeking to enhance their strategic and management skills in a business-to-business context. This comprehensive guide discusses the significance of B2B MBAs in today's market, highlighting how these programs equip leaders with the expertise to navigate complex B2B relationships and drive business success.
Understanding Whitewater Regenerative Blowers
Whitewater Regenerative Blowers are essential in various industrial applications for their efficiency in moving air and gases. These blowers are known for their durability and ability to operate continuously, making them a preferred choice for industries ranging from wastewater treatment to aquaculture. This article explores their features, benefits, and applications, offering readers a comprehensive understanding of their importance in modern industry.
Mastering Employee Retention Strategies
Employee retention has become a critical aspect of organizational success, particularly in the dynamic landscape of 2020. As businesses strive to maintain a stable and productive workforce, understanding effective retention strategies is essential. This article delves into key methods for enhancing employee satisfaction and retention, offering a comprehensive guide for HR professionals and business leaders alike.
